


You've found a place you want, but you're unsure what to offer or how far to stretch. I'd decide your opening price and maximum before the agent calls back, then check which dates you can safely offer.
That’s why I’d check the seller’s timing before offering more money. Katie’s purchase in Albion is a good example: we helped her offer a 25 day settlement instead of the other buyer’s 75 days. The seller chose her even though the competing offer was higher and in cash.
- 01 / Value
Set your price range
Start with what similar homes sold for, then decide how much you’re willing to pay.
- 02 / Terms
Check your finance dates
Find out how long your lender needs before promising the seller a quick answer.
- 03 / Protection
Put the terms together
Choose the price, conditions and settlement date together. Each one affects the offer.
How much below asking price should you offer?
Sometimes the right offer is 10% below asking. Sometimes asking price is already low and even a full price offer will miss out. The percentage by itself tells you very little.
I’d look at 4 things: recent comparable sales, the home’s condition, how long it has been for sale and how much genuine competition exists. Then I’d choose an opening price and a separate maximum price.
If the agent says several buyers are competing, our multiple-offer guide explains what to confirm before submitting your final number.
| What you find | What it may mean for your offer |
|---|---|
| The asking price sits above recent comparable sales | A lower offer is easier to support. Show the closest settled evidence rather than saying the home feels overpriced. |
| The property needs clear repairs or updating | Allow for the work, but use inspection evidence and realistic costs. Don’t simply subtract a renovation wish list. |
| The listing has been live for weeks with little interest | There may be more room to negotiate, especially if your timing helps the seller. |
| Several written offers are due at once | Confirm whether this is best and final. You may not get another chance, so stay inside your true limit. |
| The property is deliberately priced to attract competition | Asking price may not be a useful guide. Comparable sales and your maximum price matter more. |
How the evidence can change an opening offer
The asking price sits above recent comparable sales
- What it may mean for your offer
- A lower offer is easier to support. Show the closest settled evidence rather than saying the home feels overpriced.
The property needs clear repairs or updating
- What it may mean for your offer
- Allow for the work, but use inspection evidence and realistic costs. Don’t simply subtract a renovation wish list.
The listing has been live for weeks with little interest
- What it may mean for your offer
- There may be more room to negotiate, especially if your timing helps the seller.
Several written offers are due at once
- What it may mean for your offer
- Confirm whether this is best and final. You may not get another chance, so stay inside your true limit.
The property is deliberately priced to attract competition
- What it may mean for your offer
- Asking price may not be a useful guide. Comparable sales and your maximum price matter more.
Step 1: Work out what the property is worth to you
I start with recent settled sales for similar homes in the same suburb, or nearby. I compare land size, internal area, condition, bedrooms and bathrooms to see whether the asking price stacks up.
For an apartment, I go closer again. I compare the building, floor, aspect, car space, body corporate costs and internal area.
Online estimates can help you find a starting point. I'd check them against the sales before choosing a price. Our property valuation guide walks through the comparison. If you're still organising your budget and loan, start with how to buy a house.
Herron Todd White's Month in Review can help you understand the broader market before you negotiate. Read the commentary for your area alongside the recent settled sales for homes like the one you're considering.
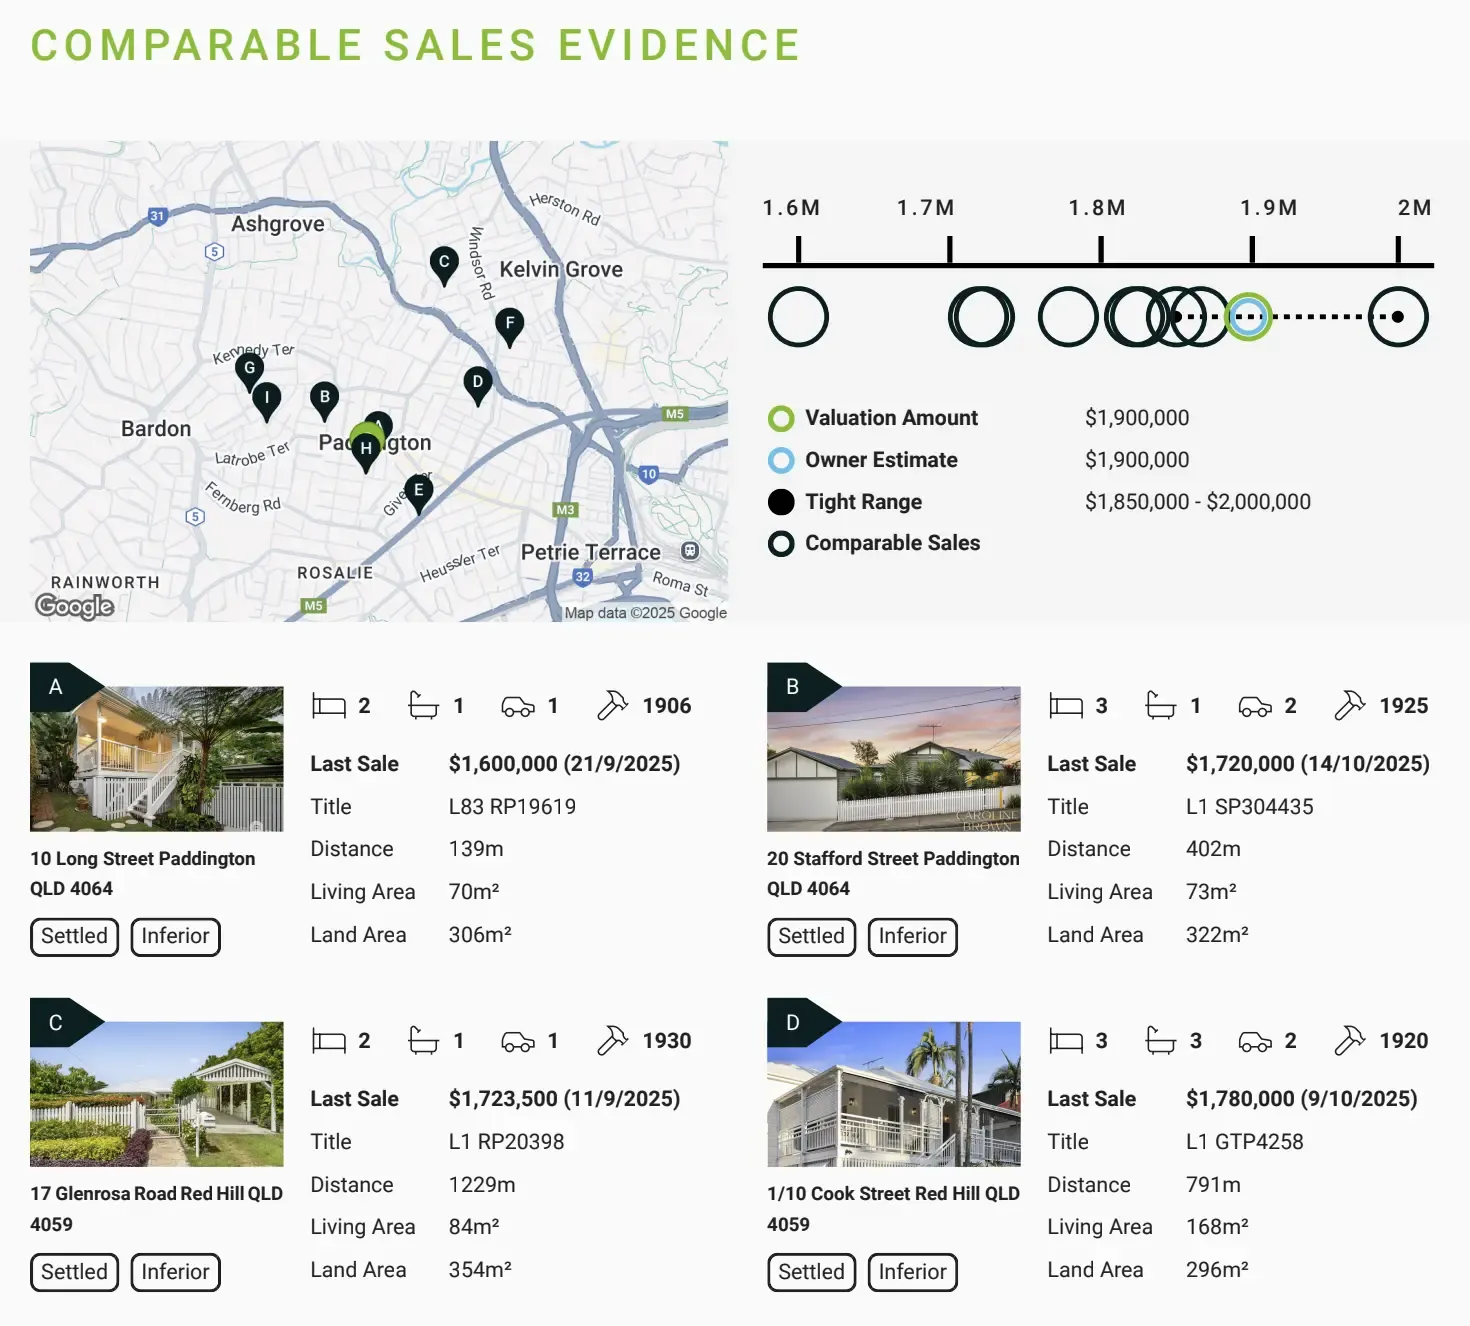
Use the same comparable sales worksheet we give buyers
How to use it
- Open the How to Use tab, then start in Simple Check with the property you're considering.
- Find 3 to 5 recent settled sales and paste the source links into the worksheet. Complete the yellow input cells.
- Rate each sale as Good, Fair or Weak based on how closely it matches. The worksheet gives stronger comparisons more weight.
- Check the adjustments against local evidence. The starting assumptions may need changing for your suburb or property type.
- Record your preferred price and maximum price, then compare that limit with your pre-approval, available cash, repayments and buying costs.
Download the comparable sales worksheet. Use recent sales and local evidence to check its starting assumptions.
Why do so many listings have no price?
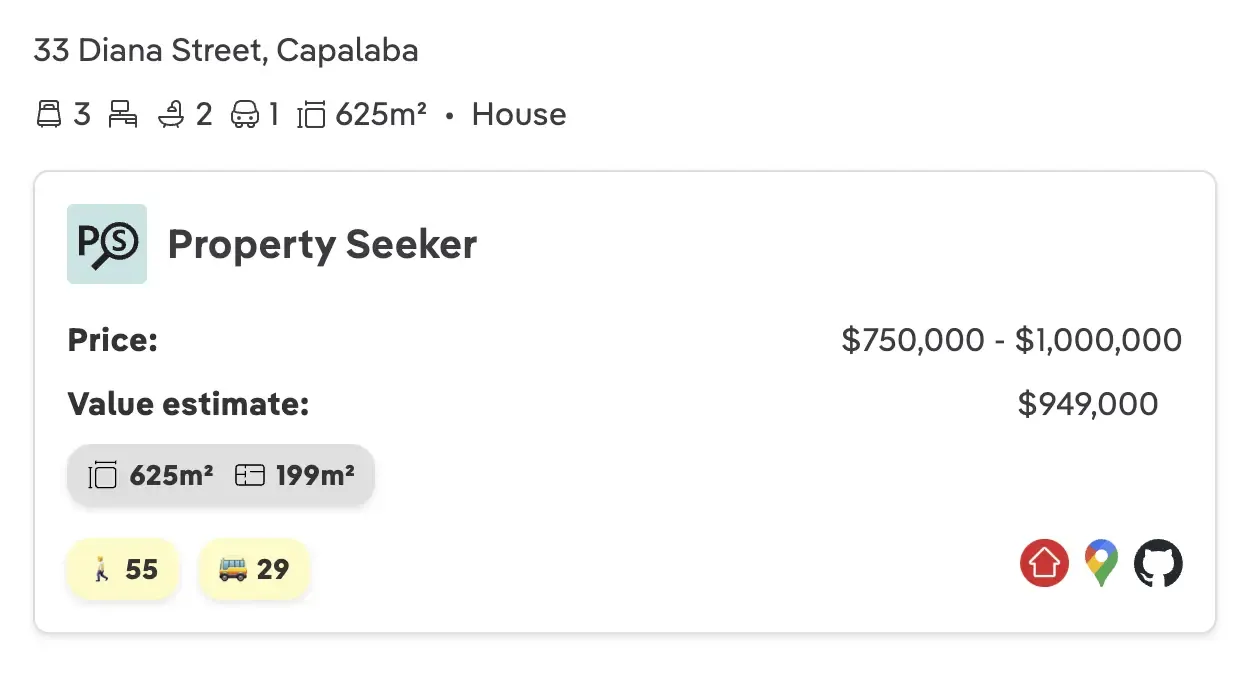
A listing without a price makes it harder to know whether a property belongs on your shortlist. In Queensland, agents can't disclose an auction reserve or price guide. A private seller can also instruct the agent not to disclose their asking price. The Queensland rules on price disclosure explain the distinction.
The Property Seeker Chrome extension can reveal advertising ranges on supported property websites. Use that range to organise your search, then check the home against settled sales. It doesn't establish what the seller will accept or what the property is worth.
Set 3 prices before you negotiate
- 01 / Start here
Your opening offer
Choose an opening price you can support with recent sales and the property’s condition.
- 02 / Check the evidence
The likely market range
This is where the closest settled sales suggest the property should trade after adjusting for its differences.
- 03 / Set your limit
Your maximum price
The most you’re willing and able to pay. Write it down before another buyer appears.
Step 2: Check the finance deadline you can offer
A 7 day finance clause can make your offer more appealing when the seller wants a quick decision. You keep a finance condition, and the seller gets an earlier date to find out whether your loan is approved.
Get us involved before choosing that date. We'll check your assessed pre-approval, current documents, the property and any valuation, then confirm the lender's expected timing. That preparation can give you more options than leaving the loan application until after you've signed. Our home loan pre-approval guide explains how to get ready.
What we check before recommending 7 days
- An assessed pre-approval, with any conditions identified and current income documents ready.
- The property checked against the lender's requirements, with any valuation arranged or its timing confirmed.
- The lender's current assessment time checked for your application, including any further credit review.
- An exact finance date confirmed with your solicitor, allowing for weekends, public holidays and time to give the required notice.
Client story
How a 5 day finance clause secured the home
Rachel and Emma were competing for a Brisbane property above $1.7m. The agent made it clear that a standard 14 day finance period would struggle against the other offers.
Their application had already been assessed, and their pre-approval was in place. We had current income documents, had checked that the property met the lender’s requirements, and were ready to lodge the signed contract on Monday morning.
After checking the timing, they set the finance deadline for 5pm Friday.
The seller got a fast, clear decision date, while Rachel and Emma kept the finance protection they still needed. Their offer was accepted.
Client story
When a 7 day finance period ran into Christmas
Ethan and his partner had missed out at auction. With pre-approval arranged before the auction, they wanted to know whether they could leave out the finance condition or offer 7 days.
They were asking on 24 December. Lender credit teams had fewer staff available, and formal approval was unlikely before early January. Their application was ready, but the holiday period changed the timing we could recommend.
Before choosing a short finance period, have your broker check the lender's working days and your solicitor confirm the exact contract deadline. That avoids relying on a turnaround the lender can usually achieve when its team is fully available.
Find out what finance deadline you can offer
We’ll check your pre-approval, whether the lender needs a valuation and how long approval is likely to take before you commit to a finance date.
or call 1300 088 065
Have the contract and proposed dates handy.
Step 3: Find out how the seller will choose an offer
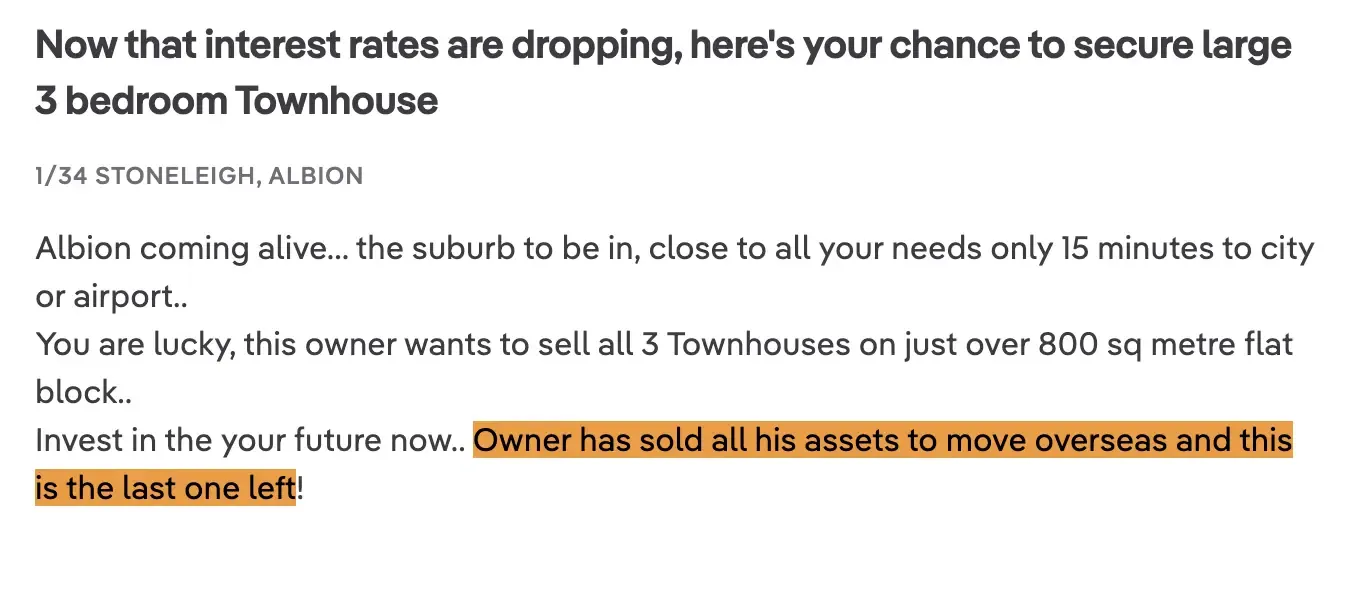
Ask the agent how this sale will work. One agent may negotiate back and forth. Another may ask every buyer for their best and final offer. A seller may also accept before an advertised deadline.
Find out whether you’ll get a chance to negotiate before you choose your opening price. Our guide to negotiating a house price with the agent covers the phone calls and counteroffers in more detail.
Questions to ask the agent
- How long has the property been on the market, and has the asking price changed?
- Why is the seller moving, and is there a preferred settlement date?
- Has a previous contract fallen over? If so, why?
- Are there other written offers?
- When do offers close, and can the seller accept one earlier?
- Is this best and final, or will buyers have another chance to negotiate?
- Can I have the contract and disclosure documents now?
Client story
How $2,999 helped Jordan in a best and final round
Jordan was preparing a best and final offer around $780k. The agent said there would be no negotiation and suggested using a non round number to reduce the chance of a tie.
After checking the extra cash contribution, Jordan offered $782,999 and secured the property. The extra $2,999 stayed within the maximum he’d already set.
Step 4: Inspect the property and check what you can’t see
Give yourself time to inspect properly, ideally more than once. Arrange the building, pest and other checks the property needs. Depending on the sale process, you may complete checks before signing or include contract conditions that give you time to act on the results.
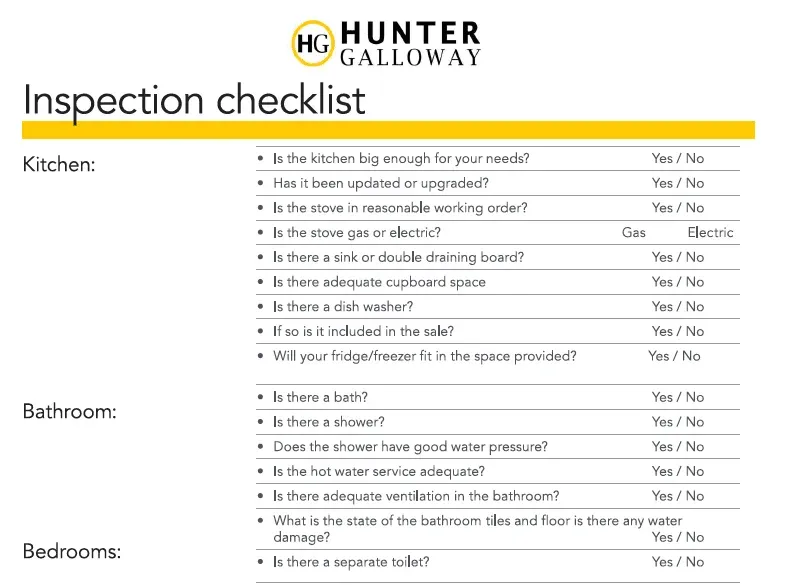
Look beyond the fresh paint
- Visible damage, drainage, access, street noise and costly parts of the home.
- Body corporate records, levies and planned works for an apartment or townhouse.
- Lease terms and vacant-possession timing if the property is tenanted.
- Flooding, planning, school catchments and local issues that matter to you.
- Whether the home still meets your needs.
Download our property inspection checklist and read our Brisbane FloodWise report guide before relying on a quick walkthrough.
Client story
How property searches helped our buyers negotiate $20k
Our buyers asked their solicitor to complete the property searches before the contract went unconditional. The searches showed that a carport didn't appear to have council approval.
They investigated what that meant for the property and the likely cost. The evidence helped them negotiate a settlement adjustment of about $20k, and they completed the purchase.
Ask your solicitor which searches to order while your contract still gives you time to act on the result. A building inspection and a council-approval search answer different questions.
Queensland seller disclosure changed in 2025
Since 1 August 2025, Queensland sellers generally need to give buyers a seller disclosure statement and prescribed certificates before the buyer signs the contract. It is useful information, but it doesn’t replace your own legal advice, building and pest inspection or searches.
The official Form 2 warns that it doesn’t cover everything buyers commonly care about, including flooding history, structural soundness, pest infestation and some building or development approvals. Read the Queensland Government seller disclosure overview and ask your legal adviser what else to investigate.
If required disclosure documents are missing, or information is materially inaccurate or incomplete, contact your solicitor promptly. A right to terminate can arise before settlement, but the tests and exceptions differ. For inaccurate or incomplete disclosure, the rules include whether you knew the true position and would have signed had you known it. Your solicitor can establish whether a right applies and give the required notice.
Buying a tenanted property
A tenancy doesn’t simply disappear at settlement. Review the lease, end date, rent, bond, arrears, notices and maintenance history. If you plan to move in, make sure the contract promises vacant possession on a date you can rely on.
Queensland and Victoria have different tenancy rules, so confirm the position with your legal adviser before making the offer.
Step 5: Have the contract reviewed before you sign
Buyers can spend days debating whether to offer $910k or $915k, then skim conditions that expose them to a much larger loss. Give the terms the same attention as the price.
The selling agent doesn’t act for you. Your solicitor or conveyancer should explain the contract, any special conditions and when the offer becomes binding. If you’re unsure who should help, see our comparison of a lawyer and conveyancer.
In Queensland, an offer is commonly made by signing the proposed contract, so review it before signing wherever possible.
| Term | What to check |
|---|---|
| Finance | The amount, lender and deadline should match the loan you’re applying for. |
| Building and pest | The wording controls what happens if the report finds a problem. |
| Settlement | The date needs to work for the seller, lender and your move. |
| Deposit | Confirm the amount, due date and where it will be held. |
| Inclusions | Record anything that must stay with the property. |
| Sale of another property | Get legal advice if this purchase depends on your existing sale. |
Common offer terms to confirm before signing
Finance
- What to check
- The amount, lender and deadline should match the loan you’re applying for.
Building and pest
- What to check
- The wording controls what happens if the report finds a problem.
Settlement
- What to check
- The date needs to work for the seller, lender and your move.
Deposit
- What to check
- Confirm the amount, due date and where it will be held.
Inclusions
- What to check
- Record anything that must stay with the property.
Sale of another property
- What to check
- Get legal advice if this purchase depends on your existing sale.
When do you pay the contract deposit?
A Queensland contract may split the deposit into an initial payment and a balance due on the date in the reference schedule. Check both dates and the named deposit holder, commonly the agent's trust account. Verify the payment details by calling a trusted number before transferring money.
The contract deposit is part of your overall contribution to the price. It can be due well before the lender releases funds, so confirm the money is available at the agreed time. If you're offering an unusually large deposit or payments before settlement, have your solicitor check the legal effect of that arrangement first.
Step 6: Shape an offer the seller can act on
The seller needs to know you can complete the purchase and meet the agreed dates. Make those terms clear alongside your price.
A lower offer can beat a higher one when its settlement date or conditions suit the seller and it feels more likely to reach settlement. Don’t remove a protection or promise a deadline you can’t safely meet just to look stronger.
Client story
How a broker call helped a financed offer compete with cash
Mark and Eliza found a home in Enoggera listed at around $980k. They were competing with an unconditional cash offer, and the seller preferred the certainty it offered.
We had already assessed their borrowing position up to about $1.05m. At their request, we called the agent and explained why a 7 day finance period was realistic for their application. They kept the finance condition and stayed within their price limit.
The seller accepted their offer. The call gave the seller a clearer picture of the preparation behind it. Final lender approval was still a separate step.
If an agent is concerned about your finance, ask us whether explaining the preparation would help. We can agree with you what information to share before making contact.
Client story
Katie beat a higher cash offer by settling sooner
Katie was competing for a house in Albion, Brisbane, against an investor who had offered more money and could pay cash. But the investor wanted a 75 day settlement.
The seller had already bought another home. They wanted to be out as soon as possible.
We helped Katie reshape her offer: $1,000 more than her original price, a 7 day finance clause and a 25 day settlement. Her price was still below the investor’s.
The seller chose Katie. She got the house because her timing suited their move.
Before increasing your price, ask what matters to the seller. A settlement date you can meet might make more difference than another few thousand dollars.
Check the steps after finance approval too
For a shorter settlement, confirm when the lender can issue the loan documents, how soon you can sign them and how long the lender needs to check them. Your solicitor also needs time to complete the legal work and coordinate settlement. Have your cash contribution and insurance ready. Our signed contract guide walks through those steps.
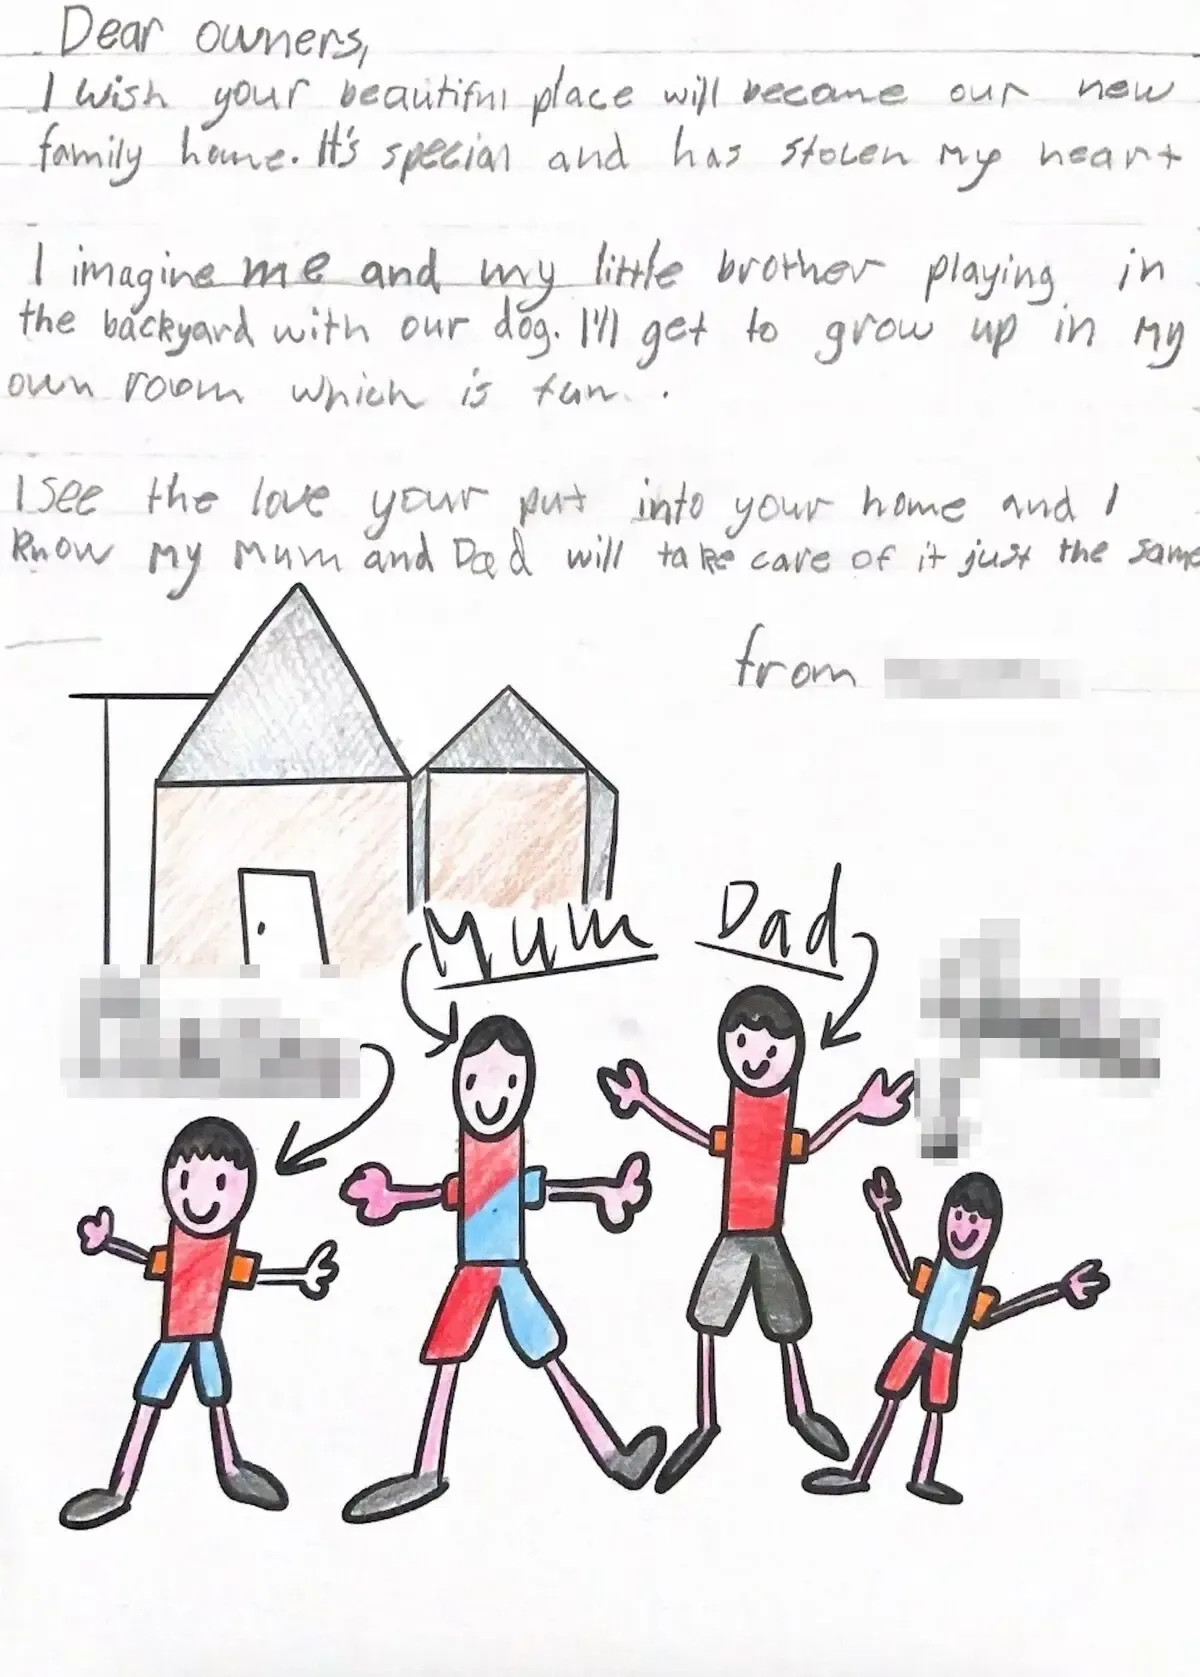
Should you write a personal letter to the seller?
A short, sincere note can help the seller understand why you like the home when 2 offers are otherwise close. Keep the price and workable terms at the centre of your offer.
Say what you appreciate about the home and that you’re organised and ready to proceed. Don’t reveal your maximum budget, promise that you’ll do anything to win or include sensitive personal information that is irrelevant to the sale.
Use the building and pest report as evidence
If the report identifies defects, get the inspector’s explanation and suitable repair quotes. Give those to your solicitor so they can check your options under the contract. Our guide to renegotiating after a building inspection covers that conversation.
Client story
How an inspection report helped Priya and Ben negotiate $17k
Priya and Ben’s report found termite damage and several smaller problems. They got advice on the repair costs and used the report to negotiate a $17k price reduction.
The report gave them specific problems and costs to discuss with the seller. Send yours to your solicitor while there’s still time to act under the inspection condition.
Step 7: Put the complete offer in writing
Ask the agent how the seller wants a formal offer submitted. It may begin with an email, expression of interest form or proposed contract. In Queensland, the agent may ask you to sign the contract as the offer.
Whatever the process, make sure every part of the offer is clear and your legal adviser has reviewed the contract before you sign. If you have already signed, use our contract-to-settlement checklist to keep the next deadlines moving.
What to include
- The property address and each buyer’s full legal name.
- The price, deposit amount and deposit due date.
- Finance and building and pest conditions and dates.
- The proposed settlement date or period.
- Any inclusions or exclusions.
- An offer expiry only if your legal adviser recommends one.
Written offer email template
Subject: Offer for [property address]
Hi [agent name],
I’d like to offer $[amount] for [property address].
Buyer name(s): [full legal names]
Deposit: $[amount], payable [when]
Finance: [condition and date, if applicable]
Building and pest: [condition and date, if applicable]
Settlement: [proposed date or period]
Inclusions or exclusions: [details]
Offer expiry: [only if reviewed and appropriate]
My solicitor or conveyancer is [name and contact details]. Please confirm how the seller wants the formal offer submitted and whether another process or deadline applies.
Regards,
[name]
How to handle a counteroffer
Before responding to a counteroffer, pull out your written price limit and ask what has changed. If the agent wants another $10k, find out whether the seller has also changed the settlement date, inclusions or conditions.
Ask why your first offer wasn't accepted. A timing problem gives you different options from a price the seller won't move on. You can accept, counter, hold your position, suggest a date that suits the seller or walk away.
When does an offer become binding?
A verbal “the seller likes it” doesn’t mean the property is yours. The binding point, cooling off rights and cost of withdrawing depend on the state, sale method and contract.
Cooling off is not the same as a finance condition, and auctions are generally unconditional. Don’t use cooling off as a substitute for advice before signing. If the home is going to auction, work through our buying at auction guide before you bid.
| State or territory | General position |
|---|---|
| Queensland | Generally 5 business days. Cancelling can cost up to 0.25% of the purchase price. Auction-related exceptions apply. |
| New South Wales | Usually 5 business days for an established home, or 10 for an off the plan purchase. Withdrawing usually costs 0.25%. Auction and waiver rules apply. |
| Victoria | Generally 3 clear business days. The cost is $100 or 0.2%, whichever is greater. Exceptions apply. |
| South Australia | Generally 2 clear business days after the later of signing and receiving the Form 1. Auction exceptions apply. |
| Western Australia | No mandatory cooling off period unless the parties add one to the contract. |
| Australian Capital Territory | Generally 5 clear working days. Withdrawing costs 0.25% of the price. Auction, tender and waiver exceptions apply. |
| Northern Territory | Generally 4 business days for property not sold at auction, with no cancellation penalty during that period. It may be changed by agreement. |
| Tasmania | No required statutory cooling off period. Seek advice on protections written into the contract. |
General cooling off position for a standard private residential sale
Queensland
- General position
- Generally 5 business days. Cancelling can cost up to 0.25% of the purchase price. Auction-related exceptions apply.
New South Wales
- General position
- Usually 5 business days for an established home, or 10 for an off the plan purchase. Withdrawing usually costs 0.25%. Auction and waiver rules apply.
Victoria
- General position
- Generally 3 clear business days. The cost is $100 or 0.2%, whichever is greater. Exceptions apply.
South Australia
- General position
- Generally 2 clear business days after the later of signing and receiving the Form 1. Auction exceptions apply.
Western Australia
- General position
- No mandatory cooling off period unless the parties add one to the contract.
Australian Capital Territory
- General position
- Generally 5 clear working days. Withdrawing costs 0.25% of the price. Auction, tender and waiver exceptions apply.
Northern Territory
- General position
- Generally 4 business days for property not sold at auction, with no cancellation penalty during that period. It may be changed by agreement.
Tasmania
- General position
- No required statutory cooling off period. Seek advice on protections written into the contract.
What to do when the seller accepts
Move quickly once you have the accepted contract
- Send the contractGive the signed contract to your solicitor or conveyancer and broker immediately.
- Record every deadlineAdd the deposit, finance, building and pest, insurance and settlement dates to your calendar.
- Complete the checksArrange inspections, valuation access and any documents the lender or legal adviser still needs.
- Protect the approvalCheck before changing jobs, opening credit or spending money needed for settlement.
- Inspect before settlementConfirm the property, inclusions and agreed work are in the required condition.
Arrange insurance early in Queensland
In most Queensland contracts, the buyer becomes responsible for the property from 5pm on the next business day after the contract date, which can be well before settlement. Check the exact risk date with your solicitor or conveyancer and arrange the cover the contract and lender require.
For an apartment or townhouse, check what the body corporate policy covers and what you still need to insure yourself. Read our guide to getting insurance after an offer is accepted.
A lender valuation is a separate check
Your lender will check what the property is worth before confirming the loan. Its valuation may differ from the contract price or an online estimate. If the contract price or terms change after acceptance, send the revised contract to your broker and legal adviser. The lender may need to confirm the updated position before the finance deadline.
Client story
Why a $15k price reduction still needed lender confirmation
Luca negotiated about $15k off after the contract had been accepted. The lower price helped, but the lender had assessed the original contract and loan amount.
We needed to send through the revised contract and obtain confirmation. Finance was due the next day, so we recommended that Luca ask his conveyancer for an extension.
Send an agreed price change to your broker straight away. Even a change in your favour needs to reach the lender before you rely on the updated figures.
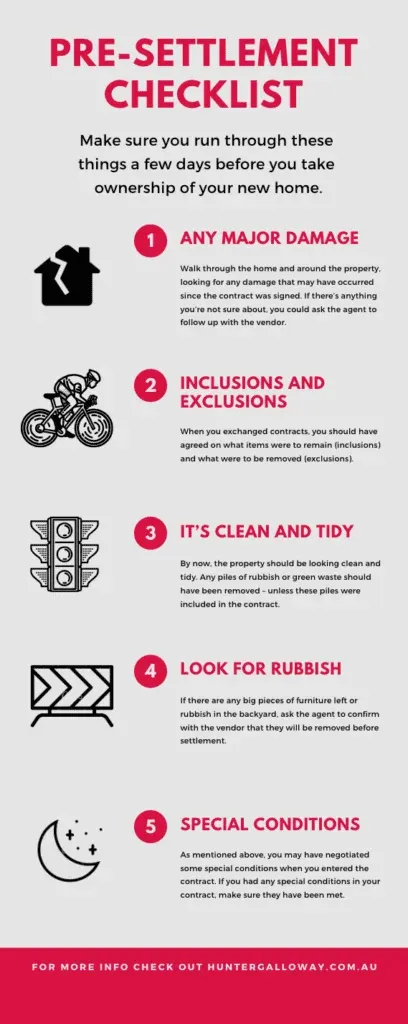
What to check at the final inspection
Take the contract and agreed repair list
- Check that the agreed inclusions are still there.
- Look for damage that wasn't present when you bought.
- Confirm agreed repairs and special conditions have been completed.
- Check that unwanted items have been removed where the contract requires it.
- Tell your solicitor about any problem immediately so they can advise before settlement.
If you're selling another property to fund this purchase, tell your broker and solicitor early. The sale proceeds and purchase funds need to be available in the right order. Our simultaneous settlement guide explains how the transactions can be coordinated and why a delay in one can affect the other.
Your making an offer checklist
Before you press send or sign
- The property still fits the important parts of my original buyer brief.
- I have inspected carefully and arranged the professional checks I need.
- I have reviewed tenancy or body corporate details where relevant.
- I have recent comparable sales and written my opening offer, the likely market range and my maximum price.
- I know how the seller will handle competing offers and which dates matter.
- My solicitor or conveyancer has reviewed the contract and special conditions.
- My broker has confirmed what is assessed and what remains outstanding.
- The finance and building and pest periods are realistic.
- The deposit, settlement date, buyer names and inclusions are correct.
- I can complete the purchase if the seller accepts.

Experience and sources
Sources and experience
This guide covers the questions we help buyers work through: what to offer, which conditions to include and how much time to allow for finance. The sources below explain the legal steps, including Queensland’s seller disclosure rules.
Jayden is a mortgage broker and co-owner of Hunter Galloway. This guide combines buyer questions from real property searches with current government guidance. See Jayden’s experience.
Official guidance used for this update
- Queensland Government: advice on buying a home
- Queensland Government: seller disclosure scheme
- Queensland Government: residential cooling off period
- NSW Government: buying residential property
- Consumer Affairs Victoria: buying by private sale
- Moneysmart: buying a house
- NSW Government: contracts and deposits
- Queensland Government: when to arrange home insurance
- South Australian Government: offers and cooling off
- WA Consumer Protection: sale by offer and acceptance
- Access Canberra: residential property buying guide
- Northern Territory Government: contract of sale
- Tasmanian Government: buying and selling property
General information only. Your rights depend on the state, sale method and contract. Get legal advice on your purchase and finance advice for your circumstances.
More help before you make an offer
Home loan pre-approval
Know what is assessed and what can still change.
Read guideHow to value a property
Use comparable sales instead of relying on the asking price.
Read guideBuying at auction
Complete your finance, legal and property checks before bidding.
Read guideNegotiating a house price
Handle agent calls and counteroffers without losing your limit.
Read guideBuilding and pest inspections
Understand the report and what to do when it finds a problem.
Read guideWhat happens after signing
Track finance, inspections, insurance and settlement.
Read guide
Straight answers
Making an offer on a house FAQs
What home buyers say about us
 Google
“Clear, incredibly responsive and accurate.”
- Google
“Preapprovals done quickly and efficiently.”
- Google
“Reassuring every step of the way.”
Get the finance side ready before the next offer
We’ll check your lender, any valuation needed, how much cash you need and a realistic finance deadline before you submit the offer.
or call 1300 088 065
Have the contract and proposed dates handy.
Client names and some amounts have been changed for privacy.