

You can get a 40 year home loan in Australia. Lenders including Great Southern Bank, Pepper Money and Granite offer them on eligible products. A lower monthly repayment can give you more room in the budget, but keeping the loan for the full 40 years costs much more in interest.
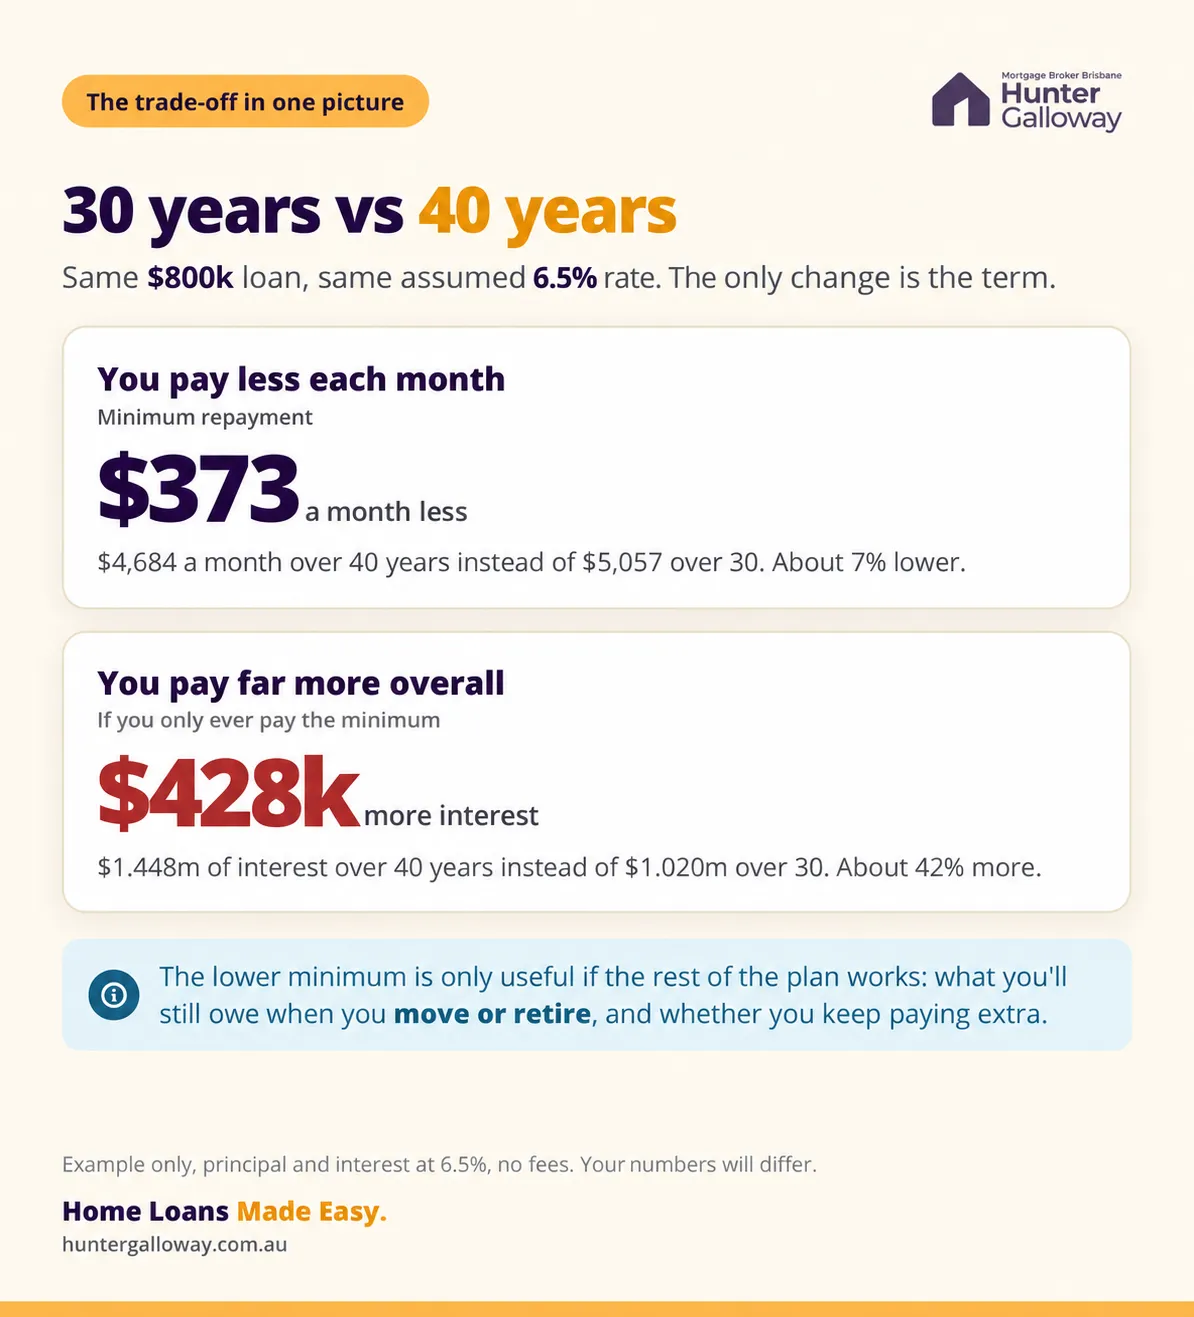
On an $800k loan at an assumed 6.5%, the minimum is about $4,684 a month over 40 years, compared with $5,057 over 30. That's roughly $373 less each month, but about $428k more interest if you only pay the minimum for the whole term.
I'd compare the payment you can manage now with what you'll still owe when you expect to move or retire. The lower minimum is useful only if the rest of that plan works too.
The short version
Lower repayments, more interest
On the same loan and rate, extending 30 years to 40 cuts the monthly repayment by about 7% in our example. Total interest rises by about 42%, and the balance falls more slowly.
Check borrowing power and extra repayments
A longer term doesn't automatically let you borrow more. Some lenders test your application over a shorter period. Extra repayments can shorten the loan, but check the product's rules and whether you can keep paying extra.
What do 25, 30, 35 and 40 year loans cost?
These examples use an $800k loan at an assumed 6.5% a year, monthly principal and interest repayments and no fees. The rate stays the same for the full term. This isolates the effect of the term; it isn't a lender quote.
$800k at 6.5%: monthly principal and interest repayments
Scroll to see more columns
| Loan term | Monthly repayment | Total repaid | Total interest |
|---|---|---|---|
| 25 years | $5,402 | $1.620m | $820k |
| 30 years | $5,057 | $1.820m | $1.020m |
| 35 years | $4,833 | $2.030m | $1.230m |
| 40 years | $4,684 | $2.248m | $1.448m |
Going from 25 to 30 years lowers the payment by about $345 a month. Adding another 10 years, from 30 to 40, reduces it by about $373. You get less repayment relief for each extra year, while interest keeps adding up.
Figures are rounded for display, and differences are calculated before rounding. Ask for quotes on the same loan amount and compare the actual rates and fees too.
How does a 40 year home loan work?
You have more time to repay the same debt. Each principal and interest payment covers interest and pays back some of what you borrowed. A longer term lowers the payment, so less comes off the balance, especially early on.
After 5 years on the $800k example, you'd still owe about $775k over a 40 year term, compared with $749k over 30 years. You've paid down around $25k instead of $51k.
Which lenders offer 40 year home loans?
The 9 lenders below publish terms of up to 40 years on eligible products. I checked their public information on 29 October 2026. The conditions differ, so a lender offering 40 years doesn't mean every applicant or loan qualifies.
LVR means the loan as a percentage of the property's accepted value. A maximum LVR doesn't cover all your buying costs, and mortgage insurance or other fees can apply.
Lenders with longer terms: public information checked 29 October 2026
Scroll to see more columns
| Lender | Term | What matters for your application |
|---|---|---|
| Great Southern Bank | Up to 40 years | First home buyers buying or building a home to live in. All applicants must be aged 18 to 40, with at least one first home buyer. Maximum 90% LVR including fees. Government scheme and guarantor loans are excluded. |
| RACQ Bank | Up to 40 years | Advertises extended terms for first home buyers. Confirm the term and eligibility for the particular loan before relying on it. |
| Credit Union SA | 31 to 40 years | XL Home Loan for a home you live in in South Australia. Purchase or refinance, with up to 97% LVR including LMI for eligible purchases. Refinances are generally capped at 80%, except land refinanced for construction. Cannot be combined with the government home guarantee scheme. |
| Bank of us | Up to 40 years | For Tasmanian owner occupiers who don't meet its 30 year affordability test. Purchases and construction only. Refinancing, debt consolidation and equity release are excluded. |
| Pepper Money | Up to 40 years | Advertises up to 40 years for eligible purchases and refinances. Its construction loans run from 10 to 30 years. Check the term for your income documents and repayment type. |
| Bluestone | 10 to 40 years | Its published policy allows up to 40 years, with some products capped at 30. It calculates borrowing capacity over 30 years, so the longer repayment term does not itself increase the amount it will lend. |
| Mortgage Street Optimax | Up to 40 years | The public Optimax page lists a 40 year maximum. Applications go through brokers. Confirm the particular product and price. |
| Granite | Up to 40 years | The variable 40-Year Extended Home Loan covers eligible home buyers, investors, construction and refinances. Up to 95% LVR includes risk fees. It tests repayments over up to 35 years, not the full 40. |
| AMP Equity Flex | 31 to 40 years | Investment purpose and investment property security only, up to 80% LVR. At least one split must start with 6 to 10 years interest only, followed by principal and interest. No reassessment during that interest only period. |
- Term
- Up to 40 years
- What matters for your application
- First home buyers buying or building a home to live in. All applicants must be aged 18 to 40, with at least one first home buyer. Maximum 90% LVR including fees. Government scheme and guarantor loans are excluded.
- Term
- Up to 40 years
- What matters for your application
- Advertises extended terms for first home buyers. Confirm the term and eligibility for the particular loan before relying on it.
- Term
- 31 to 40 years
- What matters for your application
- XL Home Loan for a home you live in in South Australia. Purchase or refinance, with up to 97% LVR including LMI for eligible purchases. Refinances are generally capped at 80%, except land refinanced for construction. Cannot be combined with the government home guarantee scheme.
- Term
- Up to 40 years
- What matters for your application
- For Tasmanian owner occupiers who don't meet its 30 year affordability test. Purchases and construction only. Refinancing, debt consolidation and equity release are excluded.
- Term
- Up to 40 years
- What matters for your application
- Advertises up to 40 years for eligible purchases and refinances. Its construction loans run from 10 to 30 years. Check the term for your income documents and repayment type.
- Term
- 10 to 40 years
- What matters for your application
- Its published policy allows up to 40 years, with some products capped at 30. It calculates borrowing capacity over 30 years, so the longer repayment term does not itself increase the amount it will lend.
- Term
- Up to 40 years
- What matters for your application
- The public Optimax page lists a 40 year maximum. Applications go through brokers. Confirm the particular product and price.
- Term
- Up to 40 years
- What matters for your application
- The variable 40-Year Extended Home Loan covers eligible home buyers, investors, construction and refinances. Up to 95% LVR includes risk fees. It tests repayments over up to 35 years, not the full 40.
- Term
- 31 to 40 years
- What matters for your application
- Investment purpose and investment property security only, up to 80% LVR. At least one split must start with 6 to 10 years interest only, followed by principal and interest. No reassessment during that interest only period.
Not every broker can arrange every lender listed here. We check which options we can arrange and explain where you would need to go directly.
Compare the rate, fees and total cost on your actual quote. A comparison rate uses a standard example loan, so it may not reflect your loan amount or term.
Who can use Granite’s extended term?
Granite offers the full 40 year term to eligible owner occupiers up to age 45, with shorter terms through age 50. Its public page says those age restrictions don't apply to investors. Retirement and income checks still matter.
Company and trust borrowers are capped at 80% LVR. The extended product has offset, redraw and unlimited extra repayments. Interest only is limited to 5 years for owner occupiers or 10 for investors. Its separate Professional Lender Paid LMI product has a maximum 30 year term. Don't combine that offer with the 40 year product when planning your deposit.
What are the pros and cons?
Benefits and costs of a longer loan term
Scroll to see more columns
| Possible benefit | What to weigh against it |
|---|---|
| A lower required monthly payment can leave more room for bills. | More interest over the full term. In our example, 40 years costs about $428k more than 30. |
| Some buyers can qualify sooner if the lender assesses the longer term. | You could take on a larger debt than you can comfortably manage if rates or expenses rise. |
| Extra repayments can shorten the loan while you retain a lower minimum. | That depends on the loan rules and whether you actually keep paying extra. |
| More time to repay the balance. | Debt falls more slowly and can extend into retirement. Some products also have higher rates or fees. |
- What to weigh against it
- More interest over the full term. In our example, 40 years costs about $428k more than 30.
- What to weigh against it
- You could take on a larger debt than you can comfortably manage if rates or expenses rise.
- What to weigh against it
- That depends on the loan rules and whether you actually keep paying extra.
- What to weigh against it
- Debt falls more slowly and can extend into retirement. Some products also have higher rates or fees.
What would you still owe after 5, 10 or 20 years?
On the same $800k loan at 6.5%, paying only the minimum leaves the balances below. These figures exclude selling costs.
Remaining debt on an $800k loan at 6.5%
Scroll to see more columns
| Time elapsed | 30 year term | 40 year term | Extra debt with 40 years |
|---|---|---|---|
| After 5 years | $748,888 | $775,241 | $26,354 |
| After 10 years | $678,209 | $741,005 | $62,796 |
| After 20 years | $445,322 | $628,195 | $182,873 |
If you sell after 10 years, the 40 year loan leaves about $63k less from the sale after repaying the lender, assuming the same sale price and costs. Property growth can add to your equity, but it doesn't pay down either loan. If you expect to upgrade, work out the remaining debt and selling costs before counting on your next deposit.
Will a 40 year term let you borrow more?
It can, if the lender uses the longer term when testing your repayments. If it assesses the loan over 30 years anyway, the lower actual payment doesn't automatically increase your borrowing power.
Granite assesses its extended product over up to 35 years. Bluestone uses 30. AMP uses the remaining principal and interest period, capped at 30 years. Bank of us offers its extended term only where the applicant doesn't meet its 30 year affordability test.
I'd ask two questions: what will you actually pay each month, and what repayment will the lender use to test your application? Your income, living expenses and other debts still decide whether it works.
Compare my loan term options
We'll show you the repayments, fees and total interest for loan terms that fit your budget and plans.
or call 1300 088 065
We’ll explain the costs before you apply.
How will you repay the loan in retirement?
Start a 40 year loan at 35 and the final scheduled repayment falls around age 75. If the loan runs beyond when you expect to stop working, the lender will want to know how you'll clear what's left.
For an owner-occupied loan, Bluestone requires an exit strategy when the term ends after the earlier of your declared retirement age or age 70. It requires that strategy to be verified if you expect to retire within the next 10 years. Applicants aged 70 or older using an owner-occupied property as security also need independent legal advice.
That plan might involve savings, super or downsizing, if the lender accepts it and the figures work. I wouldn't base it on an inheritance or hoped-for price growth. Tell us when you expect to retire and what you could use to repay the debt, so we can compare terms that fit.
Can you take 40 years and pay it off like a 30 year loan?
You can if the product allows the extra repayments and you keep making them. A lower minimum can give you flexibility, but it doesn't produce the shorter loan's savings by itself.
On the $800k example, paying about $5,057 a month instead of $4,684 clears the loan in around 30 years and saves roughly $428k in interest. That comparison assumes the same 6.5% rate, no fees, no redraw of the extra payments and no charge or cap on those payments. Different rates or fees change the result.
Fixed rate loans often limit extra repayments. Offset and redraw rules differ too. Our extra repayment guide explains the options, and the calculator below lets you test a regular top-up.
What difference could an extra repayment make?
What should you compare before choosing 40 years?
I'd start with a cheaper purchase and a loan with a lower rate or fewer fees. Either could make the budget work without adding 10 years. If you're refinancing, compare the new loan with the years you have left, as well as its repayment. Resetting 22 years to 40 is a big extension.
If the deposit is the obstacle, compare the 5% Deposit Scheme and any LMI waiver you qualify for. These address the upfront cost, not whether you can afford the debt. They also have their own term rules, so don't assume you can combine them with a 40 year loan.
A guarantor loan can help with the deposit or security, but it puts the guarantor's property at risk. Compare that obligation with buying for less or saving longer before asking someone to guarantee the loan.
Who might consider a 40 year term, and who should think twice?
It can be worth comparing if you qualify for the product, can manage its payments and want a lower minimum while making extra repayments when your budget allows. Buyers early in their careers should still base the decision on income they can show now, rather than a pay rise they hope to receive.
I'd be more cautious if you're within 15 to 20 years of retirement, stretching to a more expensive home or expecting to pay only the minimum. If the budget works only over 40 years, test what happens when rates or living costs rise before you commit.
Compare your loan term options
Send us your income documents, savings, existing debts and a budget that includes annual bills. If you're refinancing, include a recent statement showing the balance, rate and remaining term.
We'll compare the minimum repayments, total costs and the balance you'd still owe when you plan to move or retire. Then you can decide whether the lower payment now is worth keeping the debt for longer.
Common questions
Experience and sources
Sources and further reading
Reviewed 11 September 2026 by Nathan Vecchio.
The repayment examples were recomputed on 29 October 2026 using the assumptions beside each table. Lender information was checked against the public sources below on the same date. Rates, fees and eligibility can change.
Sources
- Great Southern Bank: extended terms
- Great Southern Bank: full eligibility and exclusions
- RACQ Bank: home loans
- Credit Union SA: XL Home Loan
- Bank of us: extended loan term
- Pepper Money: home loan terms
- Bluestone: public credit policy, updated 7 October 2026
- Mortgage Street: Optimax
- Granite: 40-Year Extended Home Loan
- Granite: separate Lender Paid LMI product
- AMP: Equity Flex
General information only. Your loan options depend on your circumstances and the lender’s assessment. Get legal or tax advice where relevant to your decision.