


Ask what the lender checked before issuing your pre-approval. I want your income, debts and spending reviewed before you make an offer, with the remaining property and valuation conditions clear.
Start with the money you have for the purchase, then check what the lender has verified. Our mortgage brokers in Brisbane can check the finance position before you bid at auction. Your solicitor handles the contract advice.
What is pre-approval?
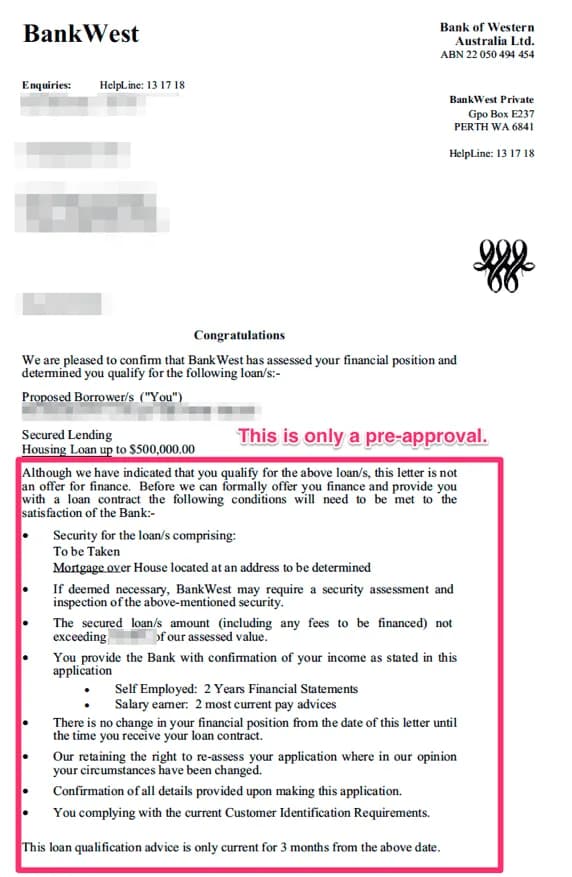
Pre-approval is a conditional indication of what a lender may lend. You can apply before finding a property.
Lenders use names such as conditional approval, indicative approval, approval in principle and Home Seeker. Ask what your lender has checked, whatever the letter is called.
Apply before you start seriously looking so you have time to resolve problems.
Has your pre-approval been assessed?
Ask who reviewed your documents, what they checked and what remains outstanding.
A human review is not a guarantee. Get the loan amount, expiry date, assumptions and outstanding conditions in writing.
Online estimate
You enter figures and receive a borrowing range. No lender has made a credit decision.
Automated pre-approval
The system accepted the supplied information. Documents, income types, debts or policy issues may still need checking.
Credit-assessed pre-approval
An assessor has checked your documents against lender rules. It is a stronger starting point, but the property, valuation and other conditions may remain.
What should you check in your pre-approval letter?
| Question | What to ask | Why it matters |
|---|---|---|
| Income | Which pay or business income was used? | Later checks may lower it. |
| Salary packaging | Were packaging and lease deductions included? | Missed deductions can change the result. |
| Debts | Were cards, car loans, HELP and BNPL included? | Extra commitments can reduce borrowing. |
| Deposit | Does your cash cover the price and costs? | Allow for your deposit, costs and cash kept aside. |
| Credit review | Were your credit report and debts checked? | An online response may leave checks unfinished. |
| Scheme eligibility | Are your eligibility and any scheme place confirmed? | Outstanding scheme approval is still a condition. |
| Other conditions | What must be supplied, repaid, closed or confirmed? | Any outstanding condition can delay approval. |
The evidence behind the loan amount
Income
- What to ask
- Which pay or business income was used?
- Why it matters
- Later checks may lower it.
Salary packaging
- What to ask
- Were packaging and lease deductions included?
- Why it matters
- Missed deductions can change the result.
Debts
- What to ask
- Were cards, car loans, HELP and BNPL included?
- Why it matters
- Extra commitments can reduce borrowing.
Deposit
- What to ask
- Does your cash cover the price and costs?
- Why it matters
- Allow for your deposit, costs and cash kept aside.
Credit review
- What to ask
- Were your credit report and debts checked?
- Why it matters
- An online response may leave checks unfinished.
Scheme eligibility
- What to ask
- Are your eligibility and any scheme place confirmed?
- Why it matters
- Outstanding scheme approval is still a condition.
Other conditions
- What to ask
- What must be supplied, repaid, closed or confirmed?
- Why it matters
- Any outstanding condition can delay approval.
Check every condition in the approval letter
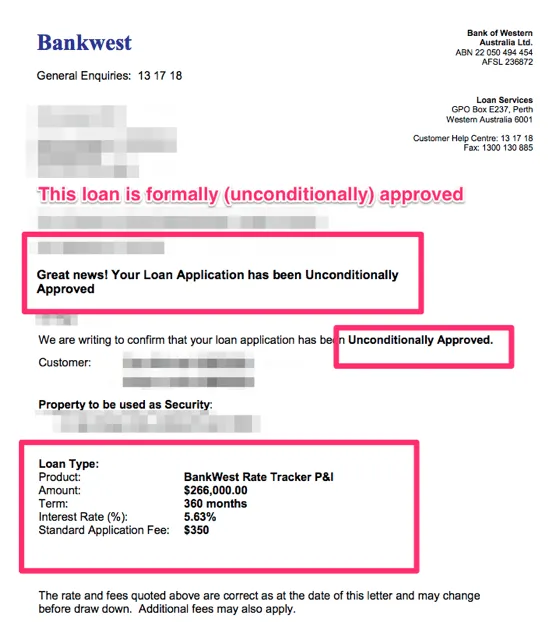
A letter is not unconditional if the lender still needs to confirm your 5% Deposit Scheme eligibility, return-to-work income, debt closure, updated documents or anything else. Read every condition before treating the approval as final.
Check before closing a credit card, changing jobs or moving savings for the application. Ask what the change would achieve and when it needs to happen.
Your finances and documents
- Confirm that the details in your application are still correct.
- Supply any outstanding documents.
- Tell the lender if your income, expenses or other finances change.
- Meet the expiry date and document deadlines. Ask what an extension needs.
When does the lender give final approval?
Final approval comes after the lender completes its required checks. Read the formal offer for any conditions still needed before settlement funds are released.
Read more: the first home buyer guide
The property still needs its own approval
The lender also needs to accept the property you choose. Before signing, send your broker or lender the address, contract and any unusual property details. If the lender's valuation is below the price, read our guide to challenging a bank valuation. For a unit, see our apartment mortgage guide.
The lender uses its valuation to set the accepted property value for the loan.
A lender may accept your income and deposit, then reject a unit because it already has too many loans in that building. Some lenders also restrict high-density towers and homes under 50sqm. Send your broker the details early. A pre-approval doesn't mean every property is acceptable.
Check the lender's property rules early if the home:
- is a compact apartment. Check the internal floor area against the chosen lender's rules.
- has a large land area or a non-standard title. Ask about the lender's size and title rules.
- is in a rural location.
- comes with developer incentives, such as furniture packages or a rental guarantee.
- needs major repairs or structural work.
If your loan requires lenders mortgage insurance (LMI), check whether any insurer conditions remain. A deposit below 20% does not always mean LMI applies: waivers and government guarantee schemes can change the position.
The lender and mortgage insurer can have different property rules. A home near high-voltage power lines is one example. If insurer approval is required and refused, that can stop the loan.
What can change the answer
- Starting a new job or changing employment type
- Lower overtime, bonus, commission or casual earnings
- A new credit card, car loan or other commitment
- Using part of the deposit
- A new dependant or material change in household expenses
- The approval expiring
- Changes to lender policy, interest rates or assessment settings
- A property or valuation the lender will not accept
A lender can still decline the final loan if the property or application doesn't meet its requirements. Here's what to do if your loan is declined after pre-approval.
The RBA raised the cash rate on 29 September 2026. A rise while you search can reduce how much you can borrow, so recheck your figure before you make an offer.
From 1 February 2026, APRA limits how much new bank lending can go to borrowers whose total debt is 6 times their income or more. The limit is 20%, measured separately for home buyers and investors, with specified exemptions.
This limits each bank's lending as a whole. It doesn't cap every applicant at 6 times income, and a pre-approval doesn't reserve a place for you.
Will the lender keep the same assessment settings?
Ask whether the lender holds any assessment settings during pre-approval, and for how long. Rates, policy and the borrowing limit can still change.
How long does pre-approval last, and can you extend it?
Many pre-approvals last around 3 months and some up to 6 months, but the expiry date on your letter is the one that counts. Ask about renewal before it expires. The lender may refresh it or ask for updated payslips and statements.
A refresh may need payslips, account statements, a credit check or reassessment. Keeping the same job does not guarantee the same loan amount.
Have a HELP debt and applying through CommBank?
Applying through the 5% Deposit Scheme with CommBank? Have your HELP debt included in the borrowing calculation before setting your price limit. For new applications from 25 September 2026, the scheme does not allow the lower assessment buffer for HELP debt expected to clear in more than 1 year and within 5 years. The separate option for debt expected to clear within 12 months remains available to eligible borrowers.
An application or Home Seeker pre-approval already in progress may retain its earlier treatment if it meets the rules for acceptable changes. We will check your application date and any changes before you rely on the amount.
See our HECS guide for how lenders assess the debt.
Client story
James's budget changed while he waited
James first spoke with our team in late 2025 and chose to wait before buying. He hoped prices would ease or interest rates would fall.
James's earlier assessment put his buying budget at $1m. That was the position at the time; later rate or policy changes could still affect it.
When James returned in April 2026, his borrowing capacity was more than $120k lower. Waiting wasn't the cause by itself, and an earlier pre-approval wouldn't necessarily have prevented the drop.
With the lower borrowing limit, James couldn't afford the suburbs he'd first considered. He needed a larger deposit or a smaller property further out.
Recheck your budget while you search and before making an offer. An old borrowing figure may no longer fit.
Read more: Mortgage broker Brisbane
What documents will you need?
Proof of identity
- A current Australian passport or driver's licence may be accepted as primary ID.
- Other accepted documents may include a Medicare card, birth certificate or ATO assessment notice less than 12 months old. Check the combination your lender needs.
Income evidence
For employed income, start with 2 recent payslips and your latest PAYG income statement from myGov. An employer letter may help.
If you are self-employed, many lenders ask for 2 years of personal and business tax returns and notices of assessment. Some may accept other evidence, depending on your trading history and the lender's rules.
Savings and expenses
- Ask how many months of transaction, savings and loan statements the lender needs.
- If genuine savings are required, check how much of the deposit you need to have held or saved and for how long.
- List your living expenses, including groceries, transport, insurance and subscriptions. The lender may use software to check these against your statements.
Existing debts
- Credit cards: include the full limit, even if you owe nothing.
- Personal and car loans: provide the balance and repayment schedule.
- HELP debt: provide a current ATO balance. Repayments can affect your take-home pay.
- Buy now, pay later: disclose accounts such as Afterpay and Zip.
For a novated lease, have the payslip deductions and lease breakdown checked before relying on your pre-approval amount.
What happens during pre-approval?
Your broker compares suitable lenders before submitting the application. The lender then completes its own assessment.
At Hunter Galloway, our brokers and credit analysts check your documents against the lender's requirements.
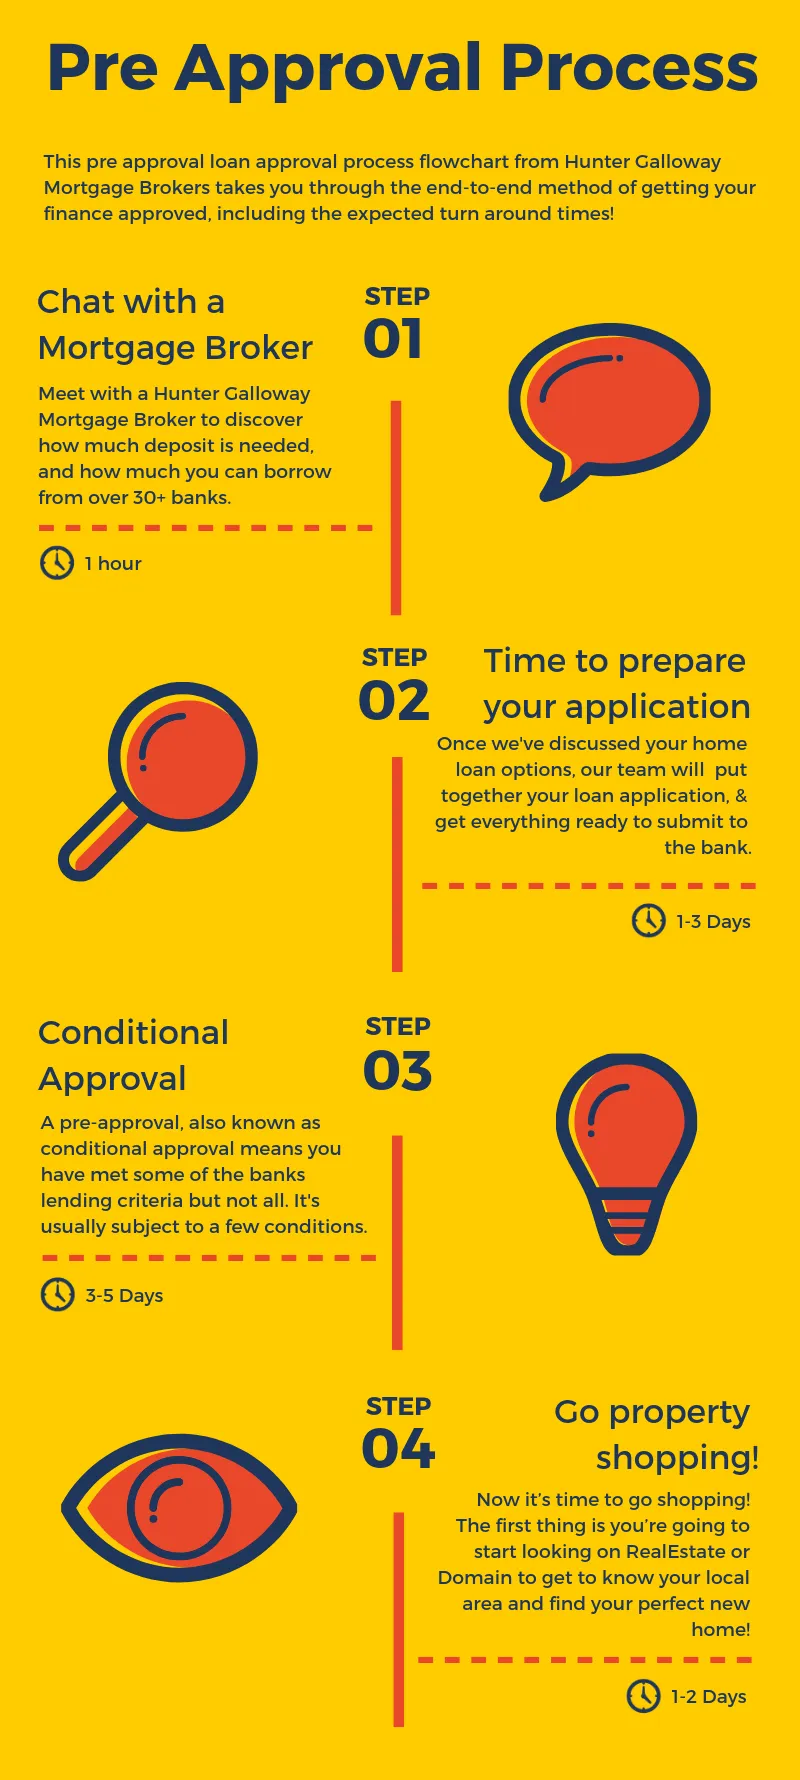
- Talk through your plansStart with a free assessment of what you want to buy, your finances and the next steps.
- Gather the documentsOur credit analysts help collect employment, asset and debt records through our secure online portal.
- Check the evidenceWe check credit-report errors, job type and work history against lender rules, then add savings, available grants and buying costs.
- Compare suitable lendersWe compare income, deposit, documents and total debts before recommending an application.
- Submit and explain the conditionsWe submit to your chosen lender and handle questions. The process usually takes 1 to 3 weeks, depending on the lender and application. We explain the conditions and what to check while shopping.
Read more: Home Loan Process: A Step-by-Step Guide
Why get pre-approval before buying?
Pre-approval helps set your search budget and uncover problems before you commit.
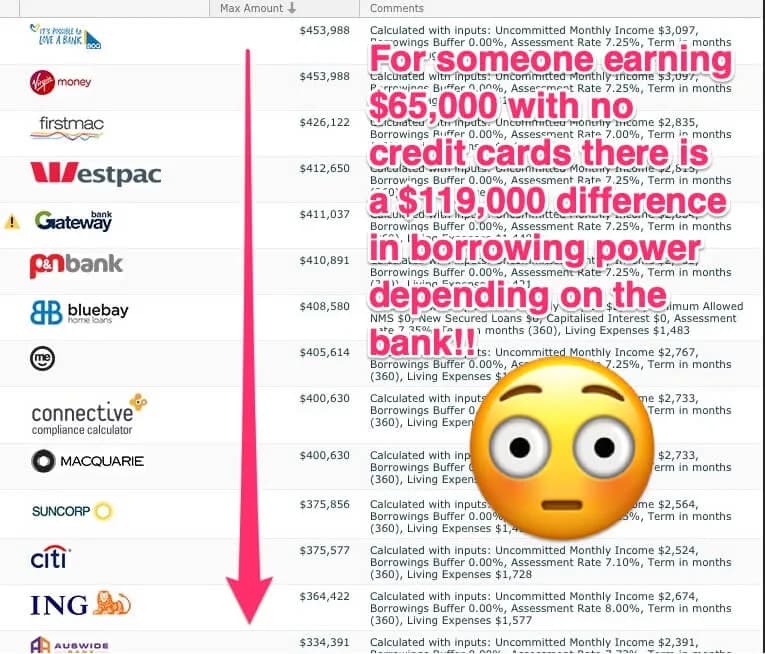
Add your savings to the loan amount, then take off buying costs and the cash you want to keep aside. What's left is your purchase budget. For example, an $800k loan and $200k in savings give you $1m. If buying costs are $40k, you have about $960k before any cash you keep aside. Use your own costs when you run the numbers.
You do not have to borrow the maximum. Choose repayments you can manage, then set your purchase limit.
In Queensland, an auction purchase has no cooling-off period. Check the deposit and settlement terms before bidding.
On a $1m property, a 5% deposit is $50k and 10% is $100k. If you cannot settle, you may lose more than the deposit. Ask your solicitor about the risk before buying unconditionally.
Client story
A $15,000 default uncovered before bidding
Pre-approval helps uncover financial red flags you might not notice. We recently helped a client who was a victim of identity fraud. He had a $15,000 default he didn't know about. Because we caught it during pre-approval, we cleared the fraud before he started bidding.
How much can you spend on the property?
Your pre-approval covers the loan amount. You'll also need cash for the costs of buying a home, as well as your deposit.
| Cost | What to allow for | What it covers |
|---|---|---|
| Transfer duty | Your state, price and eligibility | Property tax; concessions may apply |
| Conveyancing | Quote for your purchase | Contract advice and transfer work |
| Building and pest inspections | Quotes for the inspections needed | Checks for property issues |
| Government and title fees | Current state or territory fees | Registration and title charges |
| Total cash needed | Deposit, buying costs and buffer | Keep available through settlement |
Work out your total buying budget
Transfer duty
- What to allow for
- Your state, price and eligibility
- What it covers
- Property tax; concessions may apply
Conveyancing
- What to allow for
- Quote for your purchase
- What it covers
- Contract advice and transfer work
Building and pest inspections
- What to allow for
- Quotes for the inspections needed
- What it covers
- Checks for property issues
Government and title fees
- What to allow for
- Current state or territory fees
- What it covers
- Registration and title charges
Total cash needed
- What to allow for
- Deposit, buying costs and buffer
- What it covers
- Keep available through settlement
Read more: first-home buyer concessions
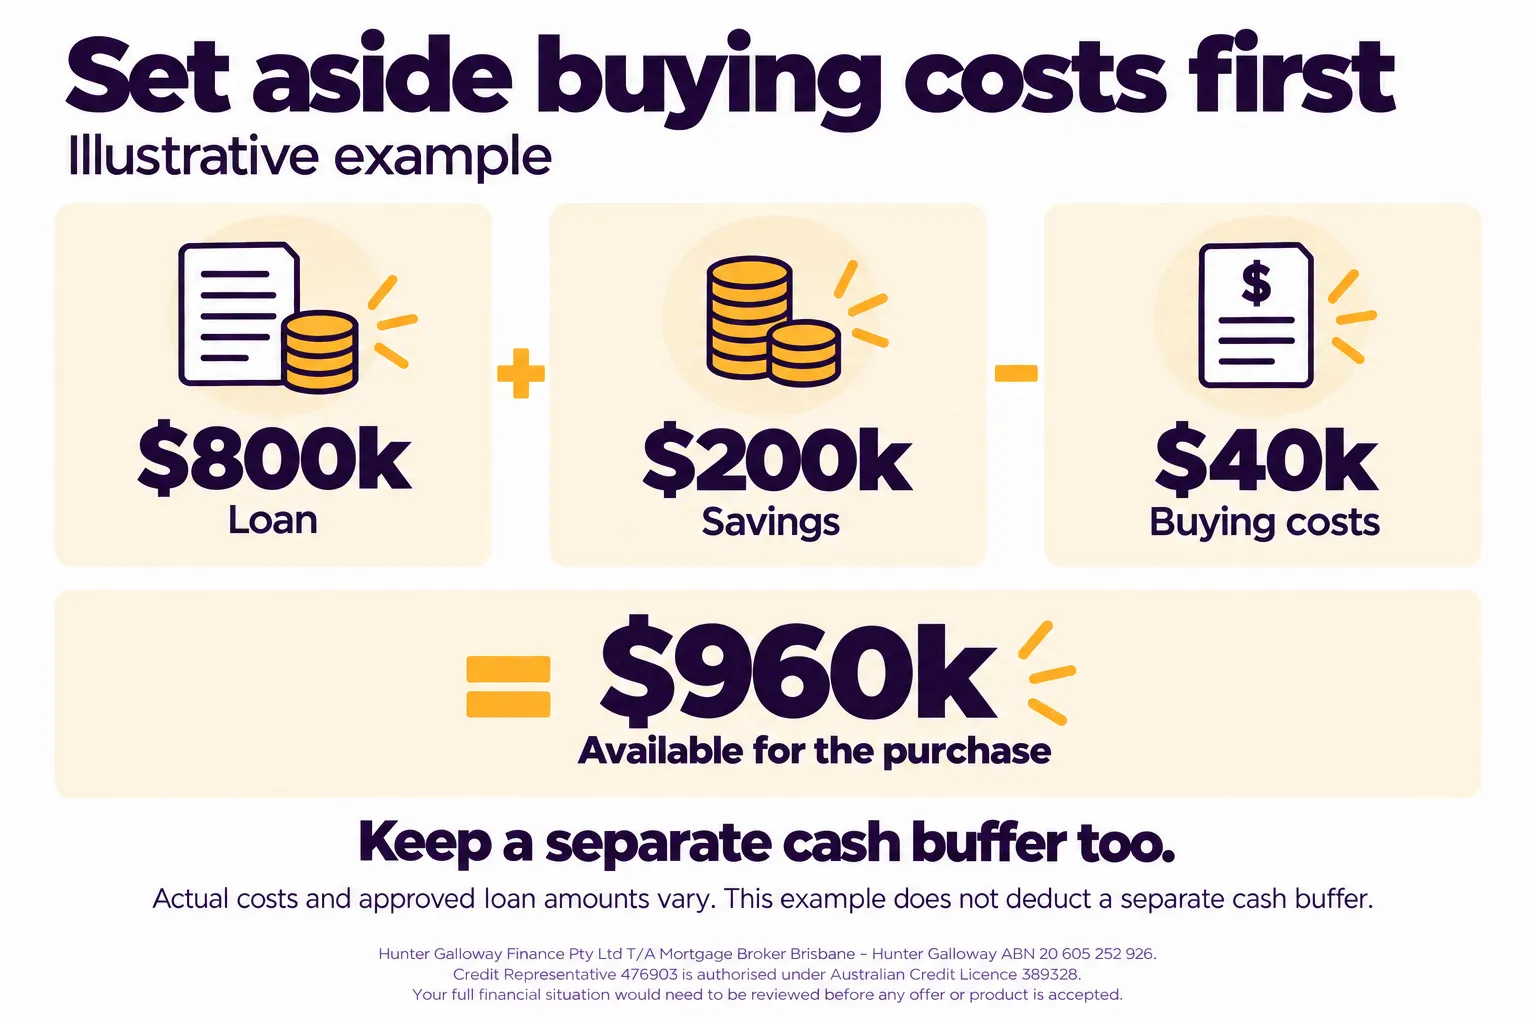
Use current quotes and allow for an unexpected legal or inspection cost, plus a separate household cash buffer.
Does pre-approval affect your credit score?
It depends on the check. Looking at your own credit report is different from making a formal loan application.
- Checking your own credit report doesn't affect your score. Some preliminary lender checks may also avoid an application enquiry; ask before proceeding.
- A formal credit application may leave an enquiry. Its effect depends on the rest of your credit history and the lender's assessment.
How long does an enquiry stay on your report?
Credit application enquiries can stay on an Australian credit report for 5 years.
Several applications close together can prompt questions about declines or your need for credit. Compare suitable lenders before applying.
Can pre-approval help you negotiate?
Sellers weigh your conditions as well as your price, so a short or no finance clause can make an offer stronger. Without a finance condition, you may still have to settle if the loan is declined, and a valuation condition may not cover an income, credit or insurer decline. Before you shorten or drop a finance clause, ask your broker whether the lender can meet the deadline (valuation, documents, LMI approval) and ask your solicitor what the contract protects and how to give notice.
Client story
How Dylan and Kennedy changed their offer
Dylan and Kennedy spent 8 months looking for their first home. They'd been making offers with a 21 day finance clause and no pre-approval.
They missed out on 3 properties. For one, the seller accepted a lower offer from a buyer who already had pre-approval.
Sellers had to weigh the time needed for finance alongside their offer price. A shorter finance period might help, but it needed to be a deadline the lender could meet.
We helped them get a fully assessed pre-approval and explained how it could support their next offer.
On the next home, they chose to remove the finance condition and keep the building and pest condition. That meant accepting the risk that they might still have to settle if finance fell through.
The seller accepted their offer that day. It worked for them, but going unconditional is a real risk, so we'd check your finance position and your solicitor would explain the contract first.
What should you do once pre-approved?
Set up your property search
Start your search on RealEstate.com.au, Domain, and local agent websites. Try a few price ranges when setting your search filters.
- For a $1m target, you could search from $800k to $1.1m to see how agents are pricing nearby homes. Keep your own spending limit separate.
- Search more than one price bracket because an advertised range can be part of the agent's marketing.
- Set up alerts so you can see new listings as they appear.
Check recent comparable sales before offering. Property reports and sales-history tools can help.
We can provide available property reports to clients. They support your research, not a guaranteed bank valuation.
Read more: Property market research tips
At Hunter Galloway, we help you understand the finance conditions and timing. Your solicitor or conveyancer should advise on the contract protections before you sign.
Pre-approval questions
More help with buying a home
- First home buyer guide
- The home loan process, step by step
- Common first home buyer mistakes
- Negotiating a house price
- Making an offer below the asking price
- Lenders mortgage insurance explained
- Grants for first home buyers
Our first home buyer loan guide explains other deposit options. You can contact us to have your pre-approval letter checked.
Check what your pre-approval covers
Send me the approval letter, the figures used and any property you are considering. I will show you what has been assessed, what is still outstanding and what to check before you commit.
or call 1300 088 065
Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328 held by Connective Credit Services Pty Ltd. General information only. This is not legal advice, a credit assessment or a promise of approval.
Experience and sources
About this guide
Reviewed 22 September 2026 by Nathan Vecchio.
Pre-approval remains subject to the lender's checks, your circumstances and the property you choose.
Joshua Vecchio is a director and mortgage broker at Hunter Galloway. Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328.
Sources
- CommBank Home Seeker loans: conditional approval and reassessment
- ASIC Moneysmart: buying a house and loan approval
- Australian Government 5% Deposit Scheme: first home buyers
- APRA: debt-to-income lending limits
- Queensland Government: cooling-off periods and auctions
- Moneysmart: credit scores and credit reports
- CommBank public reporting: HELP debt assessment options (page 75)
General information only, not legal advice, a credit assessment or a promise of approval. Lender policies can change. Pre-approval remains subject to its conditions and final assessment.
Client examples are based on real situations. Names and identifying details have been changed.