


Are power lines or easements an automatic decline?
There is no single rule. One lender may decline the property, another may limit the loan to 80%, and another may consider it after a closer look. Several policies use 50m, but the starting point and type of line matter. An easement needs a separate title and use check.
A property limit can create another $93k of cash
Say you are buying for $620k and expected to borrow 95%, or $589k. If the property is accepted only at 80%, the loan falls to $496k.
Same $620k property, different lender limit
- $589k
Loan expected at 95%
Cash towards the price: $31k.
- $496k
Loan limited to 80%
Cash towards the price: $124k.
- $93k
Extra cash before costs
Same $620k property.
Example only. The accepted value, buying costs, mortgage insurance and full application can change the amount.
Identify the line or substation first
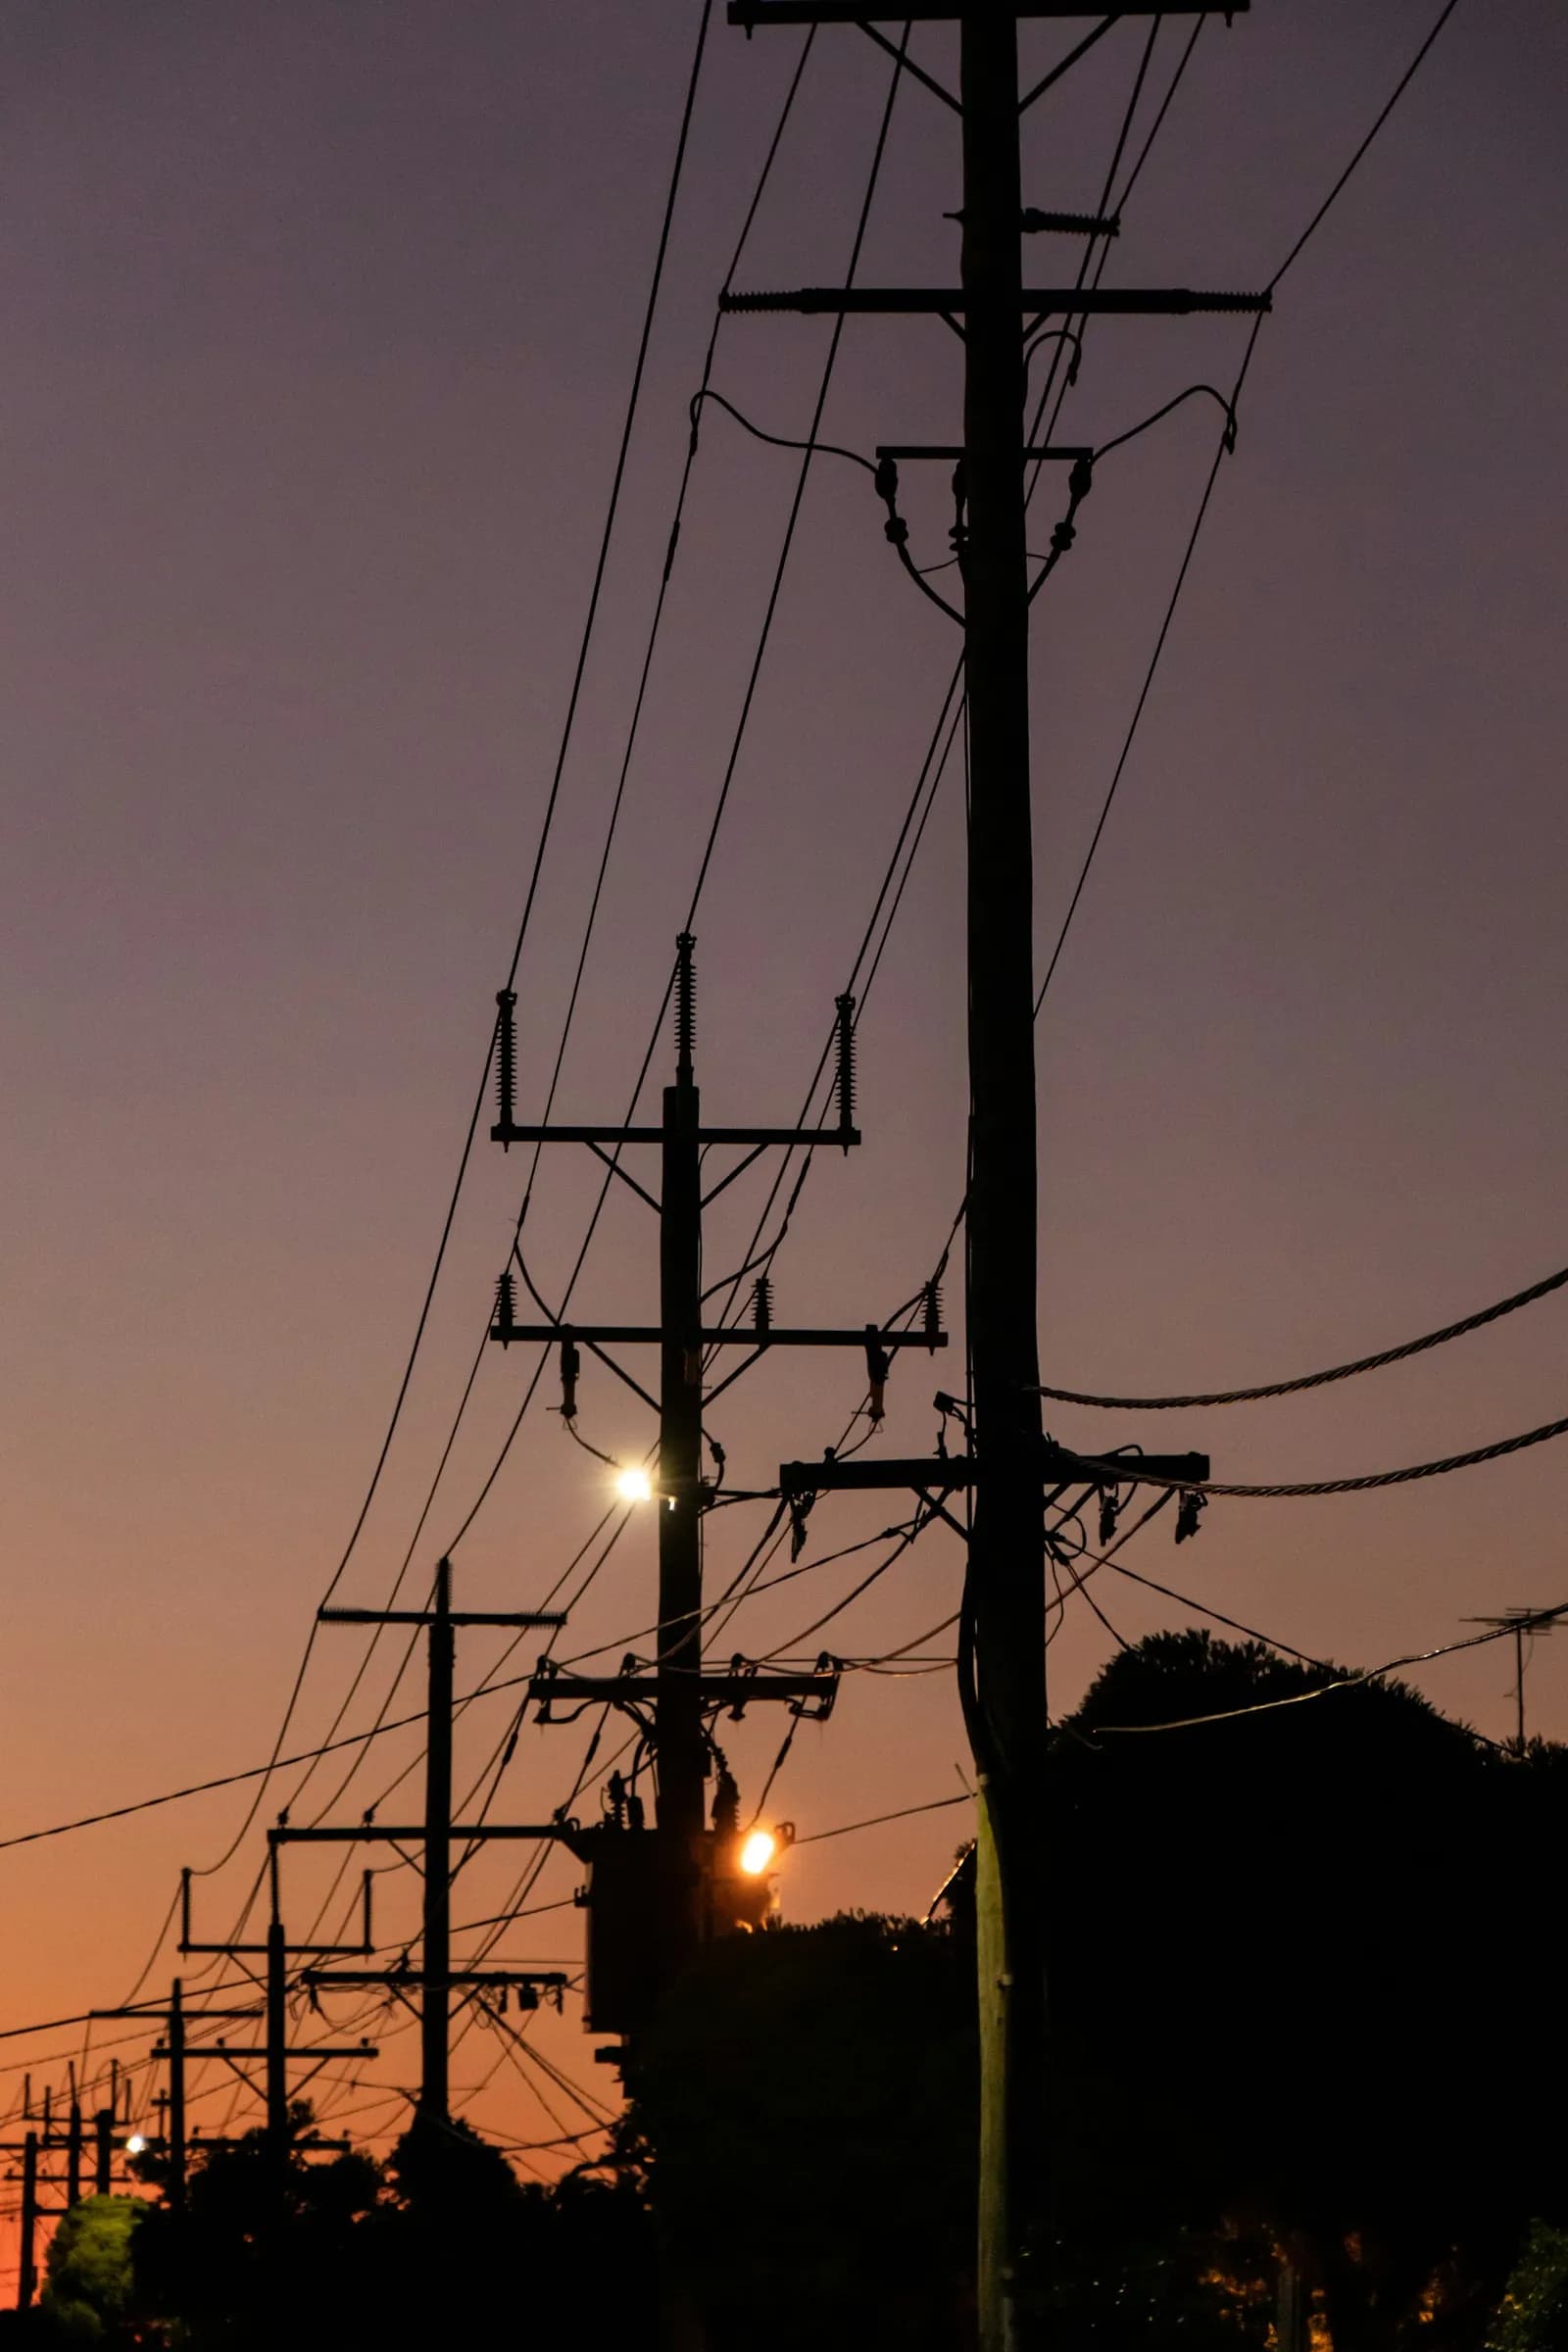
A high-voltage transmission line, an ordinary street distribution line and a substation are different features. Ask the network operator to confirm what is there; do not guess the voltage or lender category from a photograph. Send the map or written details with the title and distance measurement.
How is the distance measured?
Most lenders in this comparison that publish a fixed 50m rule start the measurement at the property or security boundary, not at the house. People First Bank is different because it starts at the residential building. On a larger block, the same power line could fall inside a boundary test and outside a building test.
Measure from the boundary
Westpac, St George, CBA, AMP, ME Bank, Macquarie and Firstmac start the rule at the boundary of the property being used as security.
Measure from the home
People First Bank starts at the home itself rather than the property boundary.
Confirm a different or unclear test
NAB relies on the valuer rather than a published distance. Resimac uses an affected-area exclusion without stating a number. Bankwest says within 50m but does not define where the measurement starts, so I check that point before relying on it.
This is why an agent's estimate or a measurement from the house is not enough. The measurement has to use the same starting point as the lender rule.
I compared 11 lenders for this guide. A 50m result can leave an option at 80%, trigger a manual review or rule the property out.
| Where lenders land | What that can mean for you | What I check |
|---|---|---|
| An option may remain at 80% Westpac , St George , CBA , ME Bank and People First Bank | These published positions can leave an option at 80% in some cases. CBA's 50m restriction applies to insured or lender-paid low deposit lending rather than every application. | I check the measurement point, the proposed loan percentage and whether mortgage insurance or lender-paid low deposit lending is involved. |
| No separate referral for some non-insured lending NAB | NAB's published non-insured framework lists transmission lines and busy roads as features that do not require a separate referral. Insured lending can still be referred through the valuer risk assessment. | I check whether mortgage insurance is involved and make sure the valuation has identified the feature correctly. |
| The property goes to manual review Macquarie and Bankwest | A result within 50m triggers a credit review rather than one automatic outcome. | I would give the assessor the exact address, a reliable boundary measurement and any useful valuation comments before relying on the loan. |
| No standard option where the rule applies AMP , Firstmac and Resimac | AMP and Firstmac use a 50m boundary test. Resimac publishes no distance and instead excludes an area affected by high tension powerlines. | I would establish whether the property is inside a measured boundary rule or an affected-area rule before comparing another lender. |
Lender and property checks
An option may remain at 80% Westpac , St George , CBA , ME Bank and People First Bank
- What that can mean for you
- These published positions can leave an option at 80% in some cases. CBA's 50m restriction applies to insured or lender-paid low deposit lending rather than every application.
- What I check
- I check the measurement point, the proposed loan percentage and whether mortgage insurance or lender-paid low deposit lending is involved.
- What that can mean for you
- NAB's published non-insured framework lists transmission lines and busy roads as features that do not require a separate referral. Insured lending can still be referred through the valuer risk assessment.
- What I check
- I check whether mortgage insurance is involved and make sure the valuation has identified the feature correctly.
The property goes to manual review Macquarie and Bankwest
- What that can mean for you
- A result within 50m triggers a credit review rather than one automatic outcome.
- What I check
- I would give the assessor the exact address, a reliable boundary measurement and any useful valuation comments before relying on the loan.
No standard option where the rule applies AMP , Firstmac and Resimac
- What that can mean for you
- AMP and Firstmac use a 50m boundary test. Resimac publishes no distance and instead excludes an area affected by high tension powerlines.
- What I check
- I would establish whether the property is inside a measured boundary rule or an affected-area rule before comparing another lender.
Lender rules checked 3 August 2026. A general starting-point view of the 11 lenders named above, not a ranking, a recommendation or credit advice. Lending policy changes without notice, and any loan is subject to the lender's own credit assessment and approval of your full application.
Does an easement mean you need a bigger deposit?
An easement does not automatically mean the bank will lend less. The title, the valuation and what the easement allows still decide the result.
Your solicitor or conveyancer should explain what the registered dealing allows. The lender and valuer then look at the building position, access, intended use, proposed work, value and future saleability.
Legal question
What rights does the registered dealing give another party, and what can you build or change?
Valuation question
Does it affect the use, value or future buyer pool?
Loan question
Will the lender accept the title and valuation at the loan percentage you need?
Can you build or renovate near an easement?
Check the registered terms before planning an extension, shed, pool or driveway. For Powerlink easements, houses are not allowed within the easement and proposed work needs to be checked with Powerlink. Other easements can have different terms. Powerlink explains its approval process.
What about health and resale concerns?
Health evidence and distance rules
ARPANSA says scientific evidence has not established that the electric and magnetic fields found near powerlines cause health effects. Its powerlines guidance explains the evidence and links to further advice. A lender's 50m credit rule is not a medical safety distance or an electrical-work clearance.
Value and future sale
For resale, ask the valuer to consider comparable sales with similar exposure to the line or easement. Do not assume a fixed discount, guaranteed rental demand or that a lower asking price makes the property a bargain.
A motorway can be a dealbreaker in one policy and a non-event in another
Resimac excludes property in an area affected by a motorway. NAB's non-insured framework lists busy roads as a feature that does not require referral, although insured lending can still be referred through a valuer risk assessment.
That contrast is why "near a road" is not enough information. I need the exact address, road type, proposed loan percentage and the valuation method being used.
What should you check before applying?
- Property and loanThe exact address, purchase price and proposed loan;
- Title rightsThe title search and registered easement dealing;
- Distance measurementA survey or reliable measurement from the correct point;
- Feature typeThe type of line, substation or road, if it can be confirmed;
- ValuationAny valuation comments already received;
- Cash neededThe cash available if the maximum loan is reduced; and
- Building plansAny proposed building work near the easement.
A surveyor, network operator or other qualified professional should confirm the physical feature and measurement. Your solicitor or conveyancer should advise on the title. My role is to compare the finance and valuation paths against those facts.
Frequently asked questions
Related guides
Home loans by property type
Start with the property checks that apply to your purchase.
Read guideLVR calculator
Compare the property value with the loan amount the lender is being asked to approve.
Read guideChallenge a bank valuation
Check whether the issue is the value or a property rule.
Read guideUnusual property titles
Understand title and legal-use restrictions.
Read guideRural property home loans
Check access, services and easements on acreage.
Read guide

Experience and sources
How this guide was checked
Explanatory sources checked 29 September 2026. Lender comparisons retain the policy-check dates shown beside them. Confirm the selected lender's current requirements for your property before applying.
Nathan is a director and mortgage broker at Hunter Galloway. He has worked in mortgage broking since 2015, helping home buyers, property investors and borrowers whose applications have been declined elsewhere.
Check how this property feature changes my loan
Send me the address, title or easement document, price, proposed loan, deposit and any valuation comments you already have. I can identify the finance question and what still needs confirmation before you rely on the pre-approval.
Check my propertyor call 1300 088 065
This guide is general information, not loan approval, valuation, legal, surveying, property or engineering advice. Lender rules can change. The exact property, borrower and loan need to be assessed before making a decision from the result. Hunter Galloway Finance Pty Ltd T/A Mortgage Broker Brisbane - Hunter Galloway ABN 20 605 252 926. Credit Representative 476903 is authorised under Australian Credit Licence 389328. Your full financial situation would need to be reviewed before any offer or product is accepted.