


Why ANZ can stand out
- 01 / Professionals
Some professions can avoid LMI
Your profession may let you buy with a smaller deposit without paying lenders mortgage insurance (LMI). ANZ covers selected medical, allied-health, legal and accounting roles.
- 02 / Business owners
1 year may be enough
If you run an established business, ANZ may accept 1 year of lodged financial records. If your company pays you a regular wage, you may need fewer documents.
- 03 / First home buyers
Small-deposit options can work
If you qualify for the Australian Government 5% Deposit Scheme, you can buy with a smaller deposit. A family guarantee or buying from a relative may give you another option.
Could your job help you avoid LMI?
LMI is usually an extra cost when you borrow more than 80% of the property's value. ANZ can waive it for selected professions, but the exact occupation and qualification matter.
| Professional group | ANZ position | What to check |
|---|---|---|
| Doctors, dentists and registered specialists | Up to 95% without LMI: roughly a 5% deposit before costs | Current registration, exact occupation, ownership share and total borrowing. Loan purpose and repayment type affect the limit, so we check investment and interest-only applications separately. |
| Physios, chiropractors, optometrists and vets | Up to 90% without LMI: roughly a 10% deposit before costs | Your exact role must appear on ANZ's list. |
| Selected legal professionals | Up to 90% without LMI: roughly a 10% deposit before costs | Current practising status or the required evidence for your legal role. |
| Selected accountants and finance professionals | Up to 90% without LMI: roughly a 10% deposit before costs | Accepted qualification or membership. Institute of Public Accountants (IPA) membership is not listed. |
| Nurses and midwives | Not included in ANZ's professional waiver list | Compare lenders that include your role in their professional waiver program. |
| Pharmacists, psychologists and several other health roles | Not included in ANZ's professional waiver list | This also includes podiatrists, occupational therapists, osteopaths and radiographers. Compare a broader program. |
Could your job help you avoid LMI?
- ANZ position
- Up to 95% without LMI: roughly a 5% deposit before costs
- What to check
- Current registration, exact occupation, ownership share and total borrowing. Loan purpose and repayment type affect the limit, so we check investment and interest-only applications separately.
Physios, chiropractors, optometrists and vets
- ANZ position
- Up to 90% without LMI: roughly a 10% deposit before costs
- What to check
- Your exact role must appear on ANZ's list.
- ANZ position
- Up to 90% without LMI: roughly a 10% deposit before costs
- What to check
- Current practising status or the required evidence for your legal role.
- ANZ position
- Up to 90% without LMI: roughly a 10% deposit before costs
- What to check
- Accepted qualification or membership. Institute of Public Accountants (IPA) membership is not listed.
- ANZ position
- Not included in ANZ's professional waiver list
- What to check
- Compare lenders that include your role in their professional waiver program.
Pharmacists, psychologists and several other health roles
- ANZ position
- Not included in ANZ's professional waiver list
- What to check
- This also includes podiatrists, occupational therapists, osteopaths and radiographers. Compare a broader program.
Our guides for physiotherapists, chiropractors, optometrists and vets compare deposit options and LMI waivers across lenders.
If ANZ's waiver doesn't cover your job, compare other lenders in our guides for pharmacists, psychologists, podiatrists, occupational therapists, osteopaths and radiographers.
Starting as an intern? Our home loan guide for junior doctors compares registration requirements across lenders and explains the options before your first payslip.
ANZ does not set the $120k minimum professional income used by some lenders for similar legal and accounting waivers. You still need enough income to afford the loan.
Recent job change or career break? Check the dates
Changed jobs recently? The length of the gap can determine whether ANZ will consider you now or ask you to build up more time in the new role.
Broker assessment
Why ANZ treated our client's return from travel as a new job
Our client returned to the same employer after travelling for 14 months. She had resigned before leaving, so ANZ treated her return as a new job rather than continuous employment.
The break exceeded 28 days, so ANZ would normally need her to complete 3 months in the new role before proceeding. Her previous years with that employer didn't remove the requirement.
If you're in this position, we compare lenders' employment rules before you apply. Another lender may accept your new contract and current income sooner, depending on your circumstances.
| Your work situation | What ANZ generally wants | Why it matters |
|---|---|---|
| Permanent full-time or part-time | 3 months in the current job, or a recent move with a gap under 28 days | A longer gap can mean waiting until 3 months in the new role |
| Casual, temporary, contract or second job | At least 6 months of income, generally without a gap of 28 days or more | ANZ also checks how long you've been in your current job |
| Parental or formal career leave | You remain employed and return within 12 months, with the date and income confirmed | ANZ may use the future income if expenses while away are covered |
Employment history and leave requirements
Permanent full-time or part-time
- What ANZ generally wants
- 3 months in the current job, or a recent move with a gap under 28 days
- Why it matters
- A longer gap can mean waiting until 3 months in the new role
Casual, temporary, contract or second job
- What ANZ generally wants
- At least 6 months of income, generally without a gap of 28 days or more
- Why it matters
- ANZ also checks how long you've been in your current job
Parental or formal career leave
- What ANZ generally wants
- You remain employed and return within 12 months, with the date and income confirmed
- Why it matters
- ANZ may use the future income if expenses while away are covered
ANZ's automated credit scoring
ANZ uses automated credit scoring for most home loan applications. If you already bank with ANZ, the way you manage your accounts can affect the result too. Some cases can still reach a senior credit assessor, but a decline from this automated assessment cannot be overturned for properties in certain restricted locations.
Recent hardship, repeated late or dishonoured payments, payday loans, or gambling that regularly pushes an account over its limit can all make it harder to get approved with ANZ. We'll look at what happened and how you're managing the account now before you apply.
Where ANZ can help first home buyers
ANZ participates in the Australian Government 5% Deposit Scheme. If you qualify, you may be able to buy with a 5% deposit as a first home buyer, or 2% as an eligible single parent, without paying LMI.
- Useful overlap
Self-employed with a 5% deposit
ANZ's 2-year financial rule is linked to whether LMI applies. Because an eligible Scheme loan does not use LMI, ANZ may still accept 1 year of financials even when you borrow 95% of the property's value.
- Separate offer
$3k first home buyer cashback
ANZ currently advertises $3k for eligible first home buyers with an eligible loan of at least $250k. It cannot be combined with a government guarantee or ANZ LMI waiver.
The cashback is paid after settlement, so it cannot fund your upfront deposit. To qualify, you need an eligible ANZ account when the loan is drawn down, and you must draw down within 180 days of applying. Payment is within 60 days of drawdown. ANZ Plus loans are excluded, and the offer can be withdrawn. Check the current offer terms before relying on it.
Will ANZ ask to see your savings history?
ANZ generally checks 3 months of savings history when you borrow more than 90% of the property's value. The government scheme has its own deposit rules. With a larger deposit, ANZ may not need that history unless another part of the application calls for it. For some first home buyers, 3 months of on-time rent can help show the same savings habit. It does not replace the cash you need for the deposit and buying costs.
Our genuine savings guide explains what counts and which records to keep.
Buying with help from family
- Buying with family help
ANZ family guarantee
An eligible parent, step-parent, grandparent, sibling or child can use equity in their home to support your purchase. ANZ can also consider vacant land and a fixed-price build. The loan must be principal and interest, and the guarantee cannot be combined with a professional LMI waiver.
- Buying below market value
Buying a home from family below market value
If a relative genuinely sells you a home for less than it is worth, ANZ may use the valuation when working out the deposit needed. You still need at least 5% of the contract price, plus costs, from your own funds.
A guarantee puts the family member's property at risk, so the structure and exit plan matter. Read our family guarantor home loan guide.
Self-employed? You may only need 1 year of financial records
You may not need 2 years of income figures, but ANZ still needs lodged tax records and an established business. The documents depend on your business structure.
| Business structure | What ANZ normally asks for | Worth knowing |
|---|---|---|
| Sole trader | Individual tax return and Australian Taxation Office (ATO) Notice of Assessment | Company financial statements are not normally required |
| Partnership | Individual return, Notice of Assessment and business tax return | A business activity statement (BAS) is not a standard requirement for every application |
| Company | Individual return and Notice of Assessment, plus company return, profit and loss and balance sheet | An accountant's letter does not replace the company documents |
Self-employed? You may only need 1 year of financial records
Sole trader
- What ANZ normally asks for
- Individual tax return and Australian Taxation Office (ATO) Notice of Assessment
- Worth knowing
- Company financial statements are not normally required
Partnership
- What ANZ normally asks for
- Individual return, Notice of Assessment and business tax return
- Worth knowing
- A business activity statement (BAS) is not a standard requirement for every application
Company
- What ANZ normally asks for
- Individual return and Notice of Assessment, plus company return, profit and loss and balance sheet
- Worth knowing
- An accountant's letter does not replace the company documents
1 year of income figures does not mean a 1-year-old business
The business generally needs at least 18 months of Australian Business Number (ABN) or Australian Company Number (ACN) history. ANZ may then use 1 year of lodged financial records if LMI does not apply.
If LMI applies, ANZ generally wants 2 years. Where it accepts 1 year for an insured loan, it may use only 80% of the business profit when calculating how much you can borrow.
Paid a regular wage from your own company?
If you are a Pty Ltd director and a direct shareholder, you may be able to use Company Wages after at least 6 months of regular wages. Your ABN or ACN must have been registered for at least 18 months.
ANZ asks for a payslip dated within 60 days and your most recent ATO Income Statement. If that statement shows less than 6 months of salary, it also needs the previous year's statement. ANZ may ask for more documents.
Company Wages does not work for sole traders, partnerships or trusts. See our self-employed home loan guide.
How ANZ works out what you can borrow
ANZ checks your income, living costs, debts, credit-card limits and dependants. It also looks at what the loan is for and whether you can afford the repayments.
Why 6 times your income matters
ANZ compares your total debt after the new loan with the gross annual income it accepts. This is the debt-to-income ratio, or DTI. If ANZ accepts $100k of income, 6 times income means $600k of total debt.
Total debt below 6 times income
ANZ's smaller-deposit options are generally more open. In an eligible case, that can mean borrowing up to 95% of the property value, plus some LMI where it applies.
Total debt at or above 6 times income
If you are new to ANZ, you may be limited to 90% of the property value for a standard loan to live in, or need a larger deposit for an investment. Different limits can apply if you already borrow with ANZ.
ANZ also checks whether you can afford the repayments after your living costs.
| Item | How ANZ generally treats it | Practical effect |
|---|---|---|
| Loan repayments | Tests the rate at 3% above the actual rate, subject to a 5.1% minimum | A 6% loan rate would be tested at 9% |
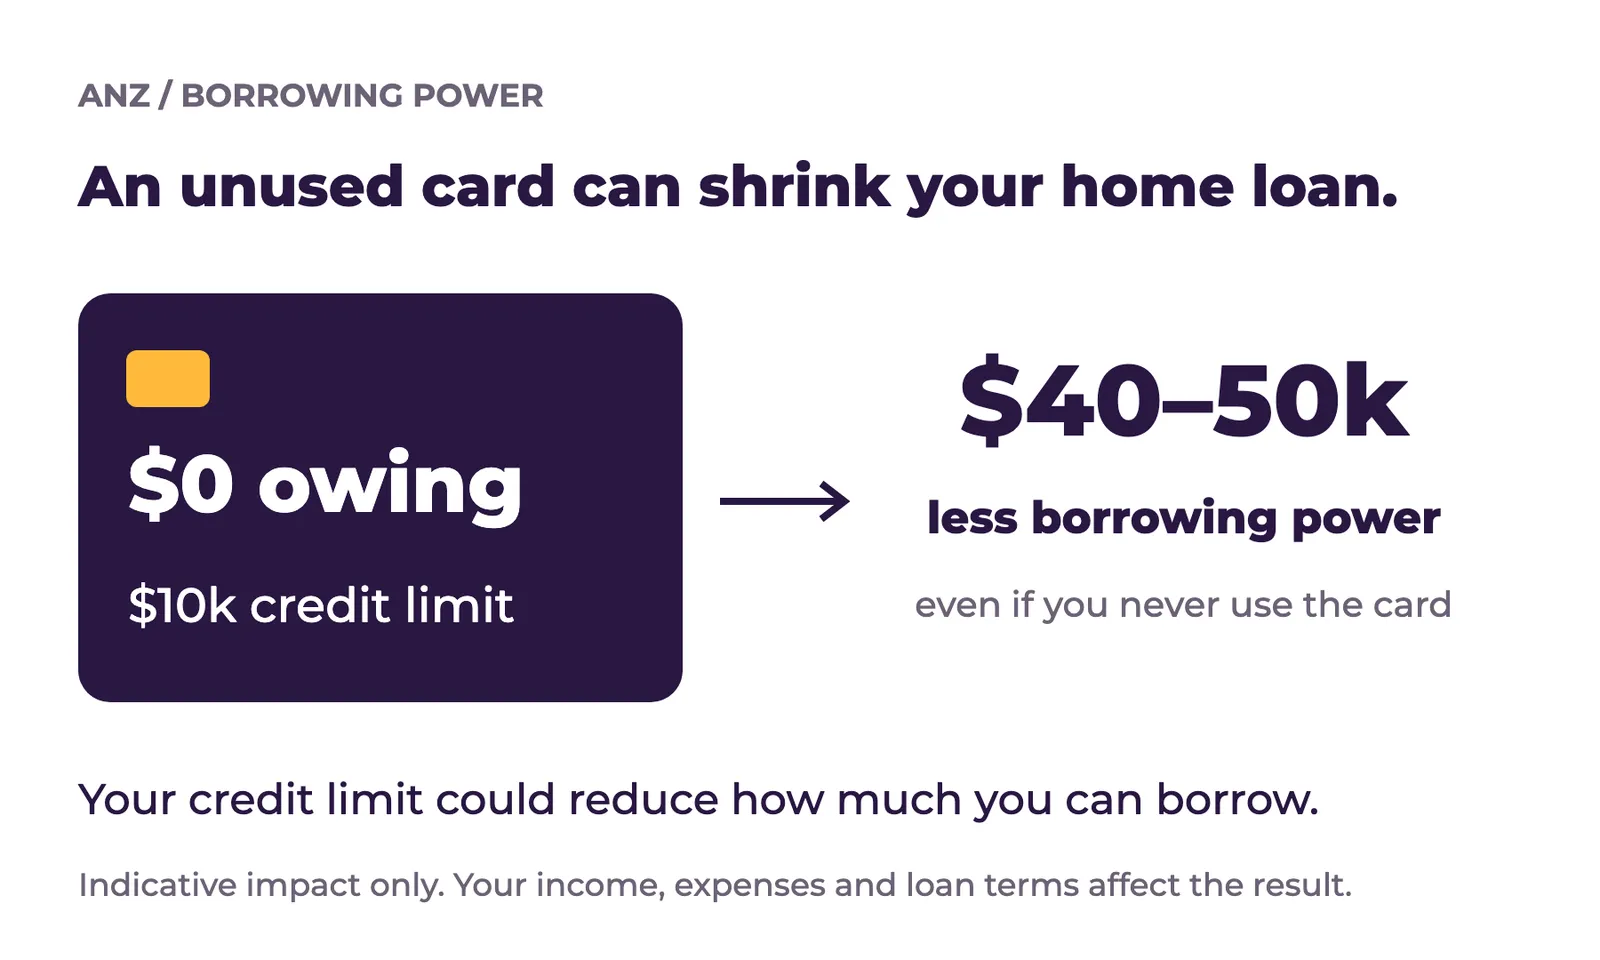
| Credit cards | Monthly commitment equal to 3.8% of the limit | A $10k limit can count as $380 a month even with a $0 balance |
| Long-term rent | Usually 90%, capped at a 7% gross rental yield | Very high advertised rent may be trimmed |
| Short-stay rent | Usually 80%, with the same 7% yield cap and a longer income history | Airbnb-style income normally needs 12 months of records or the latest tax return |
| Regular allowances and shift loading | May be used at 100% when the income is accepted | This can help if shift loading makes up a regular part of your pay |
| Overtime, bonus and commission | Usually 80% of the accepted amount | ANZ leaves a buffer rather than counting every dollar |
| HELP or HECS | Counts the compulsory repayment but leaves the balance out of DTI | Your compulsory repayment can reduce how much you can borrow, even though ANZ excludes the debt balance from DTI |
| Owner-occupied interest-only | Maximum 80% of the property value | You generally need at least a 20% deposit before costs |
How ANZ works out what you can borrow
Loan repayments
- How ANZ generally treats it
- Tests the rate at 3% above the actual rate, subject to a 5.1% minimum
- Practical effect
- A 6% loan rate would be tested at 9%
Credit cards
- How ANZ generally treats it
- Monthly commitment equal to 3.8% of the limit
- Practical effect
- A $10k limit can count as $380 a month even with a $0 balance
Long-term rent
- How ANZ generally treats it
- Usually 90%, capped at a 7% gross rental yield
- Practical effect
- Very high advertised rent may be trimmed
Short-stay rent
- How ANZ generally treats it
- Usually 80%, with the same 7% yield cap and a longer income history
- Practical effect
- Airbnb-style income normally needs 12 months of records or the latest tax return
Regular allowances and shift loading
- How ANZ generally treats it
- May be used at 100% when the income is accepted
- Practical effect
- This can help if shift loading makes up a regular part of your pay
Overtime, bonus and commission
- How ANZ generally treats it
- Usually 80% of the accepted amount
- Practical effect
- ANZ leaves a buffer rather than counting every dollar
HELP or HECS
- How ANZ generally treats it
- Counts the compulsory repayment but leaves the balance out of DTI
- Practical effect
- Your compulsory repayment can reduce how much you can borrow, even though ANZ excludes the debt balance from DTI
Owner-occupied interest-only
- How ANZ generally treats it
- Maximum 80% of the property value
- Practical effect
- You generally need at least a 20% deposit before costs
If you have a student loan, see how HECS-HELP debt affects your home loan before deciding whether to use your savings to pay it down.
ANZ products, fees and pre-approval
This review covers ANZ's broker home loans. ANZ Plus has separate products, fees and eligibility rules.
| Loan | Useful features | What to watch |
|---|---|---|
| Standard Variable | Extra repayments, redraw and optional ANZ One offset | One $10-a-month offset per eligible loan or split |
| Simplicity PLUS | Basic variable loan with extra repayments and redraw | No offset |
| ANZ Fixed | Fixed terms of 1 to 5, 7 or 10 years, depending on the loan and repayment type; offset on eligible 1-year fixed loans | Rate lock is available for 1 to 5-year fixed terms; extra-repayment limits and early repayment costs apply |
ANZ products, fees and pre-approval
Standard Variable
- Useful features
- Extra repayments, redraw and optional ANZ One offset
- What to watch
- One $10-a-month offset per eligible loan or split
Simplicity PLUS
- Useful features
- Basic variable loan with extra repayments and redraw
- What to watch
- No offset
ANZ Fixed
- Useful features
- Fixed terms of 1 to 5, 7 or 10 years, depending on the loan and repayment type; offset on eligible 1-year fixed loans
- What to watch
- Rate lock is available for 1 to 5-year fixed terms; extra-repayment limits and early repayment costs apply
Not sure whether the offset fee is worth it? Our offset account guide explains how your savings reduce the balance used to calculate interest.
3 fees worth knowing
- $0
Loan administration
No ANZ loan administration or annual package fee. Optional-feature fees, early repayment costs and government charges can still apply.
- $10/month
ANZ One offset
The fee applies to each linked offset.
- $750 per $1m
Optional rate lock
Charged per fixed loan, for each $1m or part thereof. A $1.3m fixed loan costs $1,500 to lock. Separate fixed splits each attract a fee. Available for eligible fixed terms of 1 to 5 years.
Fixed-loan extra repayments
Each year of the fixed period, ANZ allows extra repayments up to the lower of 5% of the starting fixed balance or $5k. On a $700k fixed loan, the limit is $5k, not $35k.
Early repayment costs can apply if you exceed the allowance, repay or refinance the loan in full, or change the rate during the fixed period. Ask ANZ for a quote before making a large payment. Our fixed-loan break costs guide explains what to check.
ANZ pre-approval: how long does it last?
ANZ checks your income, expenses, debts and credit history, so the enquiry appears on your credit file. Once you find a property, ANZ still needs to check the valuation and remaining loan conditions.
Check these before committing to an unconditional purchase. ANZ says pre-approval generally lasts around 3 months if nothing changes. See our ANZ pre-approval guide.
If your pre-approval expires, ANZ says you need to reapply. Check the expiry date and leave time for updated documents before relying on it for a purchase.
How quickly is ANZ looking at applications?
When we checked on 11 September 2026, ANZ listed 2 business days for simple applications without LMI. Its other listed home loan assessment queues were 4 business days. These are estimates for complete broker applications, not a promise of approval or settlement.
ANZ listed 2 business days to review additional documents. Your income, property, valuation or missing paperwork can add time. We'll check the current queue against your contract deadline before you apply.
Already with ANZ?
If your fixed rate is ending or the loan has not been reviewed recently, ask ANZ to sharpen the rate and compare the full cost of refinancing. We can check the rate, offset fee, exit costs and other lenders before you move. See our refinance guide.
Selling, refinancing or paying off your ANZ loan? Our ANZ discharge guide explains how to start, what to have ready and how long to allow.
Property restrictions: check before you sign
Apartments, acreage, building projects and unusual titles can change how much ANZ will lend. Check the relevant property details before you sign.
Property types that need a closer check
Before you commit
Send us the property details early
A financial pre-approval does not mean ANZ will accept every home. It can reduce the loan, ask for more information or decline the property after valuation.
- Check how much ANZ will lend on that address
- Leave time for valuation and follow-up questions
ANZ compared with alternatives
Start with the rule most likely to decide your application. The lowest rate is not useful if the lender cannot use your income, profession or property.
| Your situation | Why ANZ may work | When another lender may be better |
|---|---|---|
| Eligible doctor or dentist | Up to 95% without LMI, with no $120k minimum income requirement for the waiver | Compare other lenders if you also need bridging or a family guarantee. ANZ's waiver can't be combined with either. |
| Nurse or broader allied health | Nurses are outside ANZ's professional waiver list; selected allied-health roles may qualify. | NAB or another lender may cover a wider list |
| Self-employed with a strong latest year | You may be able to use 1 year of tax records. If your company pays you a regular wage, you may need fewer documents. | Compare how Westpac and other lenders calculate your business income, and whether needing LMI changes the documents or deposit they require. |
| Returning after extended travel | Formal leave may work when employment continued | Another lender may be faster if you resigned or had a gap of 28 days or more |
| First home buyer | ANZ participates in the 5% Deposit Scheme | Compare the borrowing result and how each bank treats your income |
| Buying before selling | ANZ offers bridging finance | Compare the equity needed, repayments during the overlap and the loan left after selling. St George also offers bridging, but LMI is not available on that loan. |
| Unusual property | Standard homes are simpler | Compare before signing for commercial use, unusual title or relocatable construction |
ANZ compared with alternatives
Eligible doctor or dentist
- Why ANZ may work
- Up to 95% without LMI, with no $120k minimum income requirement for the waiver
- When another lender may be better
- Compare other lenders if you also need bridging or a family guarantee. ANZ's waiver can't be combined with either.
Nurse or broader allied health
- Why ANZ may work
- Nurses are outside ANZ's professional waiver list; selected allied-health roles may qualify.
- When another lender may be better
- NAB or another lender may cover a wider list
Self-employed with a strong latest year
- Why ANZ may work
- You may be able to use 1 year of tax records. If your company pays you a regular wage, you may need fewer documents.
- When another lender may be better
- Compare how Westpac and other lenders calculate your business income, and whether needing LMI changes the documents or deposit they require.
Returning after extended travel
- Why ANZ may work
- Formal leave may work when employment continued
- When another lender may be better
- Another lender may be faster if you resigned or had a gap of 28 days or more
First home buyer
- Why ANZ may work
- ANZ participates in the 5% Deposit Scheme
- When another lender may be better
- Compare the borrowing result and how each bank treats your income
Buying before selling
- Why ANZ may work
- ANZ offers bridging finance
- When another lender may be better
- Compare the equity needed, repayments during the overlap and the loan left after selling. St George also offers bridging, but LMI is not available on that loan.
Unusual property
- Why ANZ may work
- Standard homes are simpler
- When another lender may be better
- Compare before signing for commercial use, unusual title or relocatable construction
Hunter Galloway lender rating
ANZ broker score
ANZ scores well for selected professional and self-employed borrowers, family guarantees and its straightforward core loan range. Longer work gaps, automated credit scoring and unusual-property limits hold the score back.
7.2/10
Good, with clear limits
Our rating across 6 categories
Score breakdown
Each category is scored out of 10
- Credit policy fitUseful professional and self-employed options, with firm job-gap and waiver exclusions8.0/10
- Borrowing capacityCan be competitive below 6 times income, but ANZ becomes stricter above that7.5/10
- Property acceptanceStandard homes are easier than unusual titles, small units and complex construction6.5/10
- Product and offset featuresNo package fee, a paid offset and a useful 1-year fixed offset option7.5/10
- Application speed and certaintyAutomated credit scoring can be quick, but complex declines and changing queues reduce certainty6.5/10
- Ongoing pricing and serviceAn established app and branch network; compare the rate with other lenders7.0/10
Experience and sources
How this guide was checked
Policy reviewed 11 September 2026 by Nathan Vecchio. Wording updated 7 October 2026.
The lending comparison draws on ANZ's Mortgage Credit Requirements dated 17 August 2026 and the public sources below. We confirm the current employment, repayment and property rules against your application before recommending a loan.
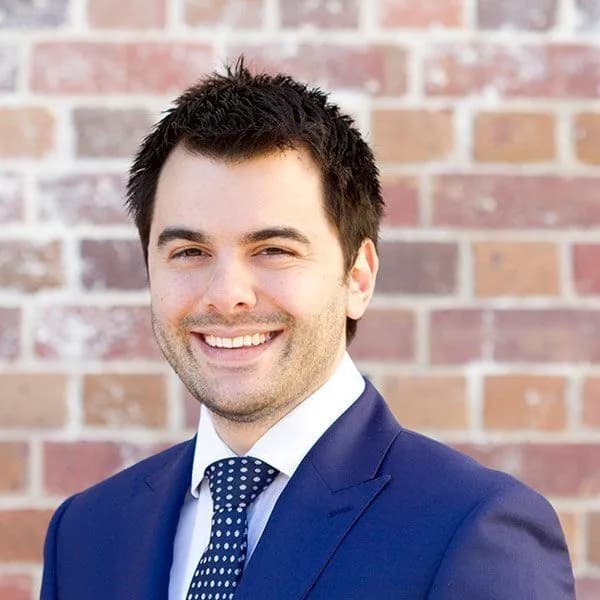
Joshua has worked in mortgage broking since 2011 and holds Diploma and Certificate IV qualifications in finance and mortgage broking. See Joshua's experience, qualifications and published work.
This guide is general information only. It doesn't consider your objectives, financial situation or needs, and lender policy can change. Talk to a broker before acting on it.
Sources and check dates
- ANZ Mortgage Credit Requirements, 17 August 2026.
- ANZ home loans: checked 11 September 2026
- ANZ One offset: checked 11 September 2026
- ANZ Fixed Rate home loan: checked 11 September 2026
- ANZ pre-approval: checked 11 September 2026
- ANZ first home buyer options: checked 11 September 2026
- ANZ Security Guarantee: checked 11 September 2026
- ANZ Construction Loan: checked 11 September 2026
- 5% Deposit Scheme lenders: checked 11 September 2026
- MoneySmart home loan guidance
- ANZ medical and dental LMI waiver brochure (August 2024 edition): public eligibility and lending limits, checked 11 September 2026
- ANZ professional LMI waiver fact sheet: eligible and excluded professions, checked 11 September 2026
- ANZ self-employed home loans: income documents and Company Wages, checked 11 September 2026
- ANZ broker service levels: application assessment and document-review estimates, checked 11 September 2026
- ANZ bridging loans: term and repayment requirements, checked 11 September 2026
ANZ's rules, fees, rates and review times can change. We confirm the current position before recommending a lender or submitting an application.
How are we paid?
The lender pays us commission, which we disclose before you proceed. Hunter Galloway is independently owned.
We compare more than 30 lenders and must put your interests first. Our Brisbane mortgage brokers can check whether ANZ suits your income and deposit, and explain where another lender may work better. Read how we review lenders, including the duty to put clients first for mortgage brokers.
What home buyers say about us
 Google
“Clear, incredibly responsive and accurate.”
- Google
“Preapprovals done quickly and efficiently.”
- Google
“Reassuring every step of the way.”
More help with your home loan
NAB home loan review
Compare health-professional and self-employed options.
Read guideWestpac home loan review
Compare professional, self-employed and family-support options.
Read guideLMI Waivers
See which professions may avoid LMI.
Read guideBuying your first home
Plan your deposit, costs and pre-approval.
Read guideSelf-employed home loans
See how lenders assess business income.
Read guideGuarantor home loans
Understand the guarantee, risks and exit plan.
Read guide
ANZ home loan FAQs
Want to know whether ANZ fits your situation?
We can check your income, deposit and property against ANZ and other suitable lenders before you apply.
or call 1300 088 065
Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328.