What should you check before the move?
1 offset account after the move to ANZ
After your Suncorp home loan moves to ANZ, you’ll have 1 offset account linked to that loan. Money in your other accounts will no longer reduce your home loan interest. You can move your savings into the offset, or compare lenders that offer multiple offset accounts.
Your minimum repayment could increase
If you’ve made extra repayments and can still withdraw that money through redraw, your minimum repayment could go up at ANZ. This can happen even if your interest rate and the amount you owe stay the same.
You may lose access to extra repayments
If your loan is in a company name or your home is still being built, extra repayments left in the loan when it moves will go towards paying it down. You won’t be able to take that money back out. On a fixed-rate loan, you’ll need to wait until the fixed term ends to use redraw.
Paid-off loans will close after the move
Once your Suncorp loan moves to ANZ, it will close if you no longer owe anything or have paid in more than you owe. When it closes, you’ll lose access to extra repayments through redraw. Any money left after the loan is paid off will be returned under the loan terms. Speak with Suncorp before the move if you want to keep the loan open.
Get in touch with us before the move and we’ll compare your refinance options. We can check your proposed ANZ repayments and fees, look for the features you want to keep, and see whether switching is worth the cost. Have your latest loan statement and the letter or email about your move handy.
Will the move to ANZ suit you? Let’s compare your options.
What the move to ANZ means for your home loan
ANZ bought Suncorp Bank in July 2024. Existing home loans are scheduled to move in the first half of 2027.
You do not need to refinance just because your loan is moving. Keep making your repayments and read the notices about your own loan.
| Your situation | What happens now | What to check |
|---|---|---|
| You already have a Suncorp loan | Keep banking with Suncorp until you receive instructions for moving your accounts. | Check your notices for changes to repayments, fees, offset and redraw. |
| Your application is underway | Applications lodged before 7 October 2026 will still be assessed. Final approval and loan documents must be issued by 27 October 2026. Settlement must happen by 26 December 2026. | Ask your broker what is still needed and whether your application can meet both cut-offs. |
| You need a new purchase or refinance loan | You need to apply to ANZ or another lender. | ANZ uses its own lending rules. Compare its rate, fees and features with other available loans. |
| You want to borrow more or change your existing loan | Ask Suncorp whether it can make the change before you commit to it. | If you need a new application, compare the costs and requirements with ANZ or another suitable lender. |
What to do during the move to ANZ
You already have a Suncorp loan
- What happens now
- Keep banking with Suncorp until you receive instructions for moving your accounts.
- What to check
- Check your notices for changes to repayments, fees, offset and redraw.
Your application is underway
- What happens now
- Applications lodged before 7 October 2026 will still be assessed. Final approval and loan documents must be issued by 27 October 2026. Settlement must happen by 26 December 2026.
- What to check
- Ask your broker what is still needed and whether your application can meet both cut-offs.
You need a new purchase or refinance loan
- What happens now
- You need to apply to ANZ or another lender.
- What to check
- ANZ uses its own lending rules. Compare its rate, fees and features with other available loans.
You want to borrow more or change your existing loan
- What happens now
- Ask Suncorp whether it can make the change before you commit to it.
- What to check
- If you need a new application, compare the costs and requirements with ANZ or another suitable lender.
ANZ says home loans will move in the first half of 2027. The banks will tell you when your accounts will move. Some loan changes will no longer be available closer to that date, so ask early if you need to change your loan.
To check the latest information, visit Suncorp’s Move Hub directly or call 13 11 75. Keep your email, mobile number and postal address up to date in the Suncorp app or Internet Banking.
Be cautious with messages about the move. The banks say they will not ask you to transfer money to keep it safe, share passwords or PINs, or log in through an email or SMS link about the move.
Read the Suncorp Move Hub and the bank’s Move Hub loan changes. To compare a new loan, see our ANZ home loan review.
ANZ is on the Australian Government’s 5% Deposit Scheme participating-lender list. You still need to meet the scheme rules and ANZ’s lending requirements. Our 5% Deposit Scheme guide explains who can qualify.
Why your minimum repayment could rise
Your minimum repayment could go up at ANZ if you’ve been paying more than required and can still withdraw that extra money. Suncorp calls this Cashback. Other banks usually call it redraw. This change affects principal-and-interest loans, where each repayment pays off some of the loan as well as the interest.
Your extra repayments will still reduce the interest you pay. Your first minimum repayment after the move will stay the same. Any change to the minimum will start at least 30 days after ANZ sends you a notice. See the bank’s repayment guidance.
If you use redraw after moving to ANZ, that withdrawal will not change your minimum repayment. You will owe more and pay interest on the higher balance.
| What is calculated | At Suncorp | At ANZ |
|---|---|---|
| Minimum principal-and-interest repayment | May use the lower amount you owe after extra repayments | Adds the extra repayments you can still redraw back to the amount you owe |
| Interest charged | Uses the amount you owe, with any linked offset savings also reducing interest | Still uses the amount you owe, with any linked offset savings also reducing interest |
How extra repayments affect your minimum repayment
Minimum principal-and-interest repayment
- At Suncorp
- May use the lower amount you owe after extra repayments
- At ANZ
- Adds the extra repayments you can still redraw back to the amount you owe
Interest charged
- At Suncorp
- Uses the amount you owe, with any linked offset savings also reducing interest
- At ANZ
- Still uses the amount you owe, with any linked offset savings also reducing interest
How much could the minimum repayment rise?
Suncorp Bank gives these examples of how extra repayments made before the move could affect your new minimum. Both assume a 7% interest rate and 25 years left on the loan.
| Loan balance and available redraw | Suncorp minimum per month | ANZ minimum per month | Monthly increase |
|---|---|---|---|
| $360k owing, $40k in redraw | $2,544 | $2,827 | $283 |
| $250k owing, $150k in redraw | $1,767 | $2,827 | $1,060 |
These are the bank’s examples. Your repayment will depend on your own rate, balance, available redraw and remaining loan term. Keeping up the higher repayments can help you pay off the loan sooner and pay less interest overall, provided you do not redraw the extra funds and the rate stays the same.
What if the higher repayment is hard to manage?
You can ask the bank to use some or all of your redraw money to pay down the loan permanently and lower your minimum repayment. You won’t be able to withdraw that money again. If your rate is fixed, you need to ask before the move. The bank’s repayment options explain how this works.
Another option is to ask the bank to use your available redraw to cover the extra amount due each month. This uses up money you’ve already paid ahead. Once it runs out, you’ll need to cover the full minimum repayment or discuss your options with ANZ. Ask the bank to arrange this and explain how it would work for your loan.
To estimate your own payment, use Suncorp’s repayment calculator. The figure in your ANZ notice is the one to budget for. The calculator does not cover construction loans or loans in a company name.
What if you pay interest only?
The bank will keep calculating interest daily on what you owe and charging it monthly during your interest-only period. Your payment can still change with your rate, loan balance or the number of days in the month.
When that period ends, you’ll start paying back the loan as well as the interest over the remaining term. The ANZ repayment changes explained above will then apply.
What happens to your offset accounts?
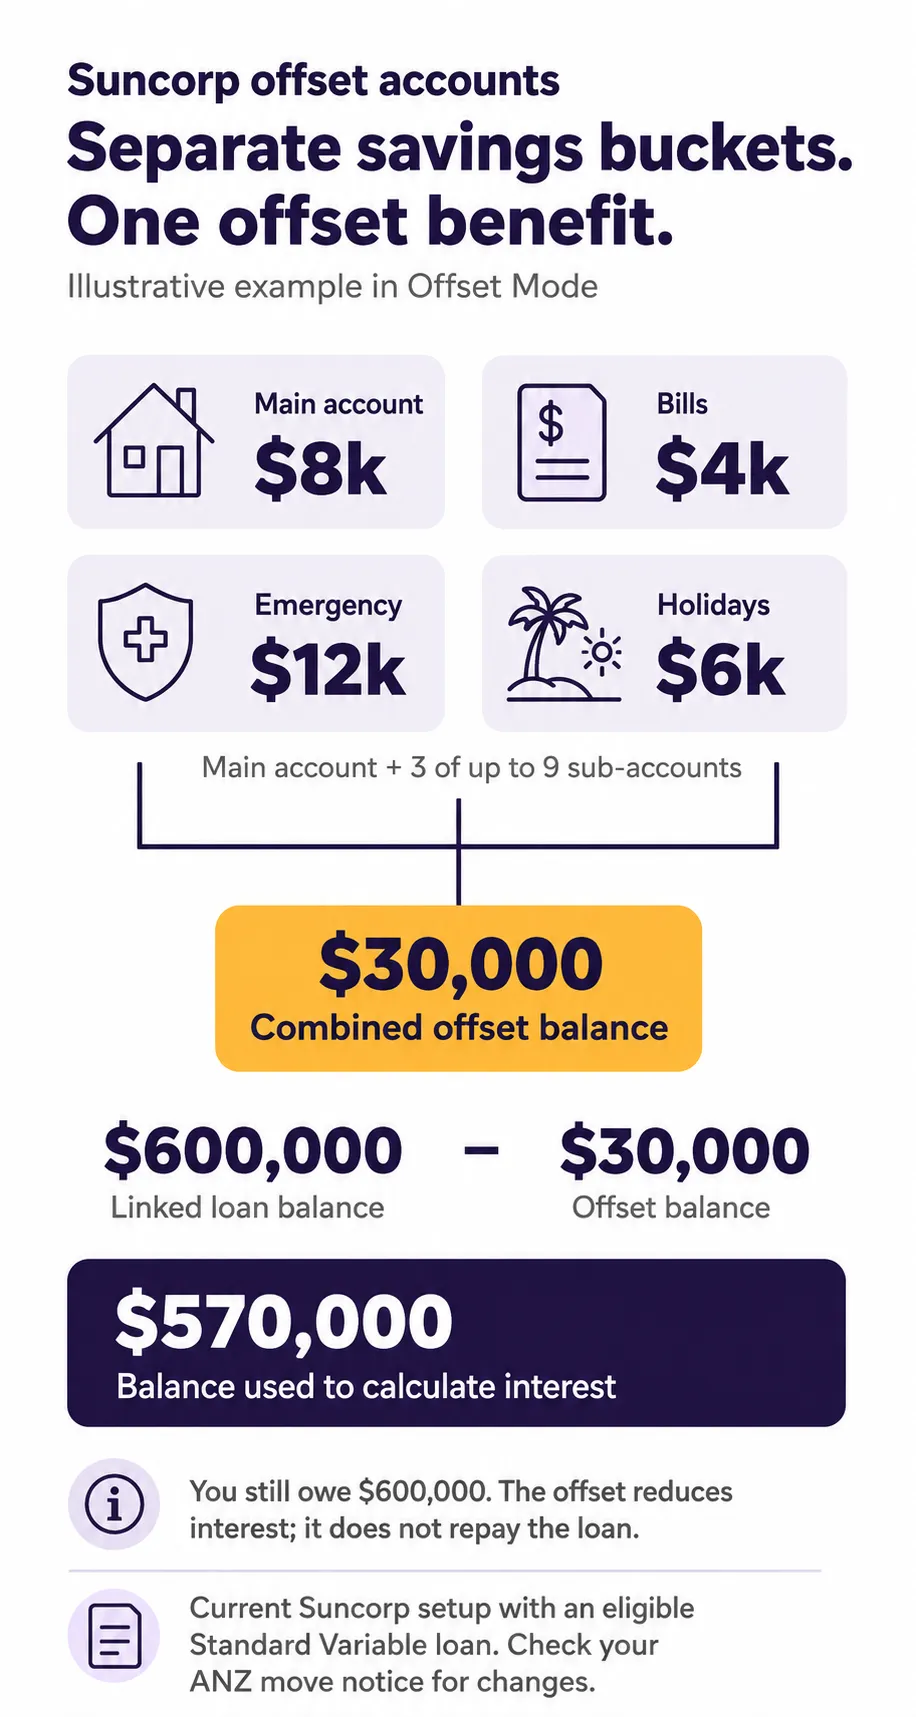
Before the move, an eligible Suncorp Standard Variable loan lets you keep savings in your Everyday Options main account and up to 9 sub-accounts. The money in all of these accounts reduces your loan interest.
After the move, you’ll have 1 ANZ One Offset account linked to that loan. Money in your other accounts will stop reducing your home loan interest. See Suncorp’s offset changes.
| Current account | After the move | Reduces home loan interest? |
|---|---|---|
| Everyday Options main account in Offset Mode | ANZ One Offset | Yes, while linked to your loan |
| Everyday Options sub-accounts | ANZ Access Advantage | No |
Where your offset savings go at ANZ
Everyday Options main account in Offset Mode
- After the move
- ANZ One Offset
- Reduces home loan interest?
- Yes, while linked to your loan
Everyday Options sub-accounts
- After the move
- ANZ Access Advantage
- Reduces home loan interest?
- No
You can move your savings into the main offset so the full amount keeps reducing your loan interest. If bills or regular transfers come out of your sub-accounts, check those payments before moving the money.
How the Suncorp setup works before the move
- 9
Separate savings buckets
- 100%
Savings used to reduce interest
- $75
One-off offset fee outside Home Package Plus
Main account
Your pay can land here and cover everyday spending.
Named buckets
Keep money aside for rates, holidays, school, bills or an emergency fund.
Read our offset guide and compare Macquarie, ING and Bankwest for different ways of linking savings to your loan.
Will you still be able to use redraw?
Redraw lets you take out extra repayments you’ve made on your loan. If you rely on that money for emergencies, check whether you’ll still be able to use it after the move. Check the cut-off in your move notice and speak with Suncorp Bank before that date. If your notice does not give a date, ask the bank to confirm it.
| Your loan | What changes |
|---|---|
| Fixed rate | You won’t be able to withdraw extra repayments left in the loan until the fixed term ends. |
| Paid off, or you’ve paid in more than you owe | The loan will close after it moves to ANZ. You’ll lose access to redraw. Any money left after paying off the loan will be returned under the loan terms. |
| Held in a company name | Extra repayments left in the loan at the move will pay it down permanently. ANZ won’t let you withdraw them later. |
| Still under construction | Extra repayments left in the loan at the move will pay it down permanently. You also won’t be able to withdraw extra repayments made while construction continues. |
Redraw changes to check before the move
Fixed rate
- What changes
- You won’t be able to withdraw extra repayments left in the loan until the fixed term ends.
Paid off, or you’ve paid in more than you owe
- What changes
- The loan will close after it moves to ANZ. You’ll lose access to redraw. Any money left after paying off the loan will be returned under the loan terms.
Held in a company name
- What changes
- Extra repayments left in the loan at the move will pay it down permanently. ANZ won’t let you withdraw them later.
Still under construction
- What changes
- Extra repayments left in the loan at the move will pay it down permanently. You also won’t be able to withdraw extra repayments made while construction continues.
If your loan is paid off but you want to keep it open, read Suncorp’s zero-balance loan instructions and ask whether withdrawing available redraw before the move would keep your loan open. For loans in a company name, ask Suncorp how to access any available extra repayments before the move. If your rate is fixed, book an appointment to discuss your options.
Want to keep multiple offsets or access to extra repayments?
Selling, refinancing or paying off your Suncorp loan? Our Suncorp discharge guide explains how to start, what to have ready and how long to allow.
Compare repayments, fees and loan features
What to compare before you refinance
Scroll to see more columns
| Check | Your proposed ANZ loan | Another lender |
|---|---|---|
| Repayments | Use the amount and start date in your ANZ notice. | Compare repayments using the same remaining loan term. |
| Offsets | Only the linked ANZ One Offset will reduce your loan interest. | Check how many accounts can offset the loan and what they cost. |
| Redraw | Check your loan type and whether you can still withdraw extra repayments. | Check access rules and any restrictions before moving. |
| Total cost | Check your rate, package fee and other ongoing fees. | Include discharge, application and any fixed-rate break costs. |
- Your proposed ANZ loan
- Use the amount and start date in your ANZ notice.
- Another lender
- Compare repayments using the same remaining loan term.
- Your proposed ANZ loan
- Only the linked ANZ One Offset will reduce your loan interest.
- Another lender
- Check how many accounts can offset the loan and what they cost.
- Your proposed ANZ loan
- Check your loan type and whether you can still withdraw extra repayments.
- Another lender
- Check access rules and any restrictions before moving.
- Your proposed ANZ loan
- Check your rate, package fee and other ongoing fees.
- Another lender
- Include discharge, application and any fixed-rate break costs.
Our refinancing guide explains the costs and steps involved in changing lenders.
Does ANZ match your views on ethical banking?
Was fossil fuel lending one reason you chose Suncorp Bank? Its responsible banking policy excludes direct finance to companies involved in thermal coal mining, coal-fired electricity, oil and gas projects, and expansion of existing oil and gas assets. ANZ’s energy lending policy allows some fossil fuel lending under its conditions. Check whether those conditions fit your priorities before your loan moves.
ANZ has owned Suncorp Bank since July 2024. If you want to move outside the major banking groups, our ethical banks guide compares ownership and lending policies. We can help you compare the home loans too, including rates, fees and features.
How Suncorp lent before October 2026
These are the lending rules we checked in September 2026. We have kept them together to explain existing loans and applications already underway. New ANZ applications follow ANZ’s own rules.
- 01 / YOUR SAVINGS
Multiple offset accounts
Eligible Standard Variable loans let borrowers offset savings in a main account and up to 9 sub-accounts.
- 02 / YOUR PROFESSION
The medical LMI waiver
Eligible doctors could borrow up to 90% without paying lenders mortgage insurance (LMI).
- 03 / YOUR BUILD
Construction and owner-builders
Suncorp had an option for registered builders who had already completed at least 1 owner-builder home.
How Suncorp’s LMI waiver worked for doctors
When we checked in September, eligible doctors could borrow up to 90% without paying LMI. At least 1 borrower needed current general or specialist registration with the Australian Health Practitioner Regulation Agency (AHPRA).
Provisional, limited and non-practising AHPRA registration did not qualify for the reviewed medical waiver.
Loan-to-value ratio (LVR) is the loan as a percentage of the property value. A 90% LVR means borrowing $90 for every $100 of property value. You still need money for any buying costs.
Doctor LMI waiver rules checked in September 2026
Scroll to see more columns
| Requirement | Who or what qualified | Limits to check |
|---|---|---|
| Profession | Eligible doctors could qualify | Dentists, pharmacists and allied health professionals were excluded |
| Amount borrowed | Above 80% and up to 90% of the property value without LMI | The loan had to be at least $250k. Total borrowing under the offer was capped at $1.5m. |
| Property use | A home to live in or a residential investment property | Building, bridging finance and refinancing an existing Suncorp loan were excluded. |
| Repayments | Repayments had to cover both principal and interest | Interest-only loans were excluded |
| Borrower name | Borrowing in your own name | Loans in a company or trust name were excluded |
- Who or what qualified
- Eligible doctors could qualify
- Limits to check
- Dentists, pharmacists and allied health professionals were excluded
- Who or what qualified
- Above 80% and up to 90% of the property value without LMI
- Limits to check
- The loan had to be at least $250k. Total borrowing under the offer was capped at $1.5m.
- Who or what qualified
- A home to live in or a residential investment property
- Limits to check
- Building, bridging finance and refinancing an existing Suncorp loan were excluded.
- Who or what qualified
- Repayments had to cover both principal and interest
- Limits to check
- Interest-only loans were excluded
- Who or what qualified
- Borrowing in your own name
- Limits to check
- Loans in a company or trust name were excluded
Compare the professions and limits in our Westpac and NAB reviews. Our LMI waiver guide covers the wider options.
How much could you borrow with Suncorp?
When we checked in September, eligible buyers could borrow up to 95% of the value of a home they planned to live in. Repayments had to cover both principal and interest. Any LMI and applicable fees added to the loan also counted towards that 95% limit.
Suncorp was not on the 5% Deposit Scheme lender list when we checked on 4 September 2026. Its standard 95% loan could still require LMI.
Suncorp borrowing limits checked in September 2026
Scroll to see more columns
| Loan purpose | General maximum | What to check |
|---|---|---|
| Home purchase, principal and interest | Up to 95% | Location cap, property and LMI rules |
| Home purchase, interest only | Up to 90% | Separate interest-only assessment |
| Construction | Up to 90% | Completed value, contract and build rules |
| Investment purchase or refinance | Up to 90% | Product, property and repayment type |
| Medical waiver | Above 80% to 90% | Eligible doctors and purchase/refinance rules |
| Extra cash | Up to 90% | If borrowing above 80%, no more than $100k could be taken as extra cash |
- General maximum
- Up to 95%
- What to check
- Location cap, property and LMI rules
- General maximum
- Up to 90%
- What to check
- Separate interest-only assessment
- General maximum
- Up to 90%
- What to check
- Completed value, contract and build rules
- General maximum
- Up to 90%
- What to check
- Product, property and repayment type
- General maximum
- Above 80% to 90%
- What to check
- Eligible doctors and purchase/refinance rules
- General maximum
- Up to 90%
- What to check
- If borrowing above 80%, no more than $100k could be taken as extra cash
A gift may count as genuine savings
For loans above 90% of the property value, Suncorp generally required savings of at least 5%, built up or held for 3 months. A gift you did not have to repay, inheritance, money from selling an asset, eligible super funds, an ATO refund or a bonus could count. You might also need to show 3 months of rent paid on time.
How Suncorp assessed income
The table below shows how Suncorp treated each income type in the policy we reviewed in September.
Suncorp income rules checked in September 2026
Scroll to see more columns
| Income | How much could count | Work history or evidence needed |
|---|---|---|
| Permanent salary | May use 100% | 3 months and probation finished, or 12 months in a similar role |
| Casual income | May use 100% | 6 months, or 12 months in a similar role |
| Second job | May use 100% | 12 months continuously |
| Essential-service overtime and allowances | May use 100% when regular | Evidence it is ongoing |
| Other overtime, allowances and commission | Generally uses 80% | At least 6 months |
| Bonus | Generally uses 80% | Usually a 2-year history |
| Rental income | Generally uses 75% | Lease, statement or valuation evidence |
- How much could count
- May use 100%
- Work history or evidence needed
- 3 months and probation finished, or 12 months in a similar role
- How much could count
- May use 100%
- Work history or evidence needed
- 6 months, or 12 months in a similar role
- How much could count
- May use 100%
- Work history or evidence needed
- 12 months continuously
- How much could count
- May use 100% when regular
- Work history or evidence needed
- Evidence it is ongoing
- How much could count
- Generally uses 80%
- Work history or evidence needed
- At least 6 months
- How much could count
- Generally uses 80%
- Work history or evidence needed
- Usually a 2-year history
- How much could count
- Generally uses 75%
- Work history or evidence needed
- Lease, statement or valuation evidence
Self-employed borrowers: Basic or Comprehensive
Basic
This option used 2 years of tax records and fewer business documents. You generally needed to borrow in your own name, have a business trading for 2 years and borrow no more than 80% of the property value. Your income could not have fallen sharply.
Comprehensive
If you did not meet the Basic rules, Suncorp needed full tax returns and financial statements. This also applied to loans in a company or trust name.
Read our self-employed loan guide and compare ANZ if you need a lender that assesses your business income differently.
Why Suncorp would not use all 3 incomes
A pharmacist we worked with had 3 employers and averaged about 50 hours a week. Suncorp declined the application twice because it was not satisfied all 3 incomes could be relied on for the loan term.
For an application like this, I’d check how long the borrower had held each job and whether they could keep working those hours. Suncorp generally wanted 12 months of second-job income. Its rules did not say that working 50 hours automatically ruled someone out. Another lender may assess the same income differently.
Construction loans and property restrictions
In September, Suncorp accepted standard homes, units and some acreage. It also offered construction loans and an option for some owner-builders. If your loan or application is already underway, ask how the move affects your build before agreeing to changes or counting on more loan funds.
- 01 / APARTMENTS
Apartments generally needed at least 40 sqm
Balconies, parking and storage did not count towards the size. The apartment also needed a separate bedroom.
- 02 / STUDIOS
No Queensland studios
The September rules only accepted studios in specified Sydney locations, generally with borrowing at 80% of the value or less.
- 03 / CONSTRUCTION
Up to 90% for an eligible build
The 90% limit used the completed home’s value and included LMI. The bank paid the loan out in stages, with interest charged on the money used.
What Suncorp needed for a construction loan
- A single home, duplex or simple 2-lot project could qualify. Larger developments needed a different type of loan.
- A standard build needed a licensed builder and a genuine building contract. The bank also had rules for plans, progress payments, valuations and the time allowed to finish.
- Owner-builders could borrow up to 70% if they met the rules. They had to be registered builders in the state and have completed at least 1 owner-builder home. Suncorp also needed detailed plans and quotes, and evidence they could afford the loan.
- For a small renovation, you could sometimes borrow against the equity already in your home. This could be simpler if the bank did not need the renovation to increase the property value enough to support the loan.
Our construction loan guide explains progress payments and the documents needed for a build.
Properties that often need another lender
Suncorp’s usual rules excluded serviced apartments, dual-key properties, company-title or stratum-title units, commercial properties financed with a home loan, and split-contract developments.
Our apartment loan guide covers how size and building use affect lending.
Borrowers and properties outside the earlier rules
Suncorp lending limits checked in September 2026
Scroll to see more columns
| Your situation | Suncorp’s position | What we would do |
|---|---|---|
| Buying before selling | Suncorp did not offer bridging finance | Compare lenders that offer a loan to buy before you sell |
| Using parents’ property | No family equity guarantee | Check what your parents would guarantee and how they could be released later |
| Recent late payments | Suncorp had strict rules on recent missed payments | Review the credit report before applying |
| Temporary visa | Suncorp’s standard rules did not cover temporary residents | Use a lender that accepts the visa and income |
| Australian expat | Suncorp had tighter borrowing limits for citizens living overseas | Check the currency, income type and 30% deposit |
- Suncorp’s position
- Suncorp did not offer bridging finance
- What we would do
- Compare lenders that offer a loan to buy before you sell
- Suncorp’s position
- No family equity guarantee
- What we would do
- Check what your parents would guarantee and how they could be released later
- Suncorp’s position
- Suncorp had strict rules on recent missed payments
- What we would do
- Review the credit report before applying
- Suncorp’s position
- Suncorp’s standard rules did not cover temporary residents
- What we would do
- Use a lender that accepts the visa and income
- Suncorp’s position
- Suncorp had tighter borrowing limits for citizens living overseas
- What we would do
- Check the currency, income type and 30% deposit
Suncorp allowed some guarantees for spouses, companies and trusts. These were separate from a family guarantee using a parent’s property to help with a deposit.
Australian citizens living overseas could be considered up to 70% of the property value. Only part of eligible overseas personal income could count. Overseas business income was excluded.
Its standard credit rules allowed no more than 1 late repayment in the previous 12 months, and that payment could be no more than 29 days late. Small, paid utility or phone defaults could be accepted within its limits.
Looking to borrow through your SMSF to buy a residential property? The rules changed on 10 August 2026: new residential SMSF borrowing is generally banned. Existing loans, qualifying refinances and purchases agreed under binding contracts before that date have exceptions. Our AMP review explains the residential SMSF changes in more detail.
Earlier Suncorp products, features and fees
Suncorp features and fees before the move. Check your ANZ notice for changes.
Scroll to see more columns
| Option | What you get | Main catch |
|---|---|---|
| Standard Variable | Offset through Everyday Options, redraw and unlimited extra repayments | Outside Home Package Plus: $600 establishment fee ($990 at 90% LVR or more), $10 a month and a $75 one-off offset fee |
| Back to Basics | Simple variable loan, redraw and no annual or monthly loan fee | No offset |
| Fixed Rate | 1, 2, 3 or 5-year terms | No offset or redraw during the fixed term. Break costs may apply. |
| Home Package Plus | Packages eligible Standard Variable and fixed loans | The standard annual fee is $375. The offer we checked refunded it on eligible new loans of $150k or more. Check your loan documents and the notice about your move. |
| Better Together offer | Discount on eligible Back to Basics loans linked with an Everyday Options account | The account does not turn Back to Basics into an offset loan |
- What you get
- Offset through Everyday Options, redraw and unlimited extra repayments
- Main catch
- Outside Home Package Plus: $600 establishment fee ($990 at 90% LVR or more), $10 a month and a $75 one-off offset fee
- What you get
- Simple variable loan, redraw and no annual or monthly loan fee
- Main catch
- No offset
- What you get
- 1, 2, 3 or 5-year terms
- Main catch
- No offset or redraw during the fixed term. Break costs may apply.
- What you get
- Packages eligible Standard Variable and fixed loans
- Main catch
- The standard annual fee is $375. The offer we checked refunded it on eligible new loans of $150k or more. Check your loan documents and the notice about your move.
- What you get
- Discount on eligible Back to Basics loans linked with an Everyday Options account
- Main catch
- The account does not turn Back to Basics into an offset loan
How we compared Suncorp with other lenders
What we compared under Suncorp’s September lending rules
Scroll to see more columns
| If you need… | Earlier Suncorp rules | What we would compare |
|---|---|---|
| An LMI waiver for your profession | Doctors only | A lender that also includes dentists, allied health or other professions |
| Separate savings accounts that reduce loan interest | Up to 9 savings buckets could offset an eligible loan. | A lender that offers multiple offset accounts and lets you link them to the loan or loan splits you need |
| A family guarantee | Not available | A lender with clear rules about what your guarantor is responsible for and when they can be released |
| Bridging finance | Not available | A lender that can add bridging interest to the loan or assess repayments using the debt left after you sell |
| A Queensland studio | Not accepted | A lender that accepts the exact size, postcode and property type |
| A quicker decision on a complex self-employed application | The September estimate was up to 20 business days after all documents were received. Ask for the timing of your application now. | A lender that accepts your income records and can meet your finance deadline |
- Earlier Suncorp rules
- Doctors only
- What we would compare
- A lender that also includes dentists, allied health or other professions
- Earlier Suncorp rules
- Up to 9 savings buckets could offset an eligible loan.
- What we would compare
- A lender that offers multiple offset accounts and lets you link them to the loan or loan splits you need
- Earlier Suncorp rules
- Not available
- What we would compare
- A lender with clear rules about what your guarantor is responsible for and when they can be released
- Earlier Suncorp rules
- Not available
- What we would compare
- A lender that can add bridging interest to the loan or assess repayments using the debt left after you sell
- Earlier Suncorp rules
- Not accepted
- What we would compare
- A lender that accepts the exact size, postcode and property type
- Earlier Suncorp rules
- The September estimate was up to 20 business days after all documents were received. Ask for the timing of your application now.
- What we would compare
- A lender that accepts your income records and can meet your finance deadline
Hunter Galloway lender rating
Our earlier Suncorp broker score
We gave Suncorp 7.1/10 in our September 2026 review. This score covers its earlier loan features and lending rules. It does not rate the ANZ loan you’ll move to.
7.1/10
Useful offsets, doctor waiver and construction options
Score breakdown
Each category is scored out of 10
- Lending flexibilityOptions for some borrowers, with strict credit and visa rules6.5/10
- Borrowing capacityCould count regular income and essential-service overtime7.0/10
- Property acceptanceOptions for building, with limits on studios and unusual units7.5/10
- Products and featuresUp to 9 savings buckets could reduce loan interest7.5/10
- Speed and certaintyShorter waits for simple applications. Longer waits for complex ones.6.5/10
- Pricing and serviceThe LMI waiver or package offer could reduce costs7.5/10
Experience and sources
How this guide was checked
Updated 14 October 2026. We checked the repayment examples, redraw options and interest-only explanation against Suncorp Bank’s public repayment guidance and a customer migration email. The email also confirms that existing financial assistance arrangements continue as agreed.
On 13 October 2026, we checked Suncorp and ANZ’s public migration guidance for repayments, offset accounts, redraw and construction loans, along with the closure to new applications.
The detailed lending rules and assessment-time examples come from our September review. Their original check dates are listed below. They have not all been rechecked for this update.
The minimum repayment guidance confirms at least 30 days’ notice of the new amount and that using redraw after the move does not recalculate it.
Joshua has worked in mortgage broking since 2011 and holds Diploma and Certificate IV qualifications in finance and mortgage broking.
Sources and check dates
- Suncorp Bank Move Hub: customer support. Checked 13 October 2026.
- Suncorp Bank: new applications closed and pre-approvals expired. Checked 13 October 2026.
- Suncorp: construction loan changes. Checked 13 October 2026.
- Suncorp: loans in a company name. Checked 13 October 2026.
- Suncorp: loans with no outstanding balance. Checked 13 October 2026.
- Suncorp: offset account changes. Checked 13 October 2026.
- Suncorp: estimated repayment calculator. Checked 13 October 2026.
- Suncorp Bank: repayment examples, minimum repayment changes and options. Checked 14 October 2026.
- Suncorp Bank customer email: An important update about your home loan. Reviewed 14 October 2026.
- ANZ: home loan migration timing. Checked 13 October 2026.
- Earlier policy checks: detailed lending policy checked 4 September 2026. The following sources retain their original check dates.
- Suncorp Bank Move Hub: changes to home loans. Checked 13 October 2026.
- Suncorp Bank mortgage offset and sub-account guidance. Checked 11 September 2026
- Suncorp Bank Everyday Options and 9 sub-accounts. Checked 7 September 2026
- Suncorp Bank home loan offers and medical practitioner waiver. Checked 11 September 2026. Page since removed.
- Suncorp Bank construction loan process. Checked 7 September 2026. Page since removed.
- Australian Government 5% Deposit Scheme: ANZ on the participating-lender list. Checked 13 October 2026.
- ANZ CEO Nuno Matos: half-year results investor briefing remarks, May 2026. Checked 7 September 2026.
- Residential SMSF borrowing changes: Schedule 5, effective 10 August 2026. Checked 8 September 2026
- Suncorp home loan assessment times: historical snapshot checked 11 September 2026.
- Suncorp Bank: responsible banking exclusions. Checked 13 October 2026.
- ANZ: 2025 Energy Customer Approach. Checked 13 October 2026.
- Suncorp Bank’s official home loan notice, saved 2 October 2026, confirmed new applications would close from 7 October 2026. The current page confirms closure and the 4 October pre-approval expiry.
- Broker Daily: 2 October 2026 report of Suncorp Bank’s application cut-offs, including final approval and loan documents by 27 October 2026 and settlement by 26 December 2026. Checked 14 October 2026.
Rates, fees, offers and lending requirements can change.
How are we paid?
The lender pays us commission, which we disclose before you proceed. We compare more than 30 lenders and must put your interests first. Our Brisbane mortgage brokers can review your existing Suncorp loan or compare lenders accepting new applications.
More help with your home loan
LMI waivers
Compare professions, deposits and lender rules.
Read guideSelf-employed home loans
Compare income records and lender options.
Read guideGuarantor home loans
Understand the family arrangement and risks.
Read guideOffset accounts
Work out how an offset could help.
Read guide5% Deposit Scheme
Check eligibility and participating lenders.
Read guideBridging loans
Plan buying before selling.
Read guide
Suncorp to ANZ and refinancing FAQs
Should you stay with ANZ or refinance?
Tell us what you want to keep in your home loan. We’ll compare your proposed ANZ loan with suitable refinance options, including repayments, offset accounts and fees. We’ll also check the cost of switching so you can decide whether moving lenders is worth it.
or call 1300 088 065
Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328.
Client examples are based on real situations. Names and identifying details have been changed.