

An offset account lets your savings reduce your home loan interest while you keep the money in a separate bank account. Whether it is worth paying for comes down to your usual balance, the loan's interest rate and its fees.
The first thing I ask is how much usually sits in the account once the bills, holidays and other planned spending are paid. Having $50k in there on settlement day won't give you a full year of savings if most of it goes on renovations next month.
If you’re considering a new loan for its offset features, our refinancing guide explains how to compare the rate, fees and switching costs.
How does an offset account work?
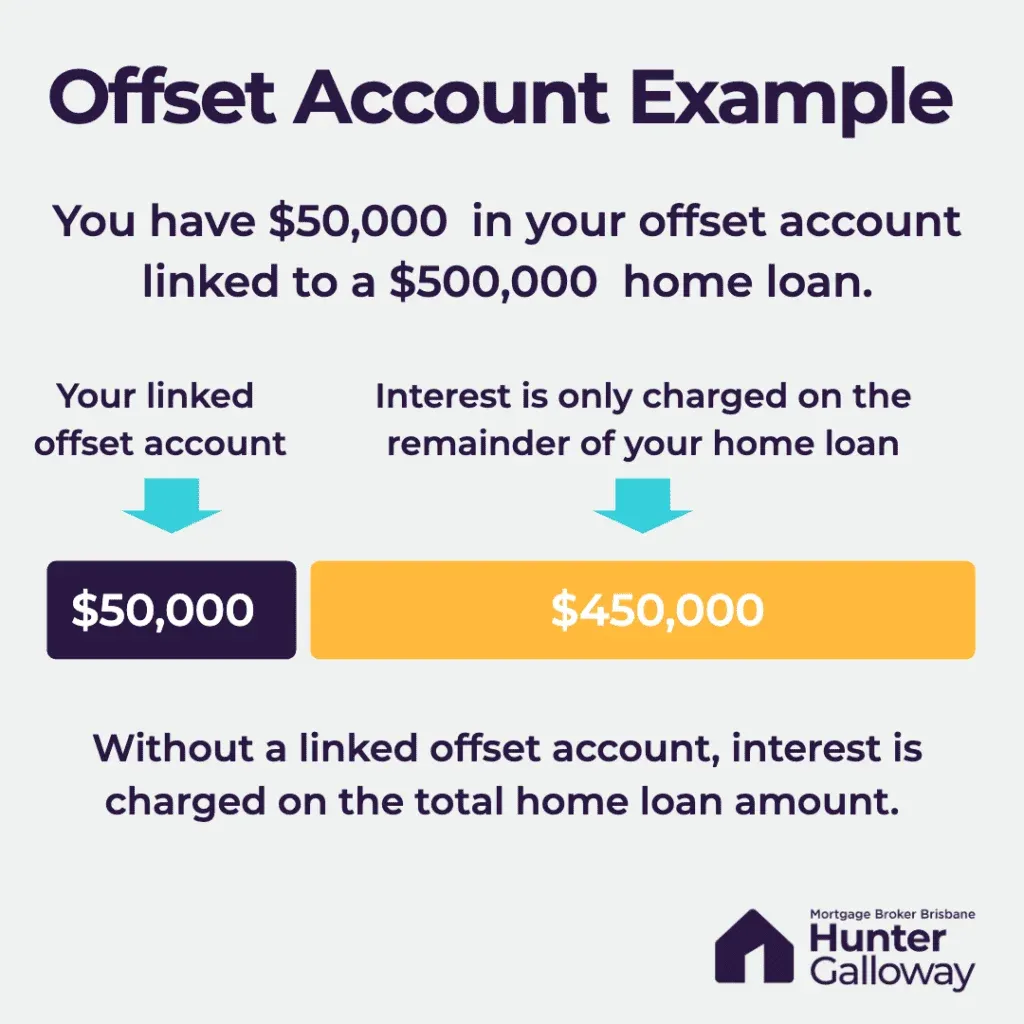
With a 100% offset, a $400,000 home loan and $20,000 in the linked account means interest is calculated on $380,000. You still owe $400,000. The money in the offset has not repaid the loan.
Most lenders work out interest daily, so a deposit starts saving you money once it's counted in that day's balance. A withdrawal reduces the saving from then on. With most bank offsets, your pay can go in, bills come out and you can use a debit card. Access features vary by lender. Westpac explains this daily calculation.
On a principal and interest loan, the scheduled repayment usually stays the same. Less interest means more of that repayment goes towards the debt, which can shorten the loan term if you maintain the benefit. An offset does not lock in your rate or prevent repayments rising when a variable rate increases.
The first diagram shows a full offset on a $500,000 loan: $50,000 in the offset account leaves $450,000 attracting interest.
Watch: offset accounts explained
Full offset vs partial offset
The comparison below uses a $400,000 loan and $20,000 in offset savings. A 100% offset leaves $380,000 attracting interest. With a 50% partial offset, only $10,000 of those savings counts, leaving $390,000 attracting interest.
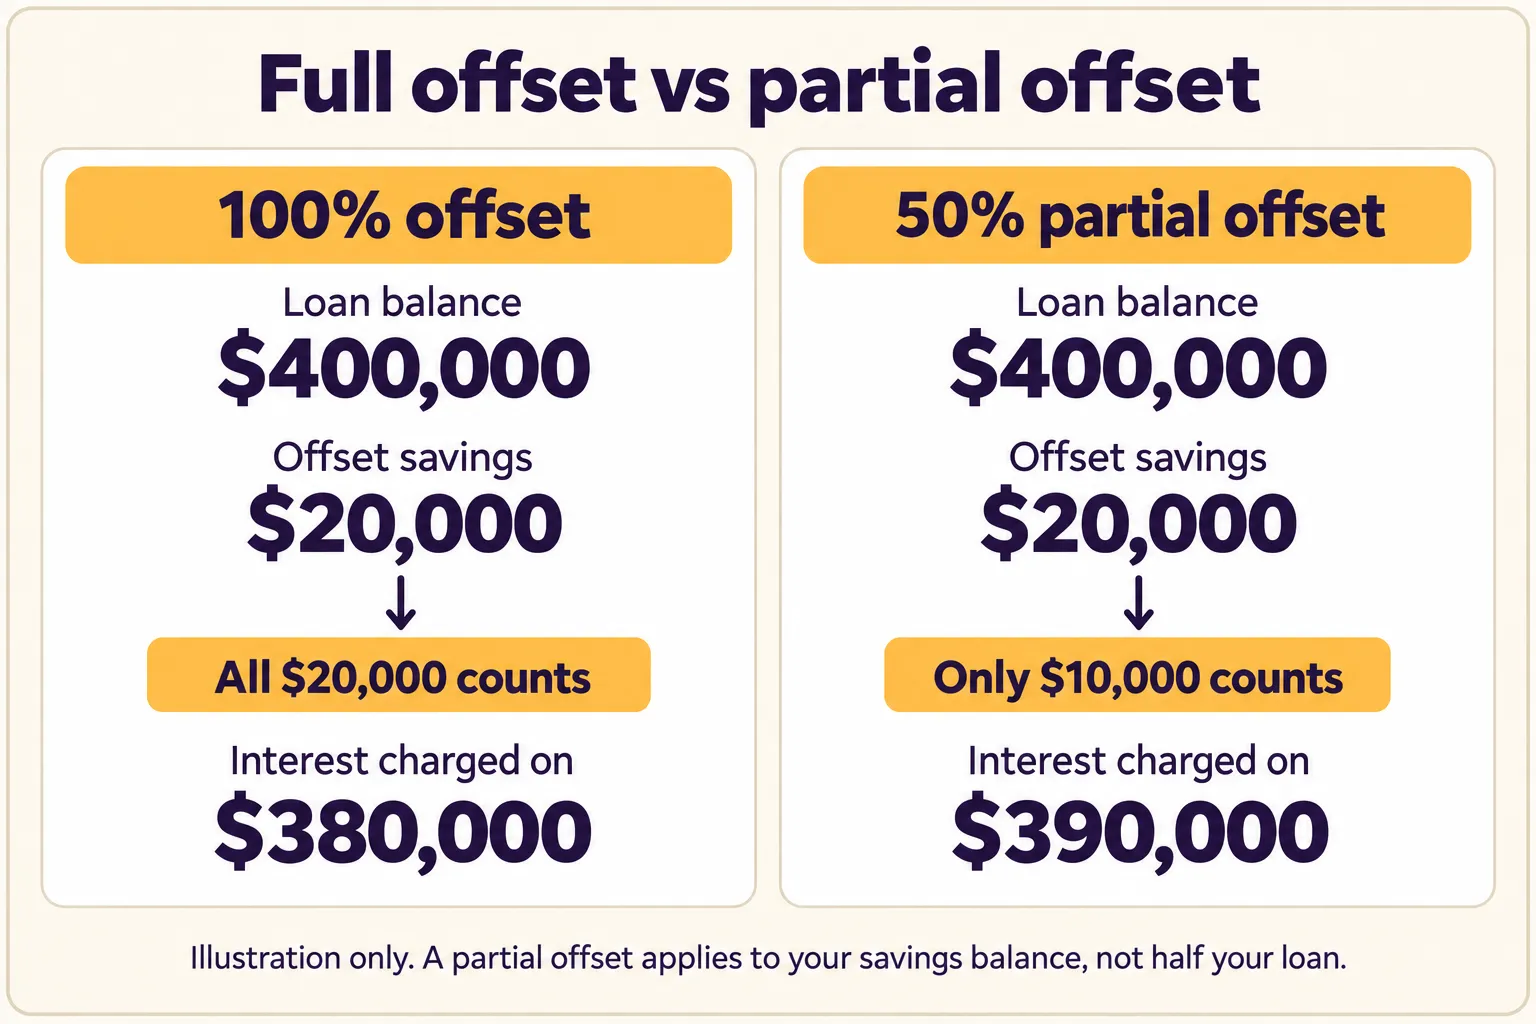
Example only. With a 50% partial offset, half your savings balance counts. Check the product terms for the offset percentage and which loan it's linked to.
Can you have more than 1 offset account?
Some lenders let you link several offset accounts to the one loan. Macquarie, NAB and Westpac, for example, allow up to 10 on eligible loans. I like this for people who already split their pay into buckets: bills, holidays and emergencies each get their own account, and all of it still works against the loan.
It won't save you extra interest. With a 100% offset on the same loan, $50k spread across 5 accounts saves the same as $50k in 1. What you get is a clearer view of which money is already spoken for.
Our multiple offset accounts guide compares which banks offer them, how many accounts you can have and the fees to check. It also includes real client examples of keeping personal and shared savings separate. If you like budgeting with buckets, read our Barefoot Investor bank accounts guide.
Offset versus redraw: what is the difference?
Both can reduce interest. Money in an offset stays in a separate deposit account. Extra repayments reduce your actual loan balance. Redraw lets you borrow eligible extra repayments back, within your loan's rules. ANZ explains the distinction.
Offset account comparison
Scroll to see more columns
| What to compare | Offset account | Redraw facility |
|---|---|---|
| Where the money sits | Separate account linked to the loan | Extra repayments already paid into the loan |
| Interest benefit | Eligible balance reduces the amount charged interest | Reduced loan principal continues saving interest until money is redrawn |
| Access | Usually everyday banking access, subject to account terms | Available amount, minimum withdrawals and restrictions depend on the lender |
| Extra cost | May involve a higher loan rate, package fee or monthly fee | May be included in a cheaper loan; check redraw fees and conditions |
| If the home becomes a rental | Withdrawing savings is different from borrowing again | The use of redrawn funds can affect interest deductibility |
| Day-to-day use | Can suit salary, bills and accessible savings | Can suit extra repayments you do not need for everyday transactions |
- Offset account
- Separate account linked to the loan
- Redraw facility
- Extra repayments already paid into the loan
- Offset account
- Eligible balance reduces the amount charged interest
- Redraw facility
- Reduced loan principal continues saving interest until money is redrawn
- Offset account
- Usually everyday banking access, subject to account terms
- Redraw facility
- Available amount, minimum withdrawals and restrictions depend on the lender
- Offset account
- May involve a higher loan rate, package fee or monthly fee
- Redraw facility
- May be included in a cheaper loan; check redraw fees and conditions
- Offset account
- Withdrawing savings is different from borrowing again
- Redraw facility
- The use of redrawn funds can affect interest deductibility
- Offset account
- Can suit salary, bills and accessible savings
- Redraw facility
- Can suit extra repayments you do not need for everyday transactions
At the same rate, $20,000 in a full offset and a $20,000 extra loan repayment initially reduce the interest calculation by the same amount. The distinction is access, cost and how the money is treated, including for tax.
Redraw isn't always instant, and it isn't always a formal application either. It depends on the lender. For example, NAB publishes minimum redraw and eligibility conditions, while ANZ explains that a redraw increases the debt again. If you're counting on redraw for an urgent bill, I'd check your contract first.
How much interest could you save?
Use this starting estimate: average offset balance × annual loan interest rate. It estimates the direct interest reduction before fees, while the loan balance remains above the amount offset.
These examples assume a 6% loan rate and a 100% offset. That's an assumed rate, not a current lender offer.
Offset account comparison
Scroll to see more columns
| Average offset balance | Approximate direct interest saving over 1 year | Monthly equivalent |
|---|---|---|
| $5,000 | $300 | $25 |
| $20,000 | $1,200 | $100 |
| $50,000 | $3,000 | $250 |
| $100,000 | $6,000 | $500 |
The monthly column is an annual average, not the saving for each calendar month. Rates, daily balances and month lengths affect the actual result. These figures exclude fees, tax effects and the additional interest benefit as repayments reduce the debt faster.
A worked example with money coming and going
Suppose your home loan is $400,000 at 6%, with $50,000 in a full offset. Holding both balances unchanged for 30 days gives this comparison, using a 365-day year:
Offset account comparison
Scroll to see more columns
| Calculation | Interest for 30 days |
|---|---|
| Without offset: $400,000 × 6% × 30 ÷ 365 | $1,973 |
| With offset: $350,000 × 6% × 30 ÷ 365 | $1,726 |
| Direct interest saved | $247 |
Now suppose you keep $50,000 there for 15 days, then withdraw $30,000 and keep $20,000 for the next 15 days. Your average offset balance is $35,000, and the direct saving falls to about $173 for the 30 days. Dollar amounts are rounded.
Making more deposits does not create an extra reward by itself. The balance available each day determines the saving. A steady $50,000 can save more than frequent deposits into an account that is usually almost empty.
What about savings over 5 or 20 years?
At a constant 6%, $50,000 held in offset produces $3,000 in direct annual interest savings while the eligible loan balance remains at least $50,000. Multiplying that by 20 gives $60,000, but that is not a reliable forecast of total savings or years taken off a loan.
To work out the saving over 5 or 20 years, I need your loan balance, the years left, your repayment, the balance you expect to keep and a rate assumption. The saving also stops growing once the offset covers the whole loan. Use our extra repayments calculator to explore paying down debt, and ask us to model an offset separately with your expected cash balance.
What fees should you compare?
Ask for the total cost of an offset loan and a comparable loan without offset. Check the annual package fee, monthly account or offset fee, and any difference in the loan interest rate. Include switching costs if you need to refinance to get the feature.
Some lenders charge a monthly fee for each offset instead of a package fee. Bankwest's Simple Home Loan, for example, charges $10 a month per offset account. That's one product, not a rule for every loan from that lender, so I go by the terms on the actual loan you're looking at.
The balance needed to cover a fee
If the offset adds $120 a year and both loans have the same 6% rate, the fee-only break-even balance is $120 ÷ 6% = $2,000. Keep an average $5,000 there and the estimated direct saving is $300, leaving $180 after that extra fee.
That comparison assumes your cash would otherwise earn nothing. If it could earn savings interest, include that alternative after tax.
A higher loan rate can matter more than the fee
Assume a $400,000 loan without offset costs 5.80%, while an offset loan costs 6.00% plus an extra $120 a year. The difference is 0.20 percentage points. These are hypothetical offers with otherwise matching terms.
Offset account comparison
Scroll to see more columns
| Option with $20,000 available cash | Approximate annual interest and extra offset fee |
|---|---|
| No offset: $400,000 × 5.80% | $23,200 |
| Offset: ($400,000 − $20,000) × 6.00% + $120 | $22,920 |
| Offset advantage before alternative savings interest | $280 |
The approximate break-even offset balance is ($400,000 × 0.20% + $120) ÷ 6.00% = $15,333. That is much higher than the $2,000 fee-only threshold.
This simplified annual comparison holds balances and rates constant, ignores amortisation and assumes the cash on the no-offset option earns nothing. It does not compare putting that cash into redraw. Have both alternatives calculated before paying more for an offset feature.
What if you might rent out your home later?
If there's a chance you'll turn your home into an investment property, talk to your tax adviser before moving big amounts into the loan or redrawing them. Which property the loan is secured against doesn't decide whether the interest is deductible. Your adviser needs to look at what the borrowed money was used for.
The ATO's redraw ruling treats a redraw as a new borrowing. If you redraw for private spending, interest on that portion may remain private even when the original property is rented out. Mixing investment and private borrowings can mean ongoing apportionment and record-keeping.
An offset withdrawal uses money from a separate account. It does not create the same new borrowing as a redraw, but an offset does not automatically make a loan deductible. Your adviser still needs to check the original borrowing, later transactions and how the property is used.
If interest on an investment loan is deductible, an offset also reduces the interest expense you can claim. You cannot claim the interest you avoided paying. The ATO's offset ruling limits the deduction to eligible interest actually incurred.
Offset versus a savings account
A savings account pays interest, which generally needs to be included in your tax return. A standard offset reduces loan interest instead. For your own home, compare the mortgage interest avoided, less extra loan costs, with savings interest after tax.
As an example, $20k earning 5% in a savings account pays $1k interest a year before tax. At an assumed 32% marginal rate including the Medicare levy, you keep $680. The same $20k in a full offset against a 6% home loan avoids about $1,200 in interest, before any extra fees or higher loan rate.
Those rates and tax assumptions are examples, not a recommendation. For an investment loan, account for the reduced interest deduction as well. Check savings account bonus conditions and withdrawal access before comparing the returns.
Check the offset is actually working
Having a transaction account with your lender doesn't mean it's working as an offset. I'd check the link before leaving savings there. ASIC's July 2026 review found that the most common problem was accounts that had been opened but never linked.
Banks had paid more than $55m in compensation for failures reported between September 2023 and August 2025. ASIC's own example is a $750k loan with an average $50k sitting in an offset that was never linked. That could cost more than $3k in extra interest in a year.
Nathan saw this with one of our clients at a non-major bank. Their offset had been left unlinked for around 4 years. It came to light after ASIC's review, and the bank paid back roughly $5k in interest.
Open your banking app or latest statement and check these 3 things:
- Your offset account is open.
- It is linked to the correct home loan or loan split.
- The money in it is reducing the interest you pay.
If anything is unclear, ask the bank to confirm when the account was linked and how it calculated your interest. Got more than 1 offset? Each one needs its own check, so see our multiple offset accounts guide.
Repeat that check after refinancing, splitting the loan or changing products. MoneySmart warns that a broken or missing link can leave customers paying more interest while their repayments appear unchanged.
Paying your salary into the linked account and leaving bill money there until it is needed can help. You do not need a credit card strategy to use an offset. Only consider one if you can pay the card in full by the due date without overspending. Card interest and fees can outweigh the mortgage saving.
Offset account FAQs
Compare the cost with your own numbers
Send me your loan balance, rate, annual fees and roughly how much usually sits in savings. I'll compare an offset with redraw on your numbers and tell you whether the extra cost is worth it. If the home might become a rental later, tell us now so the loan can be set up alongside your tax adviser's advice.
or call 1300 088 065
We will explain the loan options and any costs before you proceed.
Author and sources
How this guide was checked
Reviewed by Joshua Vecchio on 12 September 2026. Offset fees, links and examples checked 15 October 2026.
The worked examples are hypothetical calculations, not lender offers or client outcomes. Annual examples hold rates and balances constant. The 30-day example uses a 365-day year. Figures are rounded to whole dollars.
Sources
- MoneySmart: mortgage offset accounts
- ANZ: redraw and offset compared
- Westpac: offset calculations and features
- CommBank: eligible offset accounts and charges
- NAB: redraw access conditions
- ANZ: redrawing a home loan
- ATO: TR 2000/2, redraw and interest deductions
- ATO: TR 93/6, offset arrangements
- ASIC: offset account failures, media release 26-173MR
- ASIC: Report 837, Offsets, out of mind
- Bankwest: offset fees
- ASIC: check your mortgage offset account is actually saving you money
General information only. Your circumstances need to be reviewed before a loan recommendation. Ask a registered tax adviser about deductions and any planned investment use.
More help with your home loan
Client examples are based on real situations. Names and identifying details have been changed.