

You've found a place, you've saved a deposit and the lender has quoted LMI on top. Before adding it to the loan, I'd check whether you need to pay it and what it does to your repayments.
Below a 20% deposit, many lenders charge this insurance premium. Paying it can help you buy sooner, but a government scheme, professional waiver or family guarantee might let you buy without it. The useful comparison is what each option costs and how much money you'd have left after the purchase.
- 01 / The upside
It may help you buy sooner
You may be able to purchase without waiting until you have a 20% deposit, provided the lender approves the loan and property.
- 02 / The catch
It protects the lender
If the lender loses money after a forced sale, its insurer may cover the lender and then seek to recover the shortfall from you.
- 03 / The cost
The cost varies by lender
Your loan, deposit, property, lender, insurer and whether you are buying or investing can all change the quote.
What is lenders mortgage insurance?
Lenders mortgage insurance, usually called LMI, covers the lender if your home loan ends in a loss. You usually pay the premium, but it doesn't cover your repayments if you lose your job or become ill.
It's normally charged once when the loan settles. Depending on the lender, you can pay it from your savings or add it to the loan. I'll explain the cash and repayment difference below.
When might you need to pay LMI?
For a purchase, LMI commonly applies when you borrow more than 80% of the property value the lender accepts. That percentage is your loan to value ratio, or LVR.
The lender may use its valuation, the purchase price or the lower of the two. If its valuation comes in below your agreed price, you may need more cash than you expected, or your LMI quote may change.
It can also apply when you refinance with less than 20% equity. The new lender assesses the loan again, and the insurance you've already paid for doesn't transfer across.
Investment loans can have different premiums and borrowing limits. The property type, location and repayment structure can also affect the quote. I'd check the actual property and loan before treating an estimate as part of your final budget.
How much does LMI cost?
There isn't one price every lender charges. The amount you borrow, your deposit, the property and the lender's insurance arrangements all affect the premium.
Start with our LMI calculator. Enter the property value and loan amount to get an estimate. We'll then get the lender's figure for your application and include it in your buying budget.
LMI Calculator
You also need to allow for duty, conveyancing, inspections and other purchase costs. Our buying-cost guide covers the expenses that sit outside your deposit.
A small deposit change can affect the premium
LMI is often priced in bands around borrowing levels such as 85%, 90% and 95%. The cut-offs and premiums vary by lender.
If you're borrowing just over a band, a slightly bigger deposit or a lower purchase price could reduce the insurance cost. Moving from 89.99% to 90.01% of the accepted property value, for example, can cross a pricing boundary.
I'd ask for both quotes before moving more savings into the deposit. A lower premium helps, but you still need money for settlement and the bills that follow.
Adding LMI can put you in a higher interest-rate band
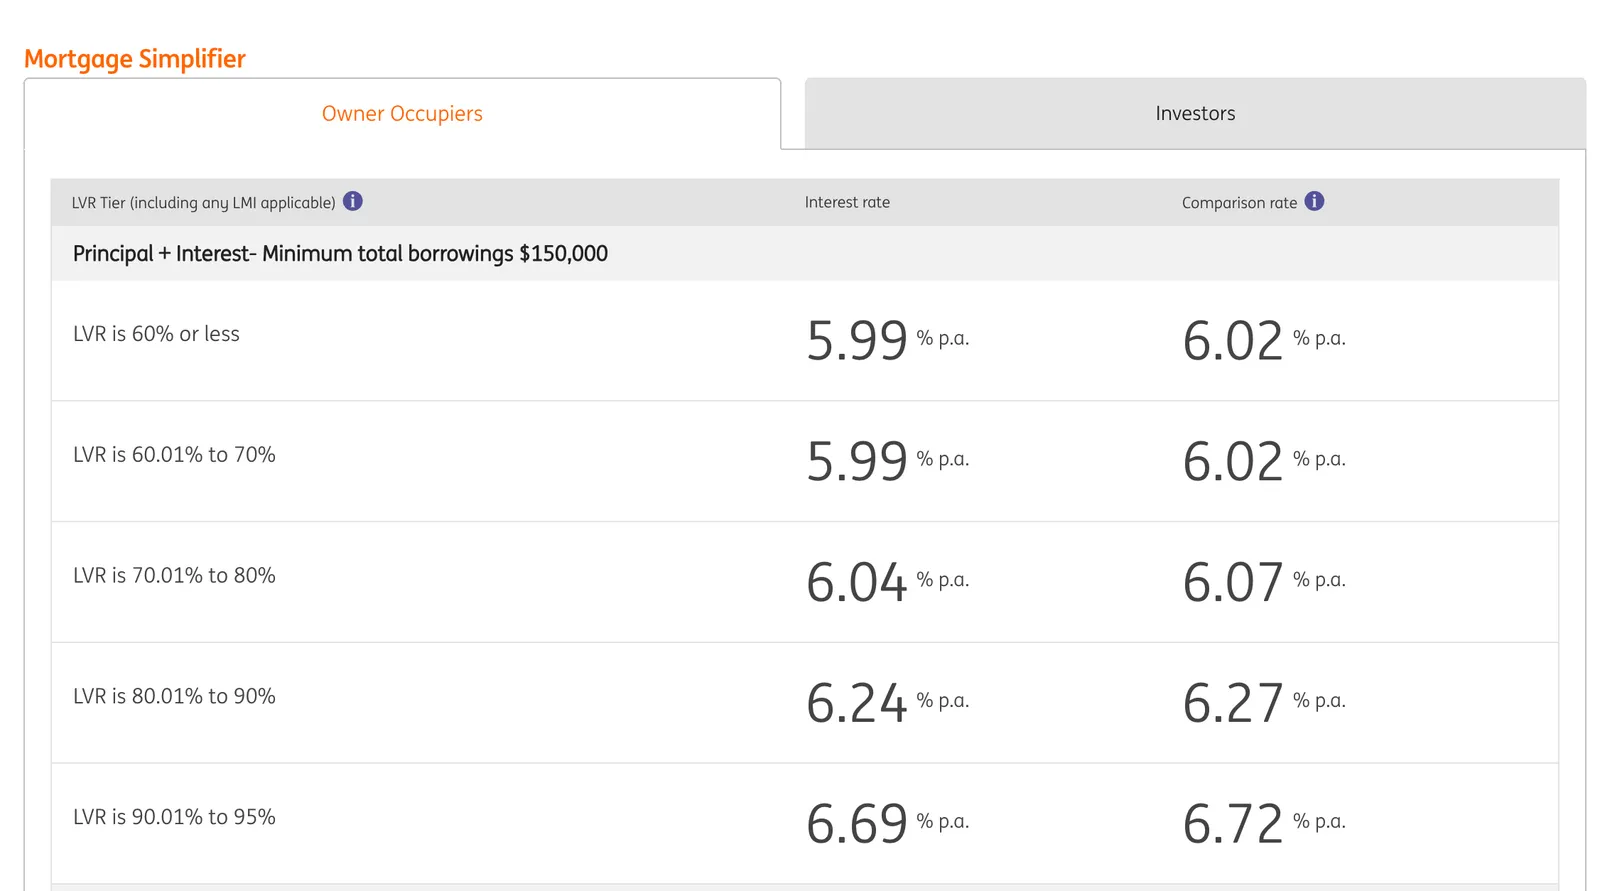
Some lenders also set the interest rate according to how much of the property's value you're borrowing. When they include LMI in that calculation, adding the premium can push the loan into a more expensive band.
One lender we compared includes financed LMI when choosing the rate tier. That means a 10% deposit can leave you above 90% once the premium is added to the loan.
The following recorded comparison shows why I'd check the premium and rate together.
Adding LMI can put you in a higher interest-rate band
Scroll to see more columns
| ING Mortgage Simplifier: loan as a share of the accepted property value, including LMI | Recorded variable interest rate |
|---|---|
| 70.01% to 80% | 6.04% |
| 80.01% to 90% | 6.24% |
| 90.01% to 95% | 6.69% |
Comparison dated 9 September 2026, for a home you live in with repayments covering principal and interest, and new property and borrowings of at least $150k. Rates can change. Check ING's current rates and conditions before using them for your budget.
These are standard loan rates. Government guarantee lending has separate arrangements: the scheme removes LMI for an eligible buyer, while the participating lender still sets the rate and assesses the application. Our ING review explains its loan options.
Compare lender fees as well as LMI
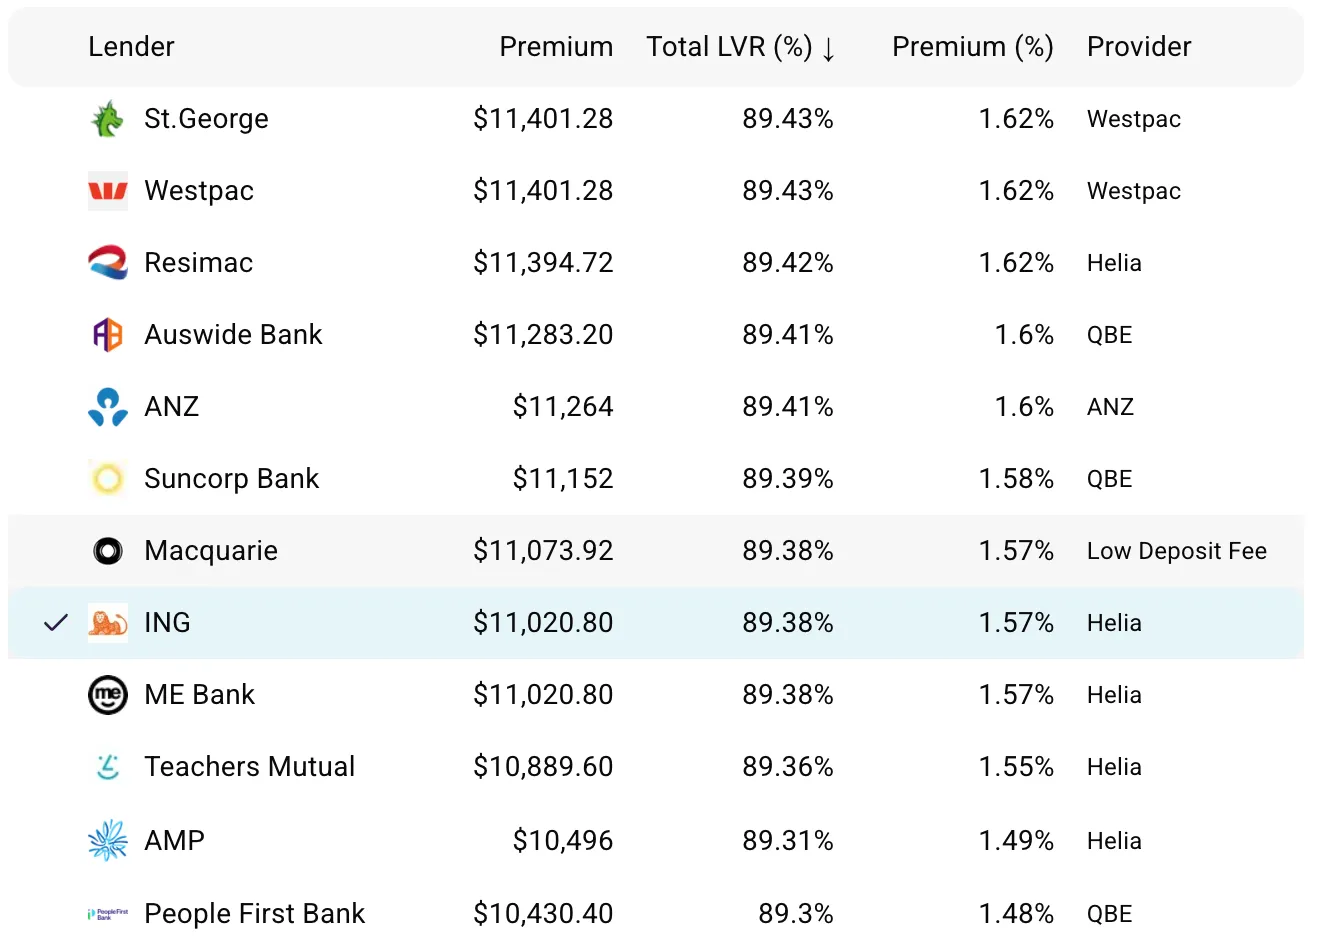
Two lenders can charge different amounts for the same purchase and deposit. Some use Helia or QBE, some have their own insurance arrangements, and some charge a different fee for lending at a higher LVR.
Macquarie, for example, uses a Low Deposit Fee rather than traditional LMI on relevant loans. I'd compare that fee with the competing premium, then check interest rates, ongoing fees and repayments over the same loan term.
A cheaper upfront charge can be outweighed by a higher rate. The loan needs to make sense across the whole comparison.
Can you add LMI to your home loan?
Some lenders allow this if the total loan remains within their limit. You'll sometimes hear it called capitalising LMI.
You need less cash at settlement, but the loan is bigger. You pay interest on the added premium until that part of the balance is repaid, and it may affect your rate band too.
Ask us to compare paying the premium from savings with adding it to the loan. We'll show you the repayment difference and the cash left after settlement. That makes the decision easier than looking at the premium on its own.
Should you pay LMI or keep saving?
I'd compare buying now with waiting, using the same type of property and a realistic savings target. Neither option is automatically cheaper.
Should you pay LMI or keep saving?
Scroll to see more columns
| Your option | What could help | What you need to weigh up |
|---|---|---|
| Buy sooner and pay LMI | You may be able to buy with the deposit you have. | The premium, larger loan, repayments and savings left afterwards. |
| Keep saving towards 20% | You may avoid LMI and borrow less. | Extra rent, the time needed and changes in property prices while you save. |
| Use a waiver, scheme or guarantor | You may be able to buy with a smaller deposit and avoid the premium. | Eligibility, lender choice, property restrictions and any family commitment. |
Waiting can work well if you're close to the deposit you need. Buying sooner may suit if the repayments fit, you've kept a cash buffer and the home meets your plans. I wouldn't rely on a prediction that prices will rise to justify a loan that already stretches your budget.
Let's compare the cost before you commit
Send us your property budget, savings, income and other debts. We'll check ways to avoid LMI and compare the suitable loans. We'll come back with the LMI quote, repayments and cash left after settlement before you sign a purchase contract.
or call 1300 088 065
We’ll explain your options and any costs before you proceed.
Five ways you may be able to avoid LMI
I'd start with the options available using your current savings and circumstances. If none fits, we can compare a larger deposit or family help with paying the premium.
Check the government scheme first
Eligible first home buyers can use the Australian Government 5% Deposit Scheme with a minimum 5% deposit and no LMI. Eligible single parents and legal guardians may qualify with a minimum 2% deposit.
The scheme has no income caps or waitlists. You need a participating lender, an eligible home to live in and a property within the location's price cap. The lender must also approve the loan.
As at September 2026, the cap is $1m for Brisbane, the Gold Coast and Sunshine Coast, and $950k for Melbourne and Geelong. Other areas have different limits, so check the property's postcode using the Government's price-cap information.
Our Westpac review explains how one participating lender offers the scheme alongside its other options for buyers with smaller deposits.
Check whether your profession qualifies for a waiver
Some lenders waive LMI for eligible borrowers in selected professions. Your job is the starting point; registration, income, employment, loan size and property requirements can also apply.
The conditions vary by lender. For example, ANZ's published list includes chiropractors for eligible lending up to 90% of the property's accepted value. That doesn't mean every chiropractor or every application qualifies. ANZ's professional-waiver factsheet sets out the requirements.
For nurses and pharmacists, I'd check the lender's income and registration requirements before assuming a waiver applies. Our nurse home loan guide and LMI waiver guides explain the options by profession.
Compare lenders with other arrangements
A lender may charge a risk fee, insure its own lending or offer a promotion. These options can still involve a higher rate, a different fee or tighter property rules.
I'd compare the complete loan cost before choosing a product because it advertises no LMI. Our lender reviews explain where those differences matter.
Check what reaching 20% would cost you
Borrowing 80% or less of the lender's accepted value will often avoid LMI, although some properties and loans have stricter rules. Allow for buying costs as well as the deposit.
A cash gift from family may help. The lender can ask for a gift letter and evidence that it doesn't need to be repaid. If you're still borrowing a high share of the property's value, genuine savings rules may also apply.
Before committing all your spare cash, compare the insurance saving with what you'd have left for moving, repairs and emergencies.
Consider a family guarantor if that suits everyone involved
A family member may be able to use part of the equity in their property to guarantee your loan. This can reduce or remove LMI and is different from giving you cash for the deposit.
Check exactly how much they're guaranteeing and how the guarantee can be released later. Their property could be at risk if you can't repay, so they should get independent legal and financial advice. Our guarantor loan guide explains the commitment.
Can you get an LMI refund?
Possibly, if you repay and close the loan early. The lender, insurer, timing and policy conditions determine whether there's a refund.
Helia's factsheet outlines partial refunds of 40% when the policy is less than 1 year old and 20% from 1 to 2 years, subject to its conditions. A refund isn't available where you regularly miss payments or default. Your lender needs to confirm whether your policy qualifies and the amount payable.
QBE's guide says some lender arrangements allow a partial refund when the relevant loans are repaid in full and the mortgage is released within 12 months. The lender must notify QBE within 30 days, and other conditions apply.
Ask before paying out or refinancing. Count a refund in your budget only once the lender has confirmed it.
Will refinancing trigger another premium?
It may, even if you've been making repayments for years. A flat or falling property value can leave you with less than 20% equity when the new lender values the home.
I'd compare any new LMI premium, switching fees and the remaining loan term with the interest saving. Extending the term can also increase total interest despite lower monthly repayments. Our refinancing guide covers the full comparison.
What happens if the home sells for less than you owe?
If sale proceeds don't clear the loan and related costs, the unpaid amount is a shortfall. After paying an LMI claim to the lender, the insurer may seek to recover that debt from you.
$855k still owed
Your outstanding loan balance.
$800k after selling costs
The money available to repay the loan.
$55k left owing
Before any extra unpaid interest or recovery costs.
If you're struggling with repayments, contact your lender's hardship team early. You can also get free financial counselling through the National Debt Helpline. If a sale leaves a debt, ask for a breakdown and get advice about your position.
Is LMI tax deductible on an investment property?
For a rental property, the ATO treats LMI charged to the borrower as a borrowing expense. If total borrowing expenses exceed $100, the deduction is generally spread over 5 years or the loan term, whichever is shorter.
Repaying early, refinancing or using part of the loan privately can change the treatment. Keep the loan documents and premium statement and ask your accountant how the ATO borrowing-expense rules apply.
Questions about LMI

Experience and sources
About this guide
Sources are linked beside the relevant information. We compare the LMI premium, interest rate, ongoing fees and cash needed for your purchase.
Joshua Vecchio is a Director and Mortgage Broker at Hunter Galloway and has worked in mortgage broking since 2011. Nathan Vecchio reviews this guide.
Sources
- Australian Government 5% Deposit Scheme
- Australian Government scheme property price caps
- Moneysmart: Switching home loans
- Moneysmart: Going guarantor on a loan
- Moneysmart: Problems paying your mortgage
- ATO: Rental property borrowing expenses
- Helia: LMI factsheet and refunds
- QBE: LMI guide and refunds
- ING: Current home-loan rates
- National Debt Helpline
General information only. Loan approval, pricing, refunds and policy exceptions depend on the lender, insurer and your circumstances. Tax and legal information is not personal advice. When we arrange a loan, the lender generally pays us commission. We explain the lenders we can access, any fees and how we're paid before you proceed.
Related guides and calculators
LMI calculator
Get an initial estimate before asking for a lender quote.
Estimate LMILMI waivers
See which professions may qualify and what conditions apply.
Check professionsGovernment 5% Deposit Scheme
Check the current deposit, property and lender rules.
Read the guideGuarantor home loans
Understand limited guarantees and the risks for family.
Read the guideHome-loan refinancing
Compare the full switching cost, not only the rate.
Read the guide
What home buyers say about us
 Google
“Clear, incredibly responsive and accurate.”
- Google
“Preapprovals done quickly and efficiently.”
- Google
“Reassuring every step of the way.”