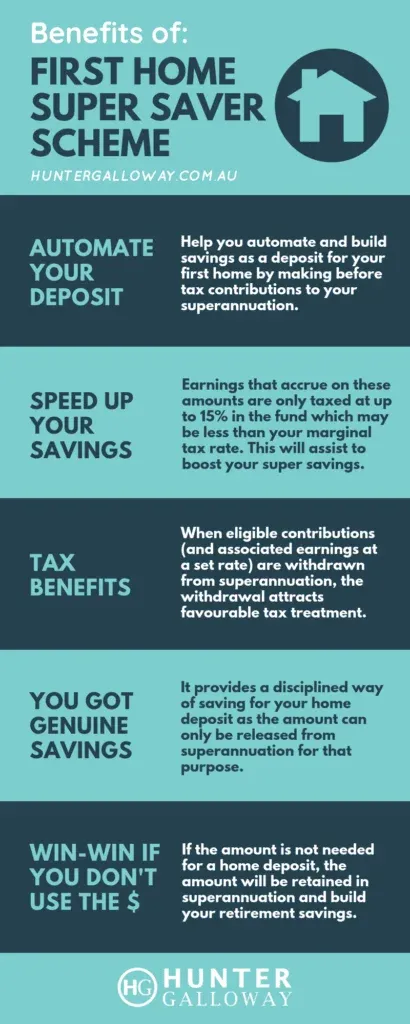
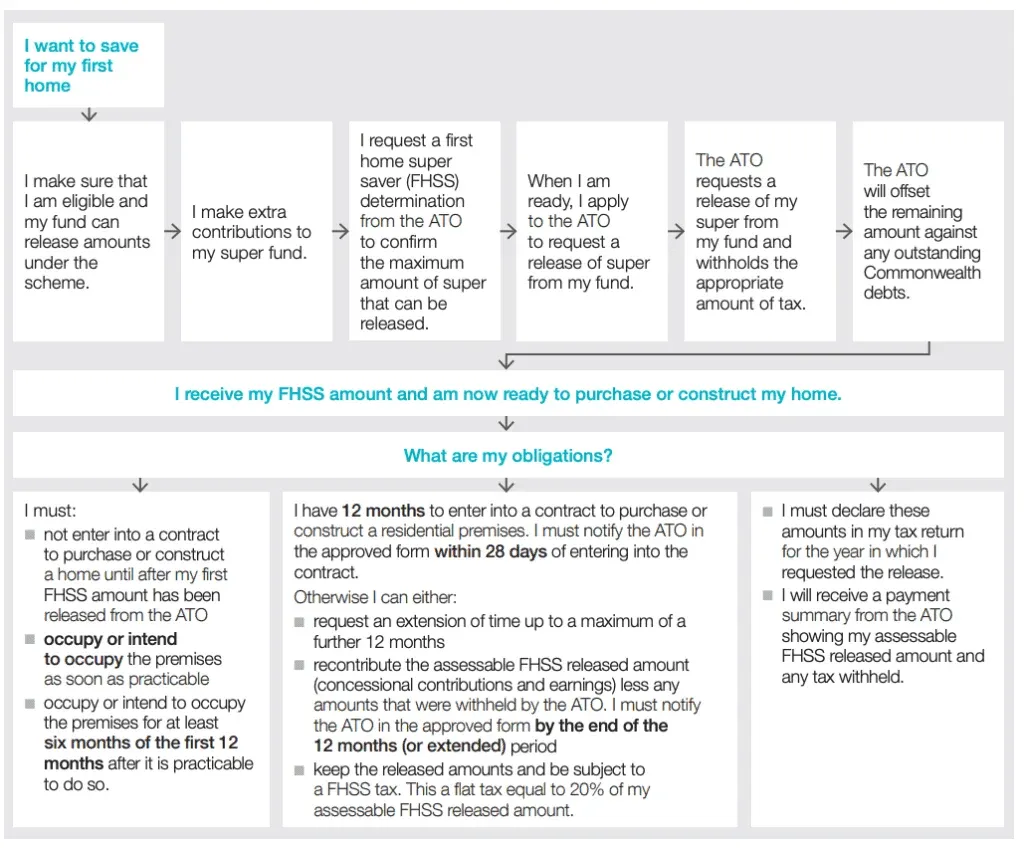
First Home Super Saver Scheme (also known as FHSSS) is a government scheme made to assist you with speeding up the time it takes to save a deposit and buy your first home. You’re probably thinking isn’t super for retirement? It is, but the government lets you dip in early to help with home ownership.
FHSS can release eligible voluntary before-tax and after-tax super contributions to help you buy your first home. The amount released depends on the contribution type, FHSS limits and other scheme rules.
Example:
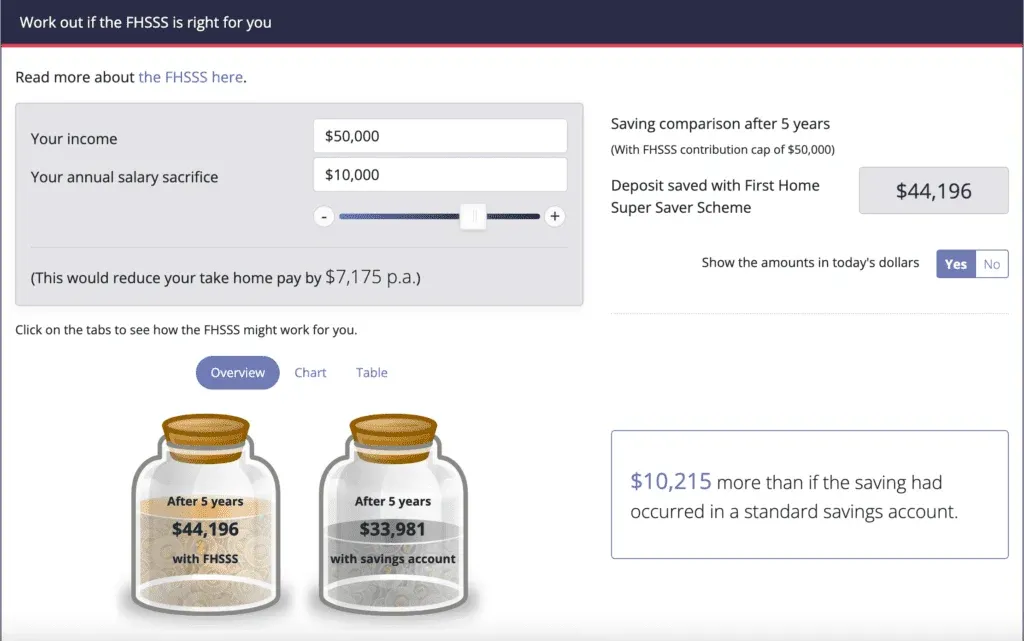
Fiona has been working as a Marketing Associate, makes $50k a year and wants to use the FHSSS to speed up the time it takes to save for her first home purchase. She has never owned a home before and wants to buy a place as soon as possible but has no savings.
Fiona asks her work to take voluntary before-tax contributions of $10k a year from her salary and pay them into her super fund. This works out to roughly $833 per month from her before-tax pay.
This money is being taken before tax, which reduces how much tax she pays per year on her total pay. In effect, her take-home pay only drops by about $7.2k a year, or about $600 a month.
After 5 years, Fiona could have about $50k released for her deposit. If she saved the same take-home pay in a bank account at 4.5% interest, she'd have about $39k, so FHSS puts her about $11k ahead. That assumes 2026-27 tax rates, a deemed SIC rate of about 7.4% for the whole 5 years and bank interest taxed at her marginal rate. Use the calculator in section 7 to run your own numbers.