ANZ calls its home loan pre-approval an Approval in Principle, or AIP. It gives you an amount to work with while you look for a property, subject to ANZ's conditions.
ANZ checks your credit, income, expenses, employment, savings and debts before issuing it. That makes the approval more useful than an online calculator, but it is not the final loan approval.
Timing matters. ANZ says pre-approval generally lasts around 3 months. A broker can request another 3 months, taking the total period to a maximum of 6 months, but the extension is not automatic. ANZ needs updated payslips and current application details before it agrees.
When I review an ANZ pre-approval, I put the process in order: what ANZ has checked now, what can wait until you find a property and what needs to happen before the approval expires.
Policy note: this article was updated on 26 August 2026 using ANZ policy supplied for this review and ANZ's published material. ANZ can change its rules, offers and turnaround times. It still needs to check your final situation and the property before approving the loan.
The short version
- ANZ checks your credit and asks you to show your income, employment, expenses, savings, deposit, debts and identity.
- The initial approval generally lasts around 3 months.
- A broker can request another 3 months, but ANZ needs updated payslips and current details before it agrees.
- The property, valuation, title and any LMI or government scheme conditions may still be outstanding.
- A change in your job, income, debts, deposit or property can make ANZ check the application again.
If you want the wider explanation before comparing banks, start with our guide to home loan pre-approval.

Pre-approval basics
A pre-approval means ANZ may lend you up to a set amount if you meet the conditions in the approval.
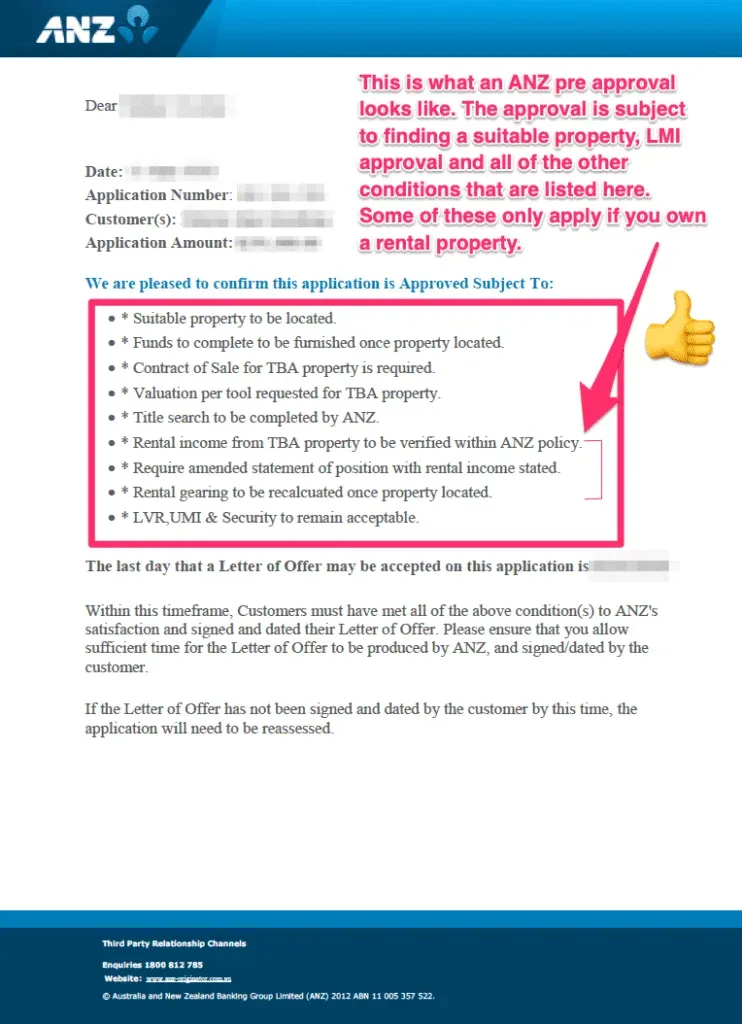
You may see Approval in Principle, conditional approval or Approved Subject To in ANZ's letters. Do not get caught up in the label. Each one means ANZ is comfortable with the application so far, but the loan is not final.
Before I would rely on the approval, I would confirm:
- the approved loan amount
- the expiry date
- what income or debt conditions remain
- whether you still need to pay Lenders Mortgage Insurance
- whether the property is yet to be valued or approved
- whether ANZ still needs to approve a government scheme or guarantor setup
What ANZ checks before giving pre-approval
ANZ checks the application rather than relying on the figures you type into a calculator. It asks you to show your income, expenses, employment, savings, deposit, debts and identity, then completes a credit check.
The important limit is the property. ANZ can approve your finances before it knows whether it will lend against the home you choose.
| At ANZ pre-approval | Before final approval |
|---|---|
| Income, employment and expenses are checked | ANZ must be willing to lend against the chosen property |
| Savings, deposit and current debts are reviewed | ANZ may need a valuation and title search |
| A credit check is completed | LMI or government scheme approval may still be needed |
| You receive a lending limit and a list of conditions | Your income, debts and expenses must still stack up |
Can you bid at auction with ANZ pre-approval?
An ANZ pre-approval gives you a clearer budget, but it is not a promise that every property will be accepted.
Before bidding, check the approval conditions, confirm your deposit and costs, and ask your broker to review the property type and location. Auction contracts are normally unconditional, so you cannot rely on a finance clause if the bank later refuses to lend against the property.
Our Queensland auction guide explains the finance checks to complete before you bid.
Documents needed for ANZ pre-approval
Start with the documents that match how you earn your income. Sending the wrong combination can create extra questions and slow down an otherwise simple application.
PAYG employees
For full-time and part-time PAYG income, ANZ can generally use any one of these options:
- a recent year-to-date payslip covering at least 3 months, dated within 60 days
- two consecutive payslips where the year-to-date figure covers less than 3 months, with the latest dated within 60 days
- 3 months of bank statements or transaction history showing regular salary credits
These are alternatives. You should not automatically need both a payslip and 3 months of salary credits.
ANZ generally wants you to have worked in your current job for at least 3 months. Changing employers can still be okay if the break between jobs was under 28 days. Being on probation does not automatically rule you out.
Client example: a 14-month travel break
I had a client who had been away travelling for 14 months. When she came back, her employment history did not fit ANZ's usual rules.
If you take approved leave and stay employed, ANZ can look at the income you will earn when you return, provided you are due back within 12 months. Her break was longer than that, so this rule did not help her.
The normal job rule did not solve it either. ANZ generally wants 3 months in the current job and only makes an allowance for changing employers when the gap is under 28 days.
Other banks can be more flexible. One major has no set minimum time in the current job. It can check a new job using an employer letter or employment contract, and it also considers people returning after a career break or other extended leave. For someone in her position, that can be easier than waiting 3 months or asking ANZ for an exception.
ANZ can usually use all of your casual income or income from a second job once you have worked there for at least 6 months. Temporary and contract income also usually needs 6 months of history.
If you work for yourself
If you work for yourself, the first step is to work out which documents ANZ will use. ANZ usually looks for:
- at least 18 months of ABN or ACN history
- one year of personal tax returns and the matching Notice of Assessment
- business returns and financial statements where income comes through a company
- two years of financials if LMI applies, unless ANZ agrees to use one year with a reduced income figure
Sole traders may not need separate business financial statements. If you trade through a company, ANZ usually wants the business tax return, profit and loss statement and balance sheet.
Some company directors and shareholders can use ANZ's Company Wages option. If you have received regular wages for at least 6 months and ANZ does not need to adjust the income, it may use a recent payslip and ATO Income Statement instead of tax returns. This option is not available with LMI.
Our self-employed home loan guide explains why the same business income can produce different results across lenders.
How long does ANZ pre-approval take?
ANZ publishes its live broker turnaround times, which move as application volumes change. As a broad guide:
| Broad application type | Current estimate |
|---|---|
| Straightforward application without LMI | 2-6 business days |
| LMI, self-employed or foreign income, a company loan or a more complex application | 4-8 business days |
| Extra documents after ANZ first checks the application | 2-6 business days |
These are estimates, not promises. ANZ starts the clock once it has a complete application and all supporting documents. Missing information, an unusual property or income from several sources can add time, so check the live turnaround times before relying on the table.
How long does ANZ pre-approval last?
ANZ publicly says pre-approval generally lasts around 3 months, assuming your circumstances do not change.
If you are still looking, your broker can request another 3 months using ANZ's extension form. This can take the approval to a maximum of 6 months from the original approval date.
The extension requires a fresh check. ANZ needs updated payslips and current application details, and it can reassess the file before agreeing.
Start the extension before the approval expires. If it has already lapsed, or something has changed, ANZ may ask you to apply again.
Check to see if you are eligible for a home loan
When should you apply?
Pre-approval is most useful when you expect to make an offer in the next 3 months.
It may be the right time when:
- your income and employment are stable
- your deposit and purchase costs are ready or close to ready
- you know the price range and areas you are considering
- you plan to attend auctions or make offers soon
- your current lease or living arrangement gives you a reason to buy within the approval period
It may be too early when you are more than 6 months away, expect to change jobs, still need to build your deposit or have unresolved credit issues.
Applying too early can mean updating the file or starting again before you are ready to buy.
Genuine savings and deposit rules
ANZ checks 2 things during pre-approval: where your deposit came from and how long you have held it.
If you are borrowing more than 90% of the property's value, ANZ generally wants at least 5% of the purchase price to come from your own money. You normally need to show that savings history for at least 3 months.
Gifts, grants, borrowed funds, gambling winnings, builder rebates and personal-loan redraw do not normally count as genuine savings. They may still form part of your broader funds to complete, depending on the application.
If you are a first home buyer, 3 months of rental history can sometimes replace the need to hold your savings for 3 months. The rent must be easy to identify and paid on time, without falling 7 or more days behind.
The rent history only replaces the 3-month waiting period. ANZ still needs to be comfortable with where the deposit came from.
See our guides to genuine savings and low-deposit home loans for the wider options.
ANZ and the Australian Government 5% Deposit Scheme
ANZ participates in the Australian Government 5% Deposit Scheme. It allows some first home buyers to purchase with a 5% deposit, or some single parents to purchase with a 2% deposit, without paying LMI.
| Scheme option | People on the loan | Maximum loan compared with the property value | Minimum deposit |
|---|---|---|---|
| First Home Buyer Stream | 2 | 95% | 5% |
| Single Parent Stream | 1 | 98% | 2% |
At ANZ, the minimum 5% or 2% must be genuinely saved, whatever percentage you borrow. ANZ works out the amount using its own property value.
You normally need to make principal-and-interest repayments, and the maximum loan term is 30 years. You cannot take extra cash out or consolidate other debts while the loan remains in the scheme.
ANZ will not combine the scheme with a guarantor loan. It also does not use the scheme for company or trust borrowers, bridging loans, owner-builders or properties in mining towns. Vacant land by itself does not qualify. Buying land and building can be considered together when both contracts are signed before approval.
ANZ also limits how much cash you can keep after buying. It generally allows enough to cover 6 months of living expenses and 6 months of home loan repayments, with some extra room for changes to a construction contract. If you have much more than that, ANZ may ask you to put more money into the purchase.
At the time of this review, the Brisbane-area property price cap was $1,000,000. Both the purchase price and ANZ's property value need to stay within the cap.
Our Australian Government 5% Deposit Scheme guide covers the national eligibility rules, current price caps and lender differences.
ANZ's $3,000 first home buyer cashback
At the time of this review, ANZ was offering some first home buyers $3,000 cashback when taking out an ANZ home loan of $250,000 or more.
You need to be buying or building your first home, hold the right ANZ account when the loan starts and draw the loan within 180 days of applying. ANZ says it pays the cashback within 60 days after the loan starts.
The offer is not available with a government guarantee, an ANZ LMI waiver or an ANZ Plus Home Loan. ANZ pays one cashback per qualifying loan, and each person can only claim once.
Do not choose the cashback in isolation. The LMI saving may be much larger. Compare both options and check ANZ's current home loan offers before applying because ANZ can change or withdraw the offer.
How ANZ treats HECS or HELP debt
ANZ uses the minimum compulsory repayment from the ATO calculator when assessing HECS or HELP debt. Under the policy supplied for this review, it does not add another servicing buffer or floor, and it leaves the HECS balance out of its debt-to-income calculation.
If the repayment is already deducted from gross pay and ANZ uses your net income, it does not count the repayment again.
The debt can still reduce how much you borrow because the compulsory repayment leaves less income available for the home loan. Our guide to HECS debt and home loans explains how other lenders approach it.
LMI waivers and guarantor loans at ANZ
ANZ may waive LMI for some medical, legal and accounting professionals. Some ANZ staff and borrowers buying in areas ANZ considers lower risk may also qualify.
The standard professional waiver may let you borrow up to 90% of the property's value without paying LMI. Some medical professionals and people buying in lower-risk areas may be able to borrow up to 95% when their total debt is below six times their income.
The occupation list is narrower than many people expect. Nurses, midwives, pharmacists, psychologists, engineers and essential-service workers are not automatically covered. Your broker needs to check the exact occupation and request the waiver.
See our LMI waivers guide for the profession-by-profession comparison.
ANZ also offers guarantor loans using some immediate family members. ANZ calls this a family guarantee. It uses part of the family member's property equity as backup for the loan, but you still need to show you can afford the repayments.
You cannot combine the guarantee with the Australian Government 5% Deposit Scheme or an ANZ LMI waiver. Interest-only repayments are not available with this setup under the policy reviewed.
Our guarantor home loan guide explains the risks, how to limit the guarantee and how it can be removed later.
Property risks after ANZ pre-approval
ANZ can approve your finances and still reject the property. This is where a pre-approval can fall over, so check the property before making an unconditional offer.
Buying in a mining town? Check before you make an offer
ANZ can be tough on properties in mining towns. If you are buying in Moranbah, Dysart, Blackwater or Emerald, the property needs a separate check before you rely on the pre-approval.
Ask your broker to confirm the exact postcode and property with ANZ. Depending on the location, ANZ may ask for a bigger deposit, require a full valuation or say no to the property altogether. This needs to happen before you sign a contract or bid at auction.
Small apartments and studios
ANZ does not automatically decline every apartment under 40 square metres. The limit depends on the size and layout:
| Property type | What ANZ may allow |
|---|---|
| Under 40 square metres | Borrow up to 60% of the property's value, with no LMI |
| 40 to 50 square metres with a separate bedroom | Borrow up to 80% without LMI or 90% with LMI, depending on the property and application |
| Studio, bedsitter or loft-style layout | Borrow up to 60% of the property's value, with no LMI |
| Standard residential unit | ANZ's normal limits may apply, depending on the location and valuation |
Internal floor area excludes balconies and car spaces. Before relying on the table, confirm the measured floor area, layout and development with ANZ. Some locations can trigger a full valuation, lower lending limit or extra property checks.
Our apartment mortgage guide explains why one lender may accept a unit that another lender will not.
Off-the-plan property
Timing changes the result for an off-the-plan purchase. If the property is due to finish within 6 months, ANZ may let you borrow up to 80% of its value without LMI. If completion is more than 6 months away, that broad limit drops to 70%.
The valuation at completion still matters. If the bank's value is lower than the contract price, you may need a larger cash contribution.
Would you like to learn about your situation?
Can ANZ decline your loan after pre-approval?
Yes. ANZ can decline the property, reduce the loan amount or check the application again if something no longer fits.
Common reasons include:
- your income falls or your employment changes
- you take out a new loan, credit card or buy-now-pay-later account
- your living expenses or other commitments increase
- the deposit or genuine savings cannot be verified
- you miss repayments or your credit record changes
- the property type or location does not fit ANZ's rules
- the valuation is lower than the purchase price
- the requirements for an LMI waiver, guarantor loan or government scheme are not met
- the approval expires before the purchase is ready
Do not respond by applying to several banks at once. Repeated credit checks can make things worse. First work out whether the problem is your finances, the property or ANZ's rules. That tells you whether to update the application, change the property or compare another lender.
Our guide to a home loan declined after pre-approval explains the next steps.
Mistakes to avoid with ANZ pre-approval

Applying before you are ready
If you are not buying for another 6 months, you may use up the original approval and extension period before you need it. Apply when you are close enough to make an offer.
Treating pre-approval as unconditional
Read every condition before relying on the loan amount. Approval of your finances does not mean ANZ will accept an unusual property.
Changing your finances during the property search
Avoid new credit, larger card limits, car finance and unnecessary job changes while the approval is current. If something has to change, tell your broker first so they can check the effect.
Letting the approval expire
ANZ needs updated payslips and current details for the extension. Start early rather than trying to fix it after you have signed a contract.
Comparing only the advertised rate
The advertised rate does not tell you whether ANZ is the right lender. Its LMI waiver or 5% Deposit Scheme policy may save one buyer far more than a small rate difference, while another lender may be a better fit for a different income or property.
Our ANZ home loan review covers the broader product, pricing and policy trade-offs.
ANZ pre-approval frequently asked questions
How long is ANZ pre-approval valid?
The initial Approval in Principle generally lasts around 3 months. Under the broker policy supplied for this review, ANZ can consider another 3 months, taking the approval to a maximum of 6 months.
Can I extend my ANZ pre-approval?
Your broker can request an extension using ANZ's extension form. ANZ needs updated payslips and current application details, then decides whether to extend the approval. It is not automatic.
Does ANZ complete a credit check for pre-approval?
Yes. ANZ states that it completes a credit check when you apply for pre-approval.
Will ANZ verify my documents?
Yes. ANZ asks you to show your income, employment, expenses, savings, deposit funds, debts and identity.
Can I use ANZ pre-approval at an auction?
It can help, but it is not final approval. Check the conditions and ask your broker to review the property before bidding because an auction contract is usually unconditional.
Will ANZ recheck my expenses before final approval?
ANZ can check your expenses, debts and finances again before final approval, especially if time has passed or something has changed.
Can I change properties after ANZ pre-approval?
You can use the approval while searching, but ANZ still needs to accept the property and its value.
Do I need a deposit before applying?
ANZ asks for your savings record and how much you have put aside for a deposit. The amount you need and how long you need to have saved it depend on your deposit size and loan setup.
Can I get ANZ pre-approval if I work for myself?
Yes. ANZ generally wants at least 18 months of ABN or ACN history and clear proof of income. The documents differ for sole traders, companies, loans with LMI and people using the Company Wages option.
Is ANZ pre-approval right for you?
ANZ can make sense if you qualify for a professional LMI waiver or the Australian Government 5% Deposit Scheme. It can also suit someone with steady income buying a standard property.
It may be less suitable if you need a low-doc self-employed option, have recent credit issues or want to buy a restricted property.
My starting point is whether the approval matches your income, deposit and the type of property you plan to buy. If one of those pieces does not fit, compare the alternatives before submitting the application.
How we can help
Send us your latest income documents, how much you have saved and the type of property you want to buy. We will check ANZ's rules first, then compare the other lenders on our panel before anything is submitted.
If ANZ fits, we can prepare the application and manage the extension when needed. If another lender has a better policy for your income, deposit or property, we will show you the difference and what happens next.
Call Hunter Galloway on 1300 088 065 or book a free assessment to talk through your situation.