


Yes, your contractor income may count.
If you receive a PAYG payslip, some banks can look at the income much like an employee's wage. If you send invoices through an ABN, they will usually ask for business records instead. A short contract can still work when your earlier employment shows you have been doing the same type of job for years.
Julian had 3 months in the contract. His first bank asked for 2 years of tax returns.
Julian had moved from permanent senior IT work into his first daily-rate contract through a PAYG recruitment agency. He was paid $1,100 a day and had more than 6 continuous years in senior technology roles.
The contract ran for 6 months. When he applied, he had worked 3 months and had 3 months left. His first bank put him in the self-employed box and asked for 2 years of contractor tax returns. He did not have them because he was paid through the agency's payroll.
- $1,100
Daily rate through PAYG agency payroll
- 6+ years
Continuous senior technology history
- $1.35m
Purchase price
- $1.05m
Loan required
I showed the new lender his signed contract, agency payslips and more than 6 years of earlier work in senior technology roles. That made it clear he was a PAYG agency contractor, not someone running a new business.
Julian's $1.05m loan was unconditionally approved on the $1.35m purchase. The first bank had asked for the wrong documents. Once we matched the application to the way he was actually paid, he could move forward.
Do you receive a payslip or send invoices?
Start with how you are paid. These details show whether to assess wages or business income.
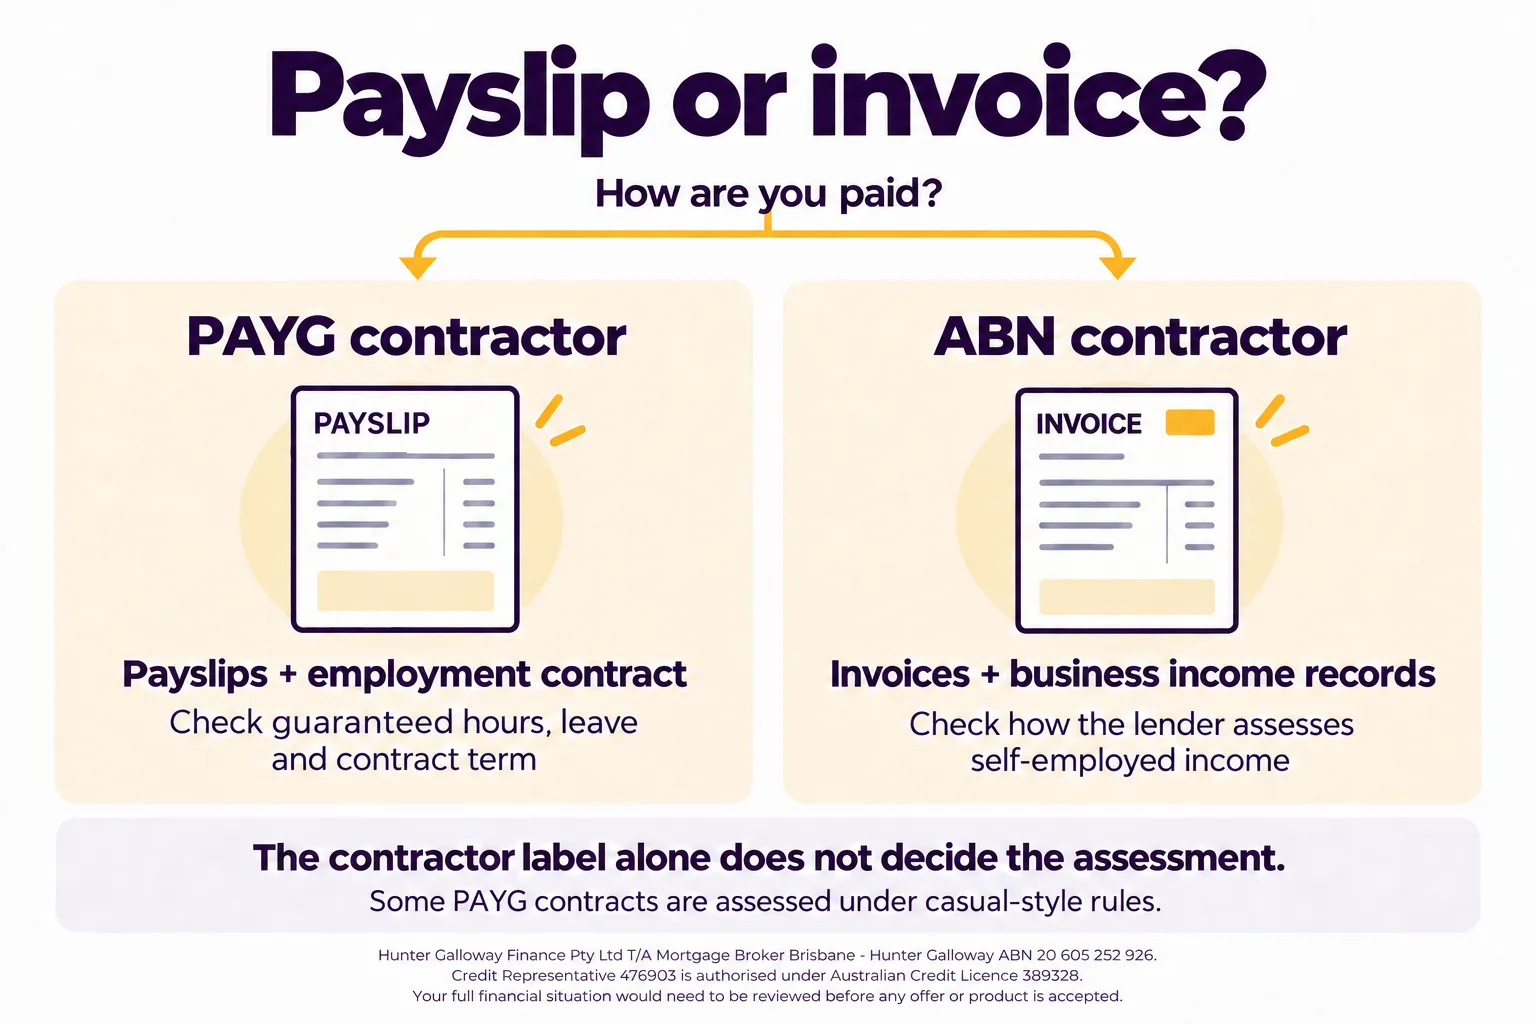
Do you receive a payslip, or do you send an invoice?
Does the employer or agency take tax out of your pay?
Who pays your super?
Do you receive paid annual leave and sick leave?
Do you work for one employer, or run a business with your own clients?
PAYG with paid leave
You receive payslips and the employer or agency handles tax and super. A contract end date does not automatically stop the income from being used.
PAYG day rate or agency work
You are paid through payroll but may not receive paid leave. The bank may average what has actually been paid instead of simply multiplying the day rate.
Invoicing through an ABN
You send invoices and handle your own tax and super. The bank will usually want to see how long the business has traded and what it earns.
If you are paid by a labour-hire or staffing agency as a casual, the casual employment guide explains the current history and income calculation rules.
Can a short contract still work?
Yes. A contract ending in 3 or 6 months is not an automatic decline. I look at how long you have done this type of work, whether earlier contracts were renewed and how much time you have had between jobs.
I compared 7 lenders for this guide. Some focus on how you are paid, some lean more heavily on your earlier work, and one may start with the income that has actually reached your account.
| How lenders assess the income | What that can mean for you | What I check |
|---|---|---|
| How you are paid can change the starting point Commonwealth Bank and ING | A PAYG contract with paid leave may be treated differently from casual or temporary work. | I check the payslip, contract, leave and super before deciding which employment rules fit. |
| Earlier work can support a short current contract Macquarie , Westpac , St George and People First Bank | Time in the same type of job, gaps between contracts and the time left on the current contract can all matter. | I would put the current and earlier contracts in date order, then check every gap between them. |
| What you have actually been paid can set the income NAB | The bank may look at payments over 180 days rather than multiplying the day rate by a full year. | I would average the payments, then compare that figure with the contract and year-to-date pay. |
Can a short contract still work?
How you are paid can change the starting point Commonwealth Bank and ING
- What that can mean for you
- A PAYG contract with paid leave may be treated differently from casual or temporary work.
- What I check
- I check the payslip, contract, leave and super before deciding which employment rules fit.
Earlier work can support a short current contract Macquarie , Westpac , St George and People First Bank
- What that can mean for you
- Time in the same type of job, gaps between contracts and the time left on the current contract can all matter.
- What I check
- I would put the current and earlier contracts in date order, then check every gap between them.
- What that can mean for you
- The bank may look at payments over 180 days rather than multiplying the day rate by a full year.
- What I check
- I would average the payments, then compare that figure with the contract and year-to-date pay.
Lender reviews: Commonwealth Bank; ING; Macquarie; Westpac; St George; People First Bank.
Lender rules checked 31 July 2026. A general starting-point view of the 7 lenders named above, not a ranking, a recommendation or credit advice. Lending policy changes without notice, and any loan is subject to the lender's own credit assessment and approval of your full application.
Julian had only 3 months in his current contract, but he had worked in senior technology for more than 6 years. That longer history was the part his first bank had missed.
How banks turn a day rate into yearly income
A day rate is not an annual salary. The calculation needs to allow for unpaid leave, public holidays and gaps between projects.
The same $1,100 day rate calculated over 52, 48 and 46 weeks
| Working period | Yearly income |
|---|---|
| 52 weeks | $286k |
| 48 weeks | $264k |
| 46 weeks | $253k |
The same day rate across working-week assumptions
52 weeks
- Yearly income
- $286k
48 weeks
- Yearly income
- $264k
46 weeks
- Yearly income
- $253k
At 48 working weeks, $1,100 a day over 5 days is $264k before the lender applies its own evidence and income method.
What that income difference can mean for borrowing power
These estimates keep the other assumptions the same and change only the income figure.
| Income | Estimated borrowing power |
|---|---|
| $286k income | $1.4m |
| $264k income | $1.3m |
| $250k income | $1.25m |
Income and estimated borrowing power
$286k income
- Estimated borrowing power
- $1.4m
$264k income
- Estimated borrowing power
- $1.3m
$250k income
- Estimated borrowing power
- $1.25m
That is about $150k of borrowing capacity between the highest and lowest income figures.
The 46-week income has been rounded to $250k for this borrowing-power example. It keeps the applicant and other assumptions the same. Expenses, debts, dependants, deposit and lender rules can change the result.
The difference between 52 weeks and 46 weeks is $33k of yearly income. A bank may instead use a 180-day average or your year-to-date pay. I use the figure we can prove from your contract and payment history, not whichever multiplication produces the biggest number.
Use the year-to-date calculator to total the income, then confirm which period the lender will use.
What changes when you invoice through an ABN
If you invoice through your own ABN and handle tax and super yourself, the bank will usually treat you as self-employed. It does not matter that the work looks similar to the PAYG job you had before. What matters is how you are paid now.
2 years remains a common starting point, but it is not universal:
I also looked at 5 lenders with shorter business-history options. Most lenders still want at least 2 years of tax returns. There can be exceptions when you did the same job in the same industry as a PAYG employee before becoming self-employed.
| How lenders assess the income | What that can mean for you | What I check |
|---|---|---|
| Options from about 1 year in business NAB and Macquarie | A 1 year option may be available, depending on your deposit, occupation and earlier work. | I check when the business started, the latest financial year, your deposit and the PAYG job you held before it. |
| Options with earlier related PAYG history Commonwealth Bank and Firstmac | Earlier PAYG work in the same or a similar field can matter when the business record is shorter. | I would line up the old PAYG role with the current business activity and test whether the duties and income are genuinely comparable. |
| Option from about 18 months Bankwest | The current rule uses 18 months of ABN or ACN history and the most recent year. | I check the registration dates and make sure the latest year reflects what the business earns now. |
What changes when you invoice through an ABN
Options from about 1 year in business NAB and Macquarie
- What that can mean for you
- A 1 year option may be available, depending on your deposit, occupation and earlier work.
- What I check
- I check when the business started, the latest financial year, your deposit and the PAYG job you held before it.
Options with earlier related PAYG history Commonwealth Bank and Firstmac
- What that can mean for you
- Earlier PAYG work in the same or a similar field can matter when the business record is shorter.
- What I check
- I would line up the old PAYG role with the current business activity and test whether the duties and income are genuinely comparable.
- What that can mean for you
- The current rule uses 18 months of ABN or ACN history and the most recent year.
- What I check
- I check the registration dates and make sure the latest year reflects what the business earns now.
Macquarie’s 1 year option is limited to eligible professional specialisations, with a loan of up to 80% of the property value (the loan-to-value ratio, or LVR). It requires at least 12 months of trading and income evidence from the current business. Checked on 17 September 2026 against Macquarie’s credit guidelines, version 14.1 dated 10 September 2026.
Lender reviews: NAB; Macquarie; Commonwealth Bank; Firstmac.
Lender rules checked 31 July 2026. A general starting-point view of the 5 lenders named above, not a ranking, a recommendation or credit advice. Lending policy changes without notice, and any loan is subject to the lender's own credit assessment and approval of your full application.
Some of these lenders only offer these options for specific industries. Speak with our team for more information, and for full financial year, BAS and add-back treatment, use the self-employed home loan guide.
Begin with the contract, payslip or invoice. Confirm who handles tax and super, whether paid leave applies, time in the current arrangement and earlier work in the same field.
What should you have ready?
| Question | Useful starting evidence |
|---|---|
| Who handles tax and super? | Payslip, contract and agency agreement. |
| Do you receive paid leave? | Employment contract or HR confirmation. |
| How long has the work continued? | Current contract, earlier contracts, CV and employment records showing gaps. |
| What income repeats? | Recent payslips or invoices, salary credits, year-to-date income and prior income statements. |
| Will the contract continue? | Renewal history and a factual employer or agency letter where available. |
| Do you invoice through an ABN? | ABN record, tax returns, notices of assessment, financials, BAS and business statements the bank asks for. |
What should you have ready?
Who handles tax and super?
- Useful starting evidence
- Payslip, contract and agency agreement.
Do you receive paid leave?
- Useful starting evidence
- Employment contract or HR confirmation.
How long has the work continued?
- Useful starting evidence
- Current contract, earlier contracts, CV and employment records showing gaps.
What income repeats?
- Useful starting evidence
- Recent payslips or invoices, salary credits, year-to-date income and prior income statements.
Will the contract continue?
- Useful starting evidence
- Renewal history and a factual employer or agency letter where available.
Do you invoice through an ABN?
- Useful starting evidence
- ABN record, tax returns, notices of assessment, financials, BAS and business statements the bank asks for.
A renewal letter can explain the current plan, but it does not guarantee future income. I would rather use accurate wording and a complete history than ask an employer or agency to promise something outside the contract.
Apply now or wait?
I compare what may work today with what would improve if you waited for the next payslip, renewal or completed financial year.
PAYG with strong same-field history
A short contract may be workable now if a lender can use the longer history in the same type of work.
PAYG with no leave and little history
More payslips can give the lender a longer period to average and more evidence of your current work.
Recently moved to an ABN
Reaching 12 months, 18 months or a completed financial year may give you more bank options.
Planning to change how you are paid
Check the home loan position before moving from PAYG to invoices. The same job can be assessed differently once you start billing through an ABN.
If the issue is simply a new role, use the new job guide. For the broader document and job history checks, see the home loan job requirements guide or the income and employment guide.
Send me the contract, payslip or invoice and the history you want the lender to recognise.
Check my contract income
Frequently asked questions
Related guides
- Start here
Match your contractor arrangement with the evidence a lender may ask for.
- Related guide
How lenders check casual income, hours and work history.
- Related guide
How permanent hours and extra shifts may be assessed.
- Related guide
What can help when you have changed roles or are still on probation.
- Related guide
What lenders check about your role, history and payslips.
- Useful calculator
Get a starting estimate before I check the lender rules behind it.
- Related guide
How agency arrangements, contracts and work history fit together.
Check how my contract income may be assessed
Send me the contract, payslip or invoice and your earlier work history. I will show you which category fits, what evidence is missing and whether applying now is sensible.
or call 1300 088 065
Any loan is subject to the lender’s assessment and approval.
When these rules were checked: The lender rules on this page were checked from 28 to 31 July 2026. Lenders can change their rules and assess the contract, income, deposit, credit history and property individually.
Hunter Galloway. Australian Credit Licence 389328. Credit Representative 476903. This page contains general information and is not a credit assessment, tax, employment or legal advice, or a promise of approval.
Client examples are based on real situations. Names and identifying details have been changed.
Content reviewed on 17 September 2026. Dates beside the lender rules show when they were checked. Confirm the requirements for your application before applying.
Sources and review
How this guide was checked
Editorially reviewed on 17 September 2026. This guide separates employment history, income evidence and the amount a lender may use in its assessment.
Lender comparisons draw on policy sources checked in July to August 2026. Any later checks are dated beside the relevant lender guidance. The public references below support the topics named in each link; they are not a fresh verification of every lender in the comparison.
References
Lender requirements can change. Confirm the rules and documents for your application before relying on an income or borrowing estimate.