


If you want to keep your home and buy an investment, I would compare crossed loans with separate securities before choosing a lender. Both can use your equity. The difference becomes clearer when you want to sell one property and keep the other.
A cross-collateralised loan uses 2 or more properties as security. Cross-collateralisation can also link several loans to those properties. Your home and investment property might both support the borrowing, even when your banking app shows separate accounts.
Crossed loans versus stand-alone security
With crossed loans, the lender relies on more than one property for the connected borrowing. With separate securities, also called stand-alone security, each property supports only the loans agreed against that property.
Separate loan accounts alone do not prove the properties are separate securities. Ask for written confirmation of which property secures each loan and what would need to be repaid if you sold it.
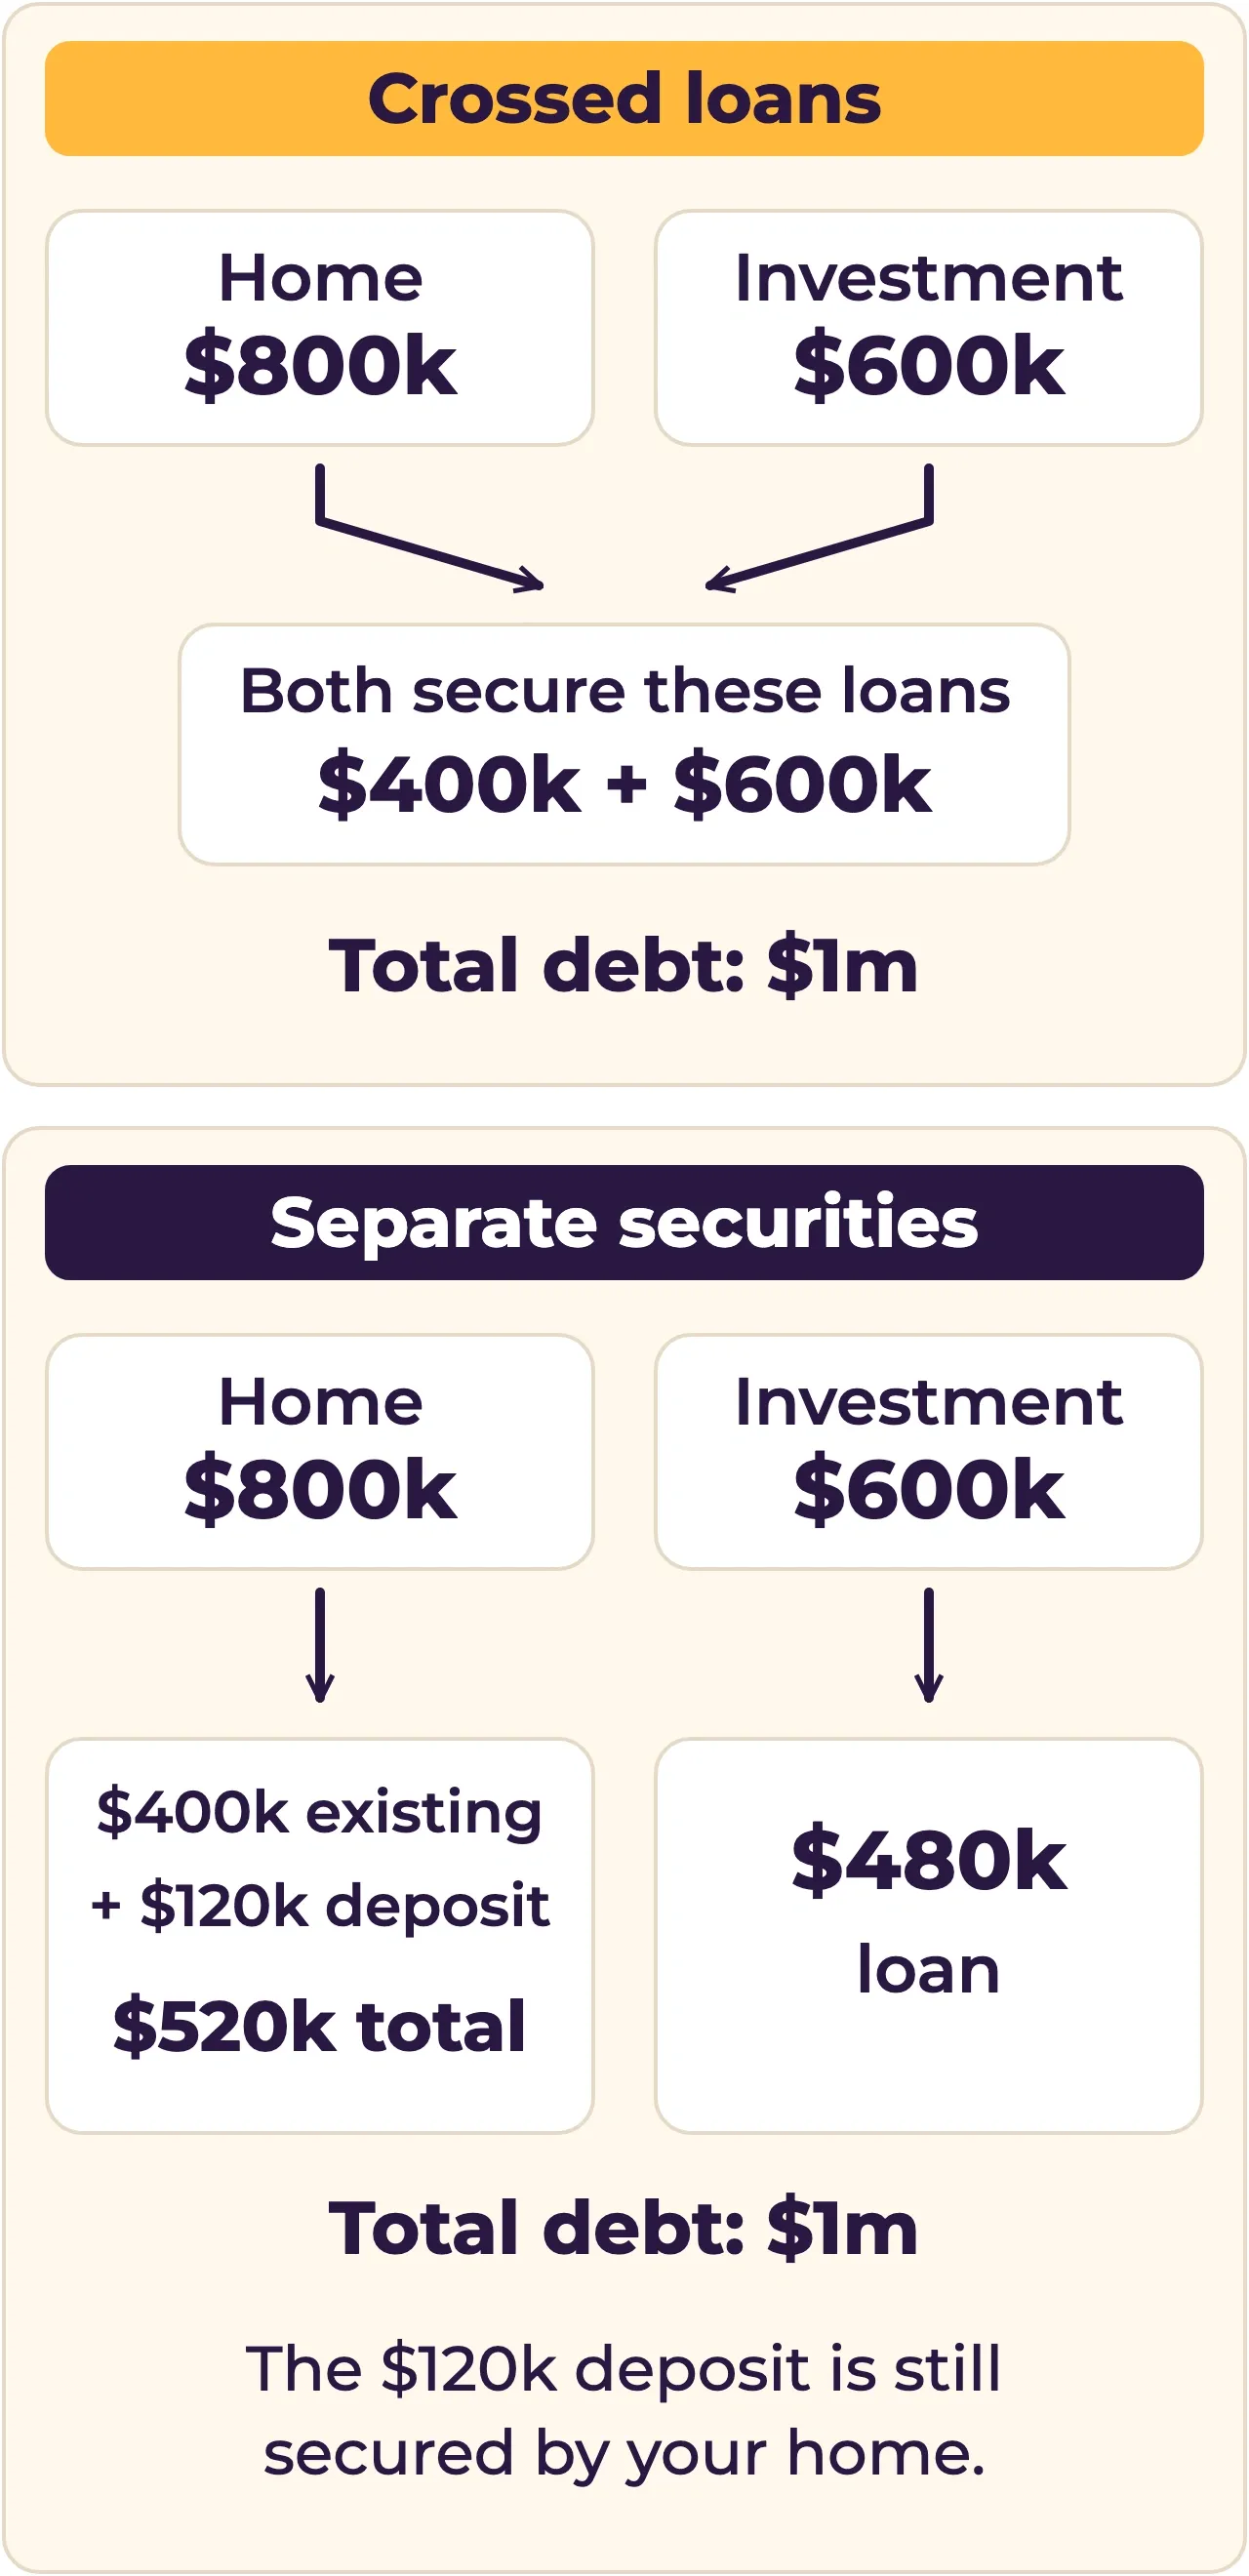
The same purchase, the same total debt
Suppose your home is worth $800k and you owe $400k. You want to buy a $600k investment property and borrow its full purchase price. You pay purchase costs from savings.
The same purchase, the same total debt
Scroll to see more columns
| Comparison | Crossed loans | Separate securities |
|---|---|---|
| Existing home | Worth $800k | Worth $800k |
| Investment purchase | $600k | $600k |
| Borrowing arrangement | The $400k existing debt and $600k new borrowing are supported by both properties | The home secures the $400k existing loan plus a separate $120k deposit loan. The investment secures a $480k loan |
| Total debt | $1m | $1m |
| Loan-to-value ratio | $1m divided by $1.4m: about 71.4% across both properties | $520k divided by $800k: 65% against the home. $480k divided by $600k: 80% against the investment |
The loan-to-value ratio, or LVR, is the debt divided by the value of the property securing it. It helps the lender assess how much security it has.
You can use our LVR calculator to check the percentage for each proposed loan and property. It cannot confirm which properties your mortgage documents tie together.
In the separate arrangement, the $120k deposit is borrowed against your home. Add the $480k investment loan and you still fund the full $600k purchase. You have not created extra equity or reduced the debt by splitting it up.
For this example, assume different lenders hold the home and investment mortgages, with no guarantee or security linking them. A lender may also offer separate security arrangements within the same bank, but the loan and mortgage documents need to confirm that.
Illustration prepared 12 September 2026. Both structures need lender approval, acceptable valuations and enough income to repay the full $1m. Stamp duty, conveyancing, loan fees and other purchase costs are excluded.
Our guide to using equity to buy a second property explains the deposit side in more detail.
What are the main risks of cross-collateralisation?
Less control over sale proceeds. The lender decides what it needs repaid before releasing a property. That can leave less cash available for your next purchase.
Fewer options when values or income change. A lower valuation or a change in your income can make it harder to separate the loans or refinance.
More than one property supports the debt. If repayments fall behind, the lender can enforce its rights over the properties held as security. Separate securities do not remove your obligation to repay the debt or guarantee that other assets are protected.
What happens when you sell one property?
You can sell a cross-collateralised property, but the lender must agree to release its mortgage. Releasing one property while keeping other security is called a partial discharge. Before you commit the sale proceeds to another purchase, find out how much the lender requires you to repay.
The lender may assess the properties left behind, your current financial circumstances and the remaining debt. Its required repayment can be higher than the balance of the loan account you associate with the property being sold.
Macquarie's partial-discharge guidance gives a useful example of the process: it requires a credit assessment and says full net sale proceeds may be needed in some circumstances. Your own lender's requirements may differ.
How $60k more could stay with the lender
Continue the example above. Assume loan balances have not changed. You sell the investment for $600k, but your home's value has fallen to $575k.
For the crossed loans, assume the lender agrees to release the investment only if the remaining debt is no more than 80% of the home's value. That is an example condition, not a rule every lender applies.
How $60k more could stay with the lender
Scroll to see more columns
| Sale calculation | Crossed loans | Separate securities with different lenders |
|---|---|---|
| Debt before the sale | $1m | $1m |
| Debt repaid at settlement | $540k, leaving $460k against the home | $480k investment loan paid out |
| Sale proceeds left before costs and tax | $60k | $120k |
| Debt left against the home | $460k | $520k |
The crossed-loan calculation is $575k multiplied by 80%, leaving a maximum of $460k. The lender therefore requires $540k from the $600k sale to reduce the original $1m debt.
You receive $60k less cash, but also owe $60k less. It is a restriction on your access to the sale proceeds, not an extra fee or a $60k loss.
With separate securities, the investment lender releases its mortgage when its $480k loan is paid out, assuming there are no other secured obligations. The $120k deposit loan remains against your home. Selling the investment does not erase it.
That home debt is now about 90.4% of the home's $575k value. Keeping the sale proceeds may preserve cash, but refinancing or borrowing more against the home could be difficult. Separate securities do not remove the consequences of falling property values.
Both columns ignore selling costs, tax, accrued interest and discharge fees. Ask your accountant about any investment-purpose debt left after the sale.
When can cross-collateralisation make sense?
A crossed structure may help you buy using existing equity while keeping more savings available. One lender may also be convenient to manage. Those benefits need to be compared with a separate-security option using the same loan amounts and repayment terms.
I would want to know what the crossed arrangement actually improves for you. If the only reason is that it is easier to set up, we should still check the cost of changing it later.
More security does not replace income
Equity can help cover the deposit gap. It does not establish that you can afford another loan. The lender still assesses income, expenses, existing debts and the proposed repayments. CommBank's explanation of loan increases distinguishes having enough equity from having enough borrowing capacity.
Compare the actual rate and mortgage-insurance quote
A lower LVR may put a loan in a different pricing band, but crossing properties does not guarantee a lower rate. The lender also considers the loan amount, purpose, product and whether you repay principal and interest or interest only. Compare actual quotes for the same borrowing.
Lenders mortgage insurance may apply when borrowing exceeds 80% of the property's value, although exceptions exist. It protects the lender, not you. The Moneysmart explanation of LMI describes this distinction.
In the purchase example, the crossed LVR is about 71.4%. The separate loans are at 65% against the home and 80% against the investment. Neither arrangement exceeds 80% on those assumptions, so crossing the properties does not by itself establish an LMI saving or extra premium. Ask the lender to confirm its LVR and mortgage-insurance requirements for each proposed arrangement.
Ask for a written comparison of both structures, including any LMI premium, ongoing fees and costs to change the loans. A generic example cannot tell you which will cost less.
Plan for a sale even if you intend to hold
You might expect to keep both properties for years. A job move, separation or change in income can bring a sale forward. If you are downsizing or buying and selling at the same time, the release conditions deserve particular attention.
Does every lender allow the same security arrangement?
Before comparing rates, I would check whether the lender accepts the security arrangement you want. Some rules require properties to be linked; others require them to stay separate. That can narrow your choices before price comes into it.
| Lender and situation | What it means for your plan |
|---|---|
| ANZ: reusing existing security | Where existing security is used and there are multiple securities, ANZ requires them to be cross-collateralised. The debt cannot simply be allocated separately to each property. Ask whether a different arrangement is available for your transaction. |
| AMP: vacant land loans | The vacant land loan must have standalone security. Cross-collateralisation is not allowed for this product. |
| Westpac: Family Security Guarantee | While the Family Security Guarantee is in place, the borrower's security cannot support further lending through cross-collateralisation or debt apportioning. Check the guarantee before relying on that property for another loan. |
| St George: Family Security Guarantee | The same restriction applies: the borrower's security cannot support further lending through cross-collateralisation or debt apportioning while the guarantee is in place. |
Examples reviewed 12 September 2026
- What it means for your plan
- Where existing security is used and there are multiple securities, ANZ requires them to be cross-collateralised. The debt cannot simply be allocated separately to each property. Ask whether a different arrangement is available for your transaction.
- What it means for your plan
- The vacant land loan must have standalone security. Cross-collateralisation is not allowed for this product.
- What it means for your plan
- While the Family Security Guarantee is in place, the borrower's security cannot support further lending through cross-collateralisation or debt apportioning. Check the guarantee before relying on that property for another loan.
- What it means for your plan
- The same restriction applies: the borrower's security cannot support further lending through cross-collateralisation or debt apportioning while the guarantee is in place.
Ask the lender to check the property type, valuations, ownership, existing guarantees and maximum LVR for the proposed loans. It must also be satisfied you can afford the full borrowing. If separate securities suit your plans, request them where the lender and product allow it.
Does cross-collateralisation change your tax deductions?
Crossing properties does not create a tax deduction. The use of the borrowed money matters; simply putting an investment property up as security does not turn private borrowing into deductible debt.
In our example, the $400k original home loan remains borrowing for your own home. The separate $120k borrowed for the investment deposit has a different purpose, even though your home secures both loans.
The ATO's rental-property guidance explains that interest may be deductible for rental-property borrowing, while private use must be excluded or apportioned. Borrowing itself is not a deductible expense.
Keep investment and personal borrowing in separate accounts where practical, and retain records showing where the money went. Ask your accountant to check the proposed money transfers before you redraw or refinance, particularly if you plan to sell or change how a property is used.
How to check or remove cross-collateralisation
Start with the loan offer and mortgage documents. The security section should identify the properties involved, but separate account names or repayments are not enough to establish how the mortgages work.
Ask your lender or broker to confirm:
- Which loans does each property secure?
- If I sell either property, what needs to be repaid before its mortgage is released?
- Can each property be kept as separate security with the current lender?
- What valuations, financial information and fees would a change require?
If the loans are crossed, you may be able to separate the securities with your current lender or refinance some or all of the borrowing. That depends on the property values, how the debt can be allocated and the lender's current assessment.
Could you keep the loan and change the property?
If you are selling and buying, ask about substitution of security, also called loan portability. This replaces the property supporting an existing loan. CommBank's portability guide describes this option, but does not allow borrowers to be added or removed through that process.
Portability does not automatically separate crossed loans. The lender must accept the replacement property, valuations and settlement arrangements. Compare the fees and any fixed rate break costs with refinancing before you decide.
Check the numbers before paying to change
We would compare the proposed loan amounts against each property's value, then check that the repayments still work. A lower valuation or changed income can limit the options. Sometimes reducing debt first makes a later restructure more practical. If a valuation looks wrong, check what evidence would support challenging the bank valuation before committing to a restructure.
Get a quote for any discharge, application, legal or registration costs, valuation charges, LMI and fixed-rate break costs. Moneysmart's refinancing guide explains why those costs belong in the comparison.
Before settlement, check the new offer matches the agreed security arrangement. After settlement, obtain confirmation that the intended mortgage releases have been completed.
Separate securities still carry risk
Your home remains security for every loan agreed against it, including money borrowed for an investment deposit. Different lenders do not cancel your obligation to repay or guarantee that other assets are protected if you default.
If the documents contain broad security, guarantee or default clauses, have your solicitor explain their effect. The aim is to make future sales and loan changes easier to manage, while understanding the obligations you retain.
Cross-collateralisation FAQs
Experience and sources
Sources and how to use this guide
Examples use stated assumptions and do not establish loan approval. Lender examples were reviewed on 12 September 2026 and need to be checked for the loan you are considering. Legal and tax outcomes depend on your circumstances.
Jayden Vecchio is a mortgage broker at Hunter Galloway.
Sources
General information. Obtain advice for your circumstances before acting.
Related guides
Compare your structure before your next purchase or sale
If you want to keep your options open, send us your loan statements, property estimates and what you are planning to do next. We can compare a crossed structure with separate securities and check what each would mean for a sale or refinance.
or call 1300 088 065
Your full financial situation needs to be assessed before a loan can be recommended.