

Yes, you can get a home loan while you are on parental leave. I check the income you receive while you are off, your confirmed return date, hours and pay, the money available to cover any unpaid months and your future childcare costs. We have used that approach to get clients approved while they were still on leave.
Client story
Isabelle's $656k home loan was approved while she still had 6 months of leave left
Isabelle was 3 months into 9 months of unpaid parental leave. Before leave she earned about $120k. Her employer confirmed that she would return permanently on a part-time salary of $96k, while her partner earned $110k.
I asked her employer for a letter confirming the return date, hours, salary and permanent status. I also showed $45k of accessible savings to cover the remaining leave period and included the post-return household costs.
The assessment covered 2 stages: the months still on leave, then the household after Isabelle returned. Her $656k loan was unconditionally approved at 80% of the $820k purchase price.
The return salary showed what Isabelle would earn once she was back at work. Her savings covered the months when she would still be on unpaid leave.
If a calculator treats you as earning $0 because you are on leave, it may be missing a confirmed return-to-work income. If it uses the old full-time salary after you plan to return part-time, it may be too optimistic.
Buying a home while pregnant or on parental leave
This video explains how buying while pregnant or on parental leave can work. The return-to-work evidence, unpaid leave gap and current lender differences are covered in detail below.
How will your income change during parental leave?
I split the timeline into the income before leave, what you receive while you are away and the confirmed pay when you return. Each period needs its own evidence.
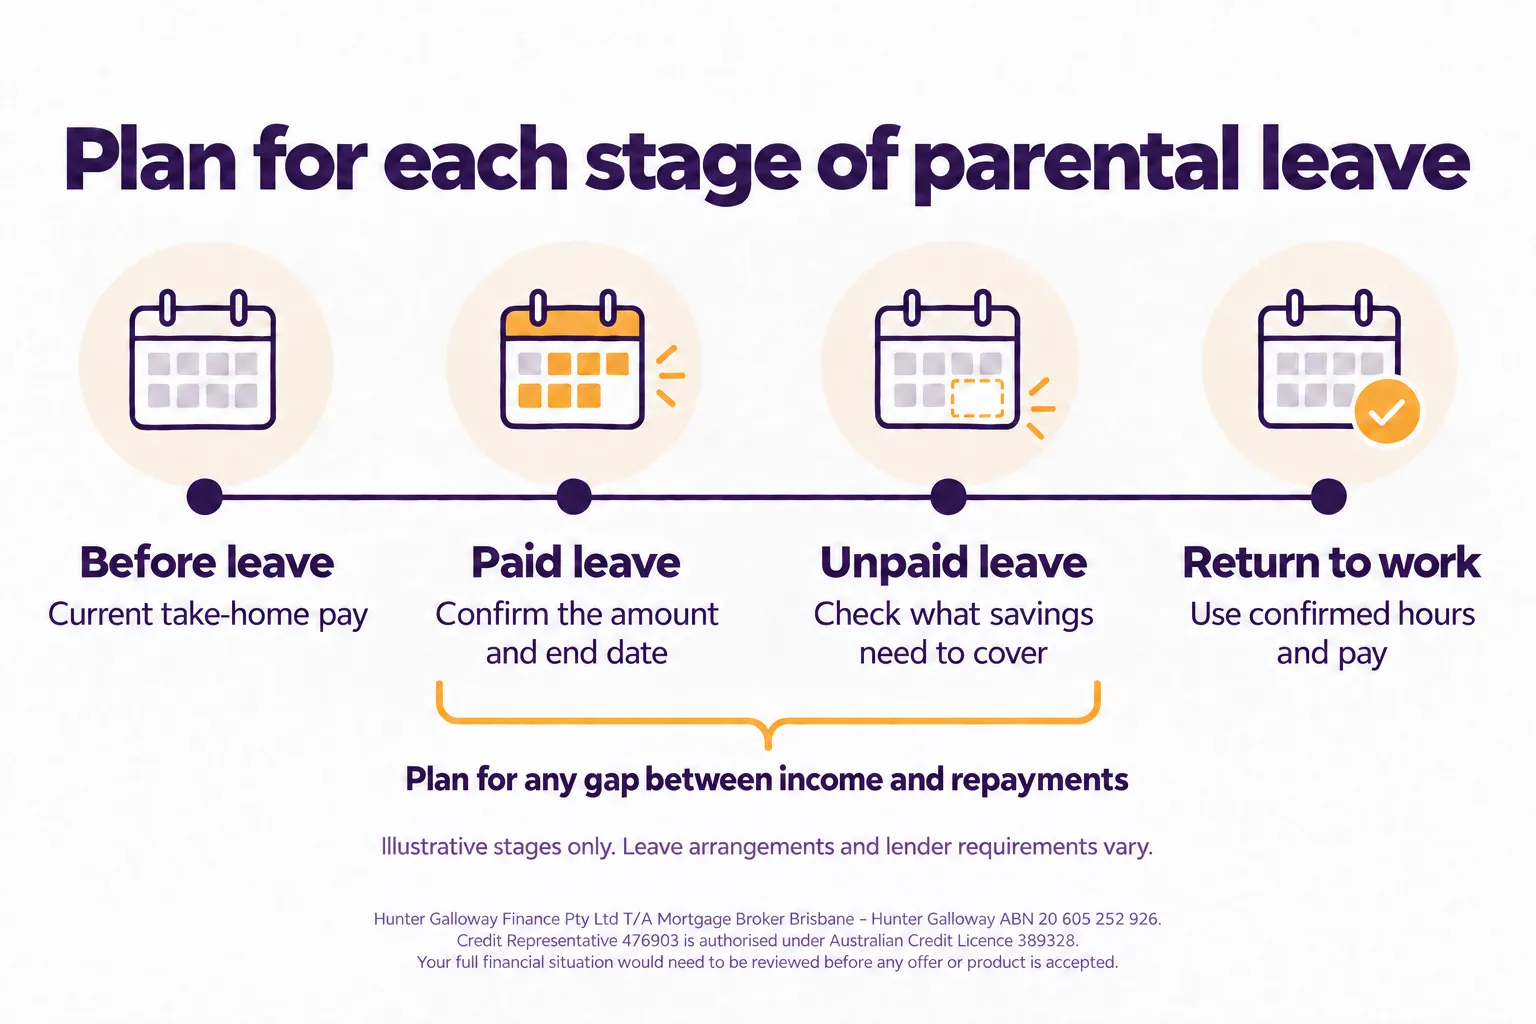
Before leave
Normal hours, base pay and recent payslips.
During leave
Employer leave pay, government payments, partner income and any unpaid gap.
On return
Confirmed date, status, hours, salary and future childcare.
Keep the deposit and the money left to cover unpaid leave as two separate figures. Using the same savings twice can make the application look stronger than it is.
A paid-leave amount does not automatically count through the unpaid months. If any stage of the leave is unpaid, that stage needs its own budget, and the lender will want to see exactly how the repayments are covered through it.
What the parental leave employer letter needs to say
A general employment letter is often not enough. The bank needs to know your return date, hours and pay.
The letter should be on employer letterhead and accurately confirm:
the employee's name, role and employment status
the parental leave start date and expected or approved return date
the role, ordinary hours or full time equivalent on return
the base salary or hourly rate on return
any staged return or temporary change in hours
an authorised signatory and contact details
Sample employer letter
[Employer letterhead]
Date: [DD Month YYYY]
To whom it may concern
We confirm that [employee name] is employed by [employer legal name] as [role] on a [permanent full time / permanent part time / other] basis.
[Employee name] commenced parental leave on [date] and is expected or approved to return on [date].
On return, [employee name] will work [hours per week / full time equivalent / agreed pattern]. Their base salary will be $[annual amount] plus superannuation, or their base hourly rate will be $[hourly rate].
Any confirmed staged return or temporary change in hours is: [details].
Please contact [authorised person, role and contact details] if further information is required.
Signed
[authorised person]
Do not ask the employer to guarantee future employment or include a salary and hours arrangement that has not been approved. Some lenders also have their own form or letter-age requirement.
Download an employer return-to-work letter template
Our employer maternity leave letter template gives your employer or HR team a starting point. It asks them to confirm your return date, employment basis, ordinary hours and gross pay, then sign and date the letter on company letterhead.
Ask the lender or broker whether anything else is needed for your application. This is an employer confirmation for a home loan, not the letter you send to request leave.
Tell us your leave dates, expected return pay and savings, and we’ll compare the options through that period.
Will the repayments work through your leave?
How current parental leave rules differ
Why "100% of income" does not mean the same thing at every lender
I check which income the lender counts: your pay during leave, your confirmed salary when you return, or a lower figure. Then I check how you will cover repayments and living costs until you are back at work.
Macquarie, ANZ and ING can use confirmed return-to-work income when their evidence and leave-funding conditions are met. Macquarie requires enough funds to cover the shortfall in commitments and living costs, including future childcare. It counts either leave pay or return income, not both. ING allows a return to the same employer after up to two years of total leave. That is the length of the leave, not two years from settlement.
Firstmac normally counts the lower of paid-leave income and return income. You must return to the same employer, and the leave payments must continue until you return. It can consider higher return income or a gap at its discretion if you return within 60 days of settlement and have enough savings to cover the shortfall. That option does not fit a return six months after settlement.
Pepper counts the lowest income received during leave. An income gap cannot exceed three months and must be covered by savings. The income figure and acceptable funds still need checking; you cannot carry the paid-leave amount through an unpaid period.
Same family, five different answers
In this fictional example, the family wants to buy while one parent is on leave.
One parent earns $84,000 a year. The other gets $4,000 gross a month throughout leave and is confirmed to return on $72,000 a year, six months after settlement.
They have one infant, $4,500 a month of living expenses including future childcare, and a $5,000 credit-card limit. The loan they’re after is $680,000, which is 80% of an $850,000 property.
Then one input changes: the confirmed return salary drops to $54,000 because that parent plans to come back on reduced hours.
Read these numbers the right way:
These are illustrative calculator estimates for a fictional family, calculated on 2 November 2026, not approved or available loan amounts.
Each lender uses different products, rates and assessment methods. This is not a comparison that isolates parental-leave policy alone.
Firstmac and Pepper count $48,000 paid-leave income in both columns because both return salaries exceed it. Each repeated figure reuses the same saved $48,000 calculation; it is not a second run.
An estimate above $680,000 does not lift the stated 80% funding limit. Borrowing more would require a fresh assessment of LVR, deposit, pricing and policy.
| Lender | Income counted | Estimate at $72k return | Estimate at $54k return |
|---|---|---|---|
| Macquarie | Confirmed return income | $691,022 | $568,013 |
| ANZ | Confirmed return income | $688,007 | $565,428 |
| ING | Confirmed return income | $685,003 | $563,063 |
| Firstmac | $48k paid-leave income in both columns | $557,103 | $557,103 |
| Pepper | $48k paid-leave income in both columns | $529,703 | $529,703 |
Calculator comparison
- Income counted
- Confirmed return income
- Estimate at $72k return
- $691,022
- Estimate at $54k return
- $568,013
- Income counted
- Confirmed return income
- Estimate at $72k return
- $688,007
- Estimate at $54k return
- $565,428
- Income counted
- Confirmed return income
- Estimate at $72k return
- $685,003
- Estimate at $54k return
- $563,063
- Income counted
- $48k paid-leave income in both columns
- Estimate at $72k return
- $557,103
- Estimate at $54k return
- $557,103
- Income counted
- $48k paid-leave income in both columns
- Estimate at $72k return
- $529,703
- Estimate at $54k return
- $529,703
In Macquarie’s calculation, reducing the return salary by $18,000 cuts the estimate from $691,022 to $568,013. That is a $123,009 difference in this example. That is this model’s result for this fictional family, not a rule for yours.
At the $680,000 target, the Macquarie, ANZ and ING full-return calculations leave an assessed margin of only about $42 to $91 a month in the calculator. That is not spare cash in a real household budget or proof that the leave period is affordable.
An unpaid gap needs its own budget
A positive calculator estimate using return income does not pay the mortgage while you are still on leave.
If the leave payments stop on 2 March 2027 and work resumes on 2 June 2027, those three unpaid months need their own assessment. The calculator does not model a dated leave timeline, so there is no borrowing figure or checked savings requirement for that variant here.
I would map after-tax household receipts against repayments, other commitments and living costs for each stage, using the lender’s required assumptions. The money must still be available after the deposit and buying costs.
In this example, $225,000 cash was assumed: a $170,000 deposit, $25,000 of costs and a separate $30,000 leave buffer. These are scenario assumptions. We have not checked whether the $30,000 covers the leave-period shortfall. The research does not establish that it is enough. Savings are not an ongoing salary.
Firstmac’s ordinary continuous-payment route would not cover that unpaid gap. Returning six months after settlement also falls outside its 60-day discretionary window.
Pepper’s three-month gap limit matches the duration only. It does not establish that the income or savings are acceptable. The return-income pathways still need a separate leave-funding assessment.
Check the dates, and the deposit rules
An employer-letter age limit is not a return-to-work deadline. Macquarie's return-date letter must be no more than 60 days old at submission. That is about the letter, not about when you have to be back at work. Confirm the evidence dates for the actual lender rather than assuming one rule fits all, and use the approved return hours and salary, with dependants and expected childcare included.
First-repayment timing can change the deposit rules too. Our lender-policy checks found the following Westpac limits for a new loan or increase using return-to-work income where the first repayment falls due before the borrower returns:
Up to 80% LVR without mortgage insurance.
Up to 90% base or capitalised LVR for owner-occupiers with mortgage insurance.
No mortgage-insured investment loan in that circumstance.
These are conditional caps, not a promise of eligibility. Other restrictions can reduce them. They are Westpac conditions, so do not apply them automatically to another lender.
Before applying, I match your actual leave schedule, confirmed return pay, accessible funds and household costs to the current policy. General information only; every loan remains subject to the lender's full assessment and approval.
Use the hours you will actually work
If the return is 3 or 4 days a week, I use the confirmed part-time income. I do not carry the old full-time salary forward and hope the extra days happen later.
A staged return should show the date, hours and pay at each stage where possible. The future childcare cost should match the hours and days being used in the income assessment.
Fair Work explains the entitlement to return to work, including what happens if the role held before leave no longer exists. Employment rights and lender evidence are related, but the legal right to return does not tell the bank the exact hours and salary.
Apply before, during or after leave?
Apply before leave
Current payslips may make the income easier to verify, but you still need to tell the lender about your planned leave so it can assess the change.
Apply during leave
The lender needs your return letter, leave schedule, available savings and a budget that includes your new household costs.
Apply after returning
New payslips can simplify the evidence, but waiting is not automatically necessary when the return-to-work details are already supported by evidence.
- Related guide
How permanent part time hours and additional income may be assessed.
- Related guide
How lenders check casual hours, income and work history.
You may be able to apply while you are still on leave when the return terms and leave budget are clear. If either is still uncertain, I would show you what needs to change before an application is worth lodging.
⚠️ If your return date, hours or pay are not confirmed, or childcare costs have changed, let us know before we assess the loan.
What should you have ready?
Confirm the leave schedule and every income period.
Obtain the employer letter with return date, status, hours and pay.
Calculate the monthly shortfall from settlement to return.
Show accessible savings, redraw, benefits or other accepted resources covering that shortfall.
Add future childcare, dependants, debts and the proposed repayment.
Match the timing and evidence to a current lender rule before lodging.
Check current Australian Government payment eligibility and periods with Services Australia. A government payment can help household cash flow without automatically being treated as permanent salary.
Our home loan job requirements guide covers the broader employment document process. The income and employment guide is useful when parental leave sits beside casual, contract, overtime or allowance income.
Frequently asked questions
Can you apply while you are still on leave?
Send me the leave schedule, return letter, household income and accessible savings. I will check whether the leave period and your return-to-work income can support an application now.
or call 1300 088 065
Any loan is subject to the lender’s assessment and approval.
About this information: Parental-leave income and evidence rules can change, and every household is assessed individually. This page contains general information only and is not a credit assessment, employment-law advice or a promise of approval.
Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328.
The assumptions behind the numbers
- The family: two fictional married Australian residents, ages 34 and 35, permanent PAYG for three years, one infant.
- The property: owner-occupied established house in postcode 4051, $850,000 value, $680,000 proposed loan, 80% LVR, 30-year principal-and-interest term, 50/50 ownership.
- Income: $84,000 PAYG for one parent; $4,000 gross a month of continuous leave pay for the other until return; confirmed return salary of $72,000, tested again at $54,000. No HELP debt, other loans, rent, benefits, overtime or other income. A $5,000 card limit is counted despite a zero balance.
- Living expenses: assessed at $4,500 a month across all five calculations: $3,700 declared (housing $700, phone and internet $200, food $1,200, recreation $300, clothing $250, medical $200, transport $500, insurance $350) plus $800 future childcare. Childcare during leave is assumed nil; the comparison deliberately uses the future cost. No expense-floor override.
- Dates: leave starts 2 November 2026, settlement 2 December 2026, return 2 June 2027. Ages, tenure and leave dates are scenario assumptions, not verified employment evidence. The calculator uses annual PAYG income fields, so its annualised tax treatment is not an actual financial-year cash-flow forecast.
- Products and nominal/assessment rates at the run date: Macquarie Offset Package 6.34%/9.34%; ANZ Standard Variable with Offset 6.38%/9.38%; ING Orange Advantage 6.44%/9.44%; Firstmac Standard Variable 6.79%/8.79%; Pepper Prime Full Doc 7.34%/9.34%. The selected package rates were used without overrides. These are model inputs, not current rate offers or product recommendations.
- The maximum figures are illustrative calculator estimates on the entered loan structure; they do not establish property or security eligibility or changed-LVR pricing. Macquarie's own calculator reports annual surplus/NSR rather than this maximum-loan figure.
Sources and review
How this guide was checked
Joshua Vecchio reviewed the full guide, including the updated comparison and calculations, on 2 November 2026. The new comparison and calculations were added on 2 November 2026.
Lender policy details and figures were checked on 2 November 2026 against broker policy sources, including Macquarie’s credit guidelines (v15.0, October 2026).
The worked example is fictional. The figures are calculator estimates, not approvals or offers. Lender rules change, so check the current rules for your situation before relying on a figure here.
Isabelle’s story is the existing real-client example, with names and identifying details changed. The five-lender comparison is fictional.
