Eligible first home buyers can use the First Home Super Saver scheme to release some of their own voluntary super contributions for a deposit. A Brisbane mortgage broker can check how the lender will treat those funds and when you’ll need the cash. An SMSF can invest in property for retirement, and someone who has met a condition of release may be able to use withdrawn super to buy a home. Each option has different rules.
Quick Summary
- The First Home Super Saver (FHSS) scheme lets eligible first home buyers count up to $15,000 of eligible voluntary contributions per financial year and $50,000 overall, per person. Compulsory employer contributions don’t count. Each eligible buyer applies separately. Your usual super contribution caps still apply.
- The FHSS release calculation generally includes 100% of eligible after-tax contributions for which you don’t claim a deduction, 85% of eligible concessional contributions, and deemed earnings. The assessable part gets a 30% tax offset. The ATO may withhold tax before paying you.
- Any tax saving depends on your contribution type, taxable income and when the ATO releases the funds.
- The ATO calculates deemed earnings at its shortfall interest charge rate. Check release timing before committing to a purchase.
- Alternative options for home buyers include getting a guarantor, saving a larger deposit, or buying with a partner/family member.
- Self-Managed Super Funds (SMSF) can be used to buy investment properties but with strict rules and potential risks.
- Using personal loans as a deposit is strongly discouraged due to reduced borrowing power and potential loan rejection.
Can I Use Super To Buy A House?
In this section, we’ll help you figure out if you’re eligible to buy a house with superannuation. So, if you’re not sure if buying a house with super will work for you, this section will get you on the right track. Then, later on, we’ll show you a bunch of advanced strategies and techniques.
What are the features of the FHSS?
Eligible first home buyers can make voluntary super contributions and ask the ATO to release eligible amounts for a deposit. Compulsory employer super guarantee contributions can’t be released under FHSS.
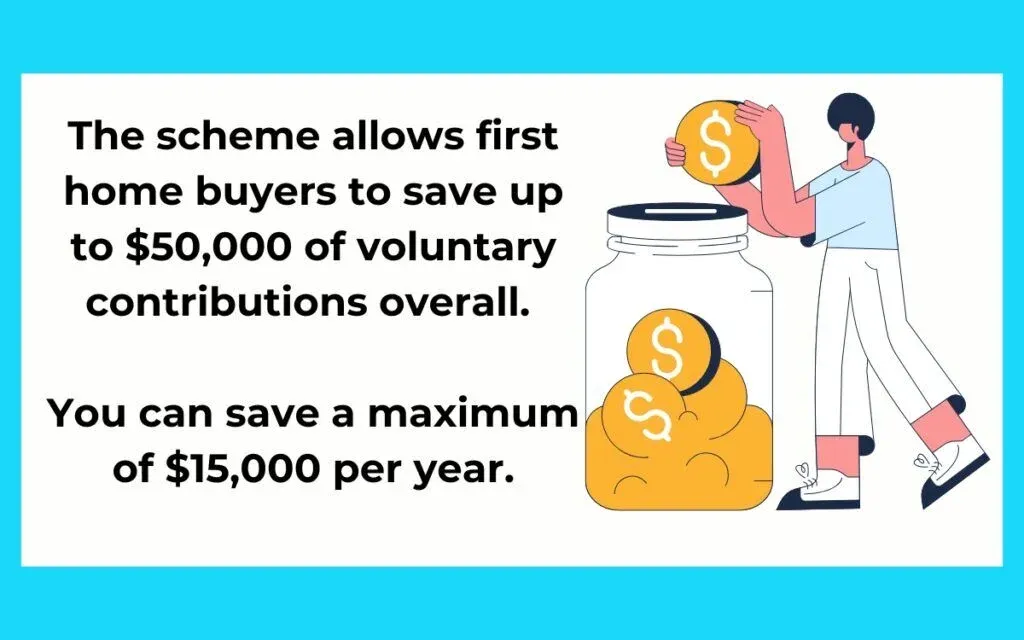
- Up to $50,000 of eligible voluntary contributions can count per person across all years.
- No more than $15,000 in eligible contributions counts from any one financial year.
- Two eligible buyers can each use their own $50,000 contribution limit. Their release amounts are worked out separately.
- Check the FHSS property and contribution rules separately from any citizenship or residency rules that apply to your loan, duty concession or grant.
The scheme can also be used in conjunction with the First Home Owners Grant too.
When the money comes out, the taxable part counts as income for that financial year, but you get a 30% tax offset on it. The ATO withholds tax at your expected marginal rate less that 30% offset before it pays you, or a flat 17% if it can't estimate your rate. The 15% you see quoted around the place is the tax on before-tax contributions going into super, not on the way out.
Am I Eligible To Make Voluntary Contributions Towards My Super Deposit?
In order to use the scheme, you should meet ALL of the following requirements:
- You must be 18 or older when you request an FHSS determination. Eligible contributions made before you turned 18 can still count.
- You must be a first home buyer. This means you must not have owned property in Australia before including vacant land or commercial property. Your name must be on the title of the property you want to buy.
- You must intend to occupy the property for at least 6 months within the first 12 months of it being practicable to move in, and be a member of an Australian super fund
- You don’t have a completed release request in relation to a FHSS determination made in relation to you.
If you have owned a property before, you may still qualify for the scheme, provided you prove that you suffered a FHSS financial hardship.
Using super for a house deposit: how much can FHSS help?
The amount you receive depends on how you contribute, how long the money stays in super and how the assessable release is taxed. Compare it with how much you could save after tax in a bank account.
Suppose you contribute $15,000 through salary sacrifice in one financial year and all of it qualifies. The FHSS calculation includes $12,750 of those contributions, plus deemed earnings, before any tax withholding. Budget the amount you’ll actually receive before you count it towards a deposit.
Differences In Using Super For Low and High Income Earners?
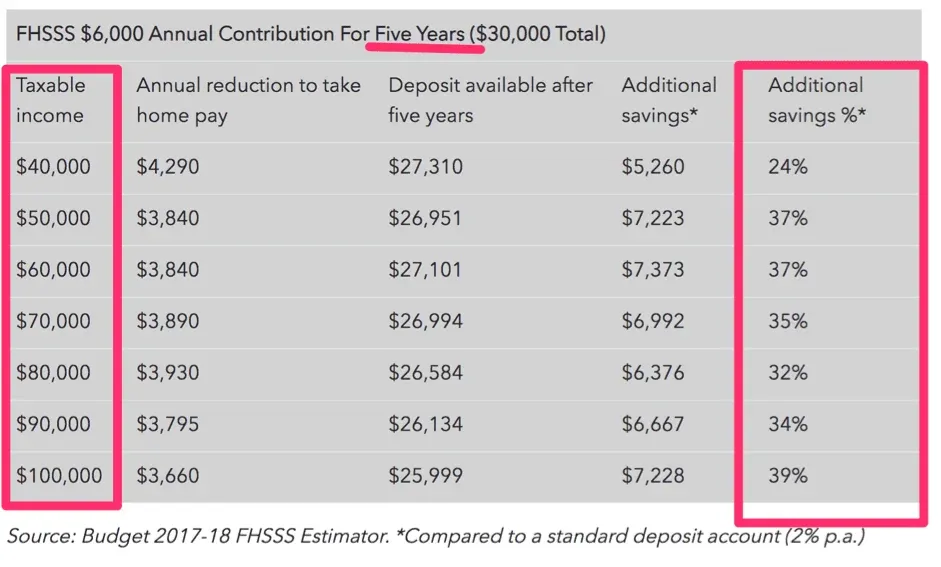
Your income and tax rate affect the benefit, alongside the type and timing of the contributions.
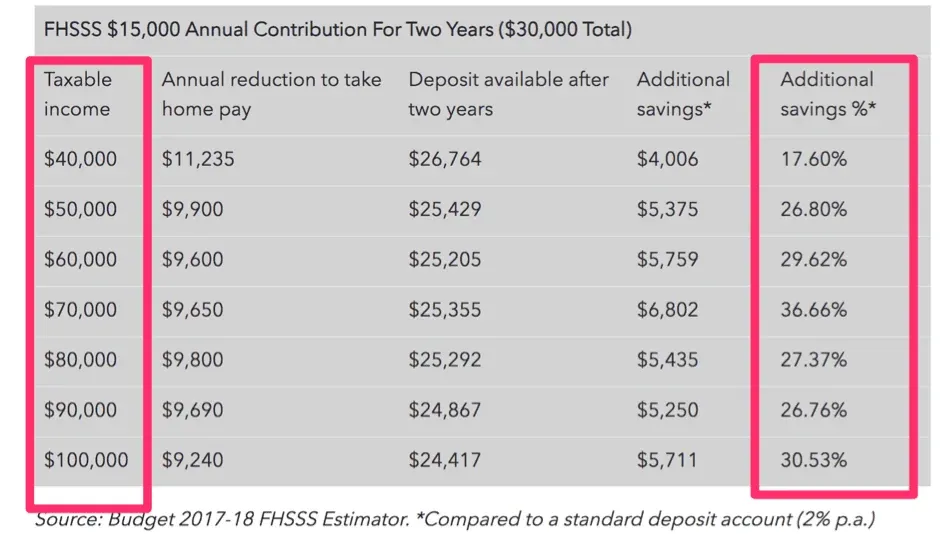
The ATO’s determination shows your maximum release amount. Ask a tax adviser to compare it with what you would save outside super.
How To Request Funds From Super?
Check your contribution records and ask the ATO for an FHSS determination. The $50,000 limit applies to contributions that can count. Your actual release depends on the type of each eligible contribution and its deemed earnings.
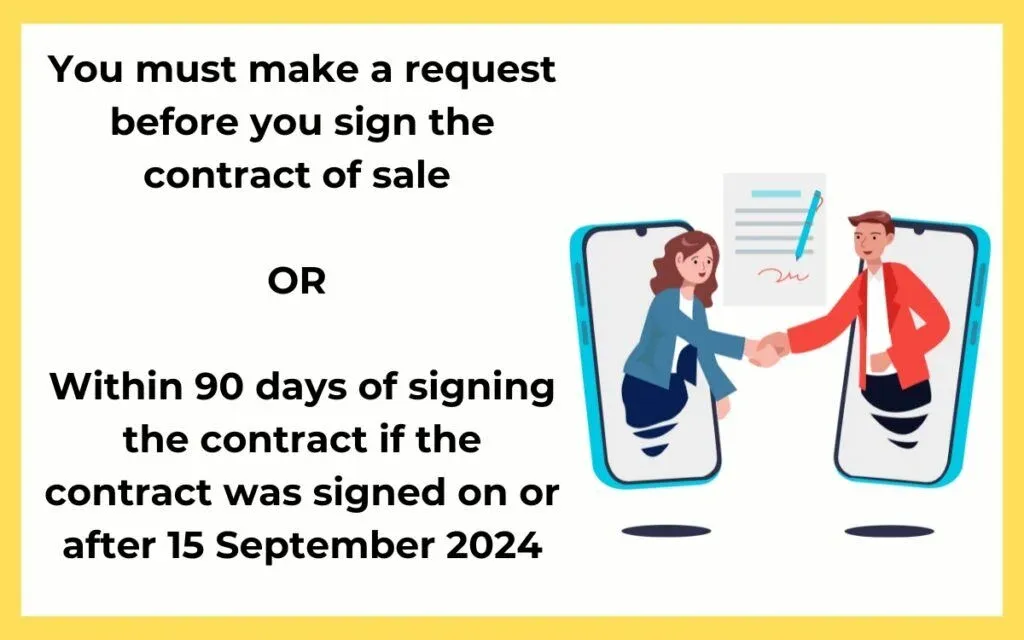
Get your determination before ownership transfers to you. For a determination made on or after 15 September 2024, you can request release before signing a purchase or construction contract, or within 90 days after signing. If you request release first, you generally have 12 months to sign. The ATO may allow more time. Tell the ATO within 90 days of signing and check your contract deposit deadline separately.
Check the amount and your details before requesting release. The ATO generally permits only one completed release request.
Wait, what’s an FHSS Determination?
Ask for a determination before requesting release. You can seek a fresh determination while eligible, but make sure you have a valid one before you become the property owner. Check your contribution records, contract and settlement dates with the ATO.
Step-by-Step Timeline For Accessing Your Super To Buy A Home
Here is a simplified step-by-step timeline of using super to buy a House
Before Week 1: Build your super contributions
The FHSS only works if you’ve already made eligible voluntary contributions over time, often 12 to 24 months or more to build a meaningful amount. If you haven’t started yet, your first step is to plan and contribute regularly before you even begin the withdrawal process. For SMSF buyers, ensure your fund is set up and compliant before considering a purchase.
Get your FHSS determination
If you’ve already contributed, ask the ATO for your FHSS determination to see your maximum withdrawal amount. Hunter Galloway doesn't arrange SMSF loans. If you are considering property through an SMSF, get licensed financial and tax advice before committing.
Check records and eligibility
FHSS applicants confirm contribution records and line up a property search. SMSF trustees update their investment strategy and seek member/trustee approval for the purchase.
Request release and track the payment
The ATO says releases generally take 15 to 20 business days. Confirm the funds and deadlines with your lender and solicitor. If you’re buying for an SMSF, work with your licensed adviser and the chosen lender.
Plan for contract and settlement deadlines
Ask your solicitor when the contract deposit is due and your lender when the funds must be cleared for settlement. Plan around those dates and keep enough cash available if the release arrives later.
Tip: Build in a buffer. Processing times can change, especially during peak ATO or lender periods.
Check to see if you are eligible for a home loan
Savings examples
Seeing the numbers can make your options clearer. Here are three real-world examples showing how using super to buy a house can work.
Case 1, FHSS First-Home Buyer
Sarah earned $80,000 a year and made voluntary super contributions over two years to build her first home deposit. She used eligible savings from super towards the purchase. For a sense of the numbers, $12,000 in eligible salary sacrifice would add $10,200 to the FHSS release calculation before deemed earnings and any withholding. The fund would deduct $1,800 in contributions tax at 15%.
Case 2, SMSF Investor
David has $200,000 in his SMSF. He uses it to buy a $500,000 investment property through a Limited Recourse Borrowing Arrangement (LRBA). The property is rented until he reaches retirement age, generating rental income that goes back into the fund.
Case 3, Preservation Age Purchaser
Linda was 60 and had $300,000 in super. She used a lump sum to buy a smaller home mortgage-free and reduce her living costs. Access at 60 depends on meeting a condition of release, such as retiring after preservation age. Your fund can explain which condition applies.
These examples show the diverse ways super can help you enter the property market or improve your housing situation.
Pros And Cons Of The Scheme
Not every Government scheme is perfect. So, let’s look at the pros and cons of the First Home Super Saver Scheme to give you a clear idea of whether it is for you.
The pros of the First Home Super Saver Scheme
- Eligible contributions and the offset on an assessable release may reduce your tax.
- You can use the scheme as a couple, combining your funds.
- Your contributions are deemed to earn the Shortfall Interest Charge (SIC) rate. It's the 90-day bank bill rate plus 3%, and the ATO resets it each quarter. For October to December 2026 it is 7.51% p.a. It isn't your fund's actual return, but a set rate the ATO uses to work out your release.
- The ATO uses deemed earnings for the release calculation. Make sure the fund has enough available to release.
- You generally have 12 months from your release request to sign an eligible contract if you have not already signed one.
The downsides of the scheme
- It is subject to change in line with government changes.
- You will have less take-home pay as the money will be salary-sacrificed.
- The ATO says most FHSS releases take 15 to 20 business days. Allow extra time during peak periods.
- If you haven’t signed an eligible contract, you generally have 12 months after requesting release. The ATO may allow an extension. If you don’t buy in time, you generally need to recontribute the required amount to super or pay 20% FHSS tax on the assessable released amount.
- $50k is the most of your voluntary contributions that can count towards an FHSS release, which might not be enough for a deposit (if you don’t want to pay LMI).
- Earnings are worked out at the SIC rate, not your fund's actual return, so a strong year for your fund won't lift the amount released.
Combining Super Strategies with Other Government Schemes
You don’t have to choose one path. You can combine super strategies with other government support to get into a home sooner.
FHSS and the 5% Deposit Scheme
FHSS funds can contribute to your deposit. The Australian Government 5% Deposit Scheme lets eligible first home buyers buy with a minimum 5% deposit without LMI. Check both schemes’ eligibility, the property price cap, lender approval and when the deposit money will arrive.
SMSF + Negative Gearing
An SMSF may be able to deduct eligible property expenses against its own assessable income. That doesn’t cover a cash shortfall in the fund or offset your personal income. Ask the fund’s tax adviser to check the borrowing and income treatment.
Preservation Age + Downsizer Contribution
If you’re 55 or older and meet the downsizer contribution rules, you may be able to contribute proceeds from selling your home to super. Whether you can withdraw any super to buy another property is a separate condition-of-release check.
When you combine schemes, check all eligibility criteria first. Rules can be complex, and the benefits depend on your personal situation.
If I Can't Use Super As My Deposit, What Other Options Have I Got?
If you are not eligible for the FHSS, don’t despair. Fortunately, there are other options for you to get into the property market. In this section, we will lay out a few different ways you can buy a house sooner rather than later.
1. Get a Guarantor
If your deposit is short, a parent or close family member might be able to use equity in their home to guarantee part of your loan. Each lender sets its own rules on who can be a guarantor.
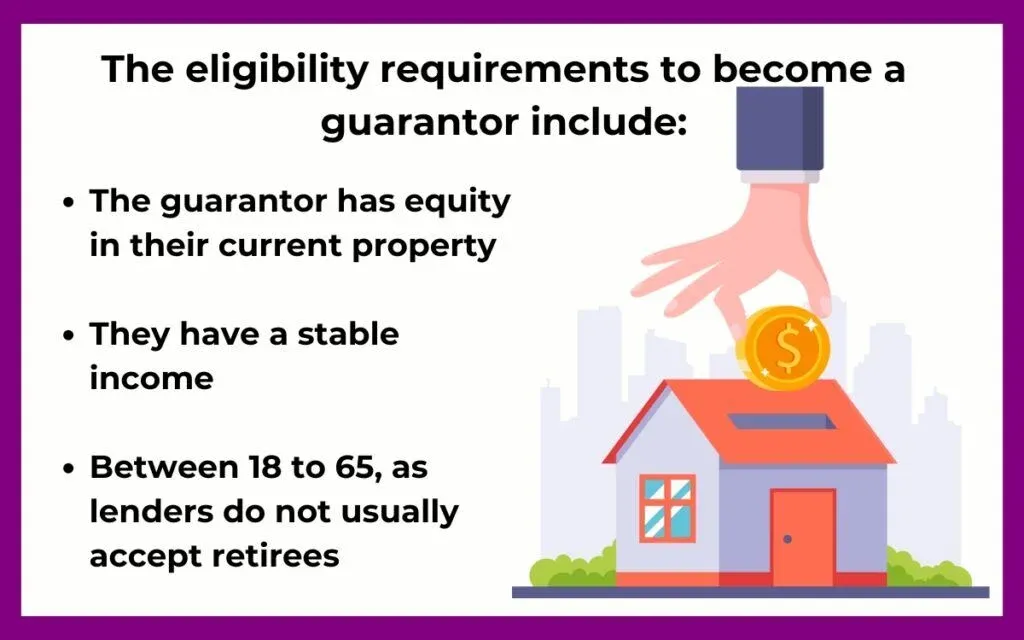
If you can’t repay, the lender can call on the guarantee. The terms set out how much your guarantor could owe, including any interest, fees and charges that apply. Property used as security can be at risk.
Read more: Guarantor home loans
2. Save a more significant deposit
Sometimes, all you need to do is continue saving and wait a little longer. The more you save, the easier it will be to pay your mortgage and still afford to live comfortably.
A great way to maximise your savings is by starting with your expenses. Do an audit of unnecessary spending. Are you spending money on Uber Eats or AfterPay each week? Time to cut those expenses and replace that money by putting it into savings.
These small changes will help you speed up your savings process.
Read more: How to set a budget for buying a home
3. Buy with a partner or family member
A lot of thought needs to go into this one if you’re planning to buy a property with a partner or family member.
First, ensure you’re on the same page and have clear guidelines for each buyer.
Figure out a contract with ownership over the property, and have an exit strategy should either of you want to sell their half of the property.
You may feel like these steps are unnecessary, but should financial circumstances change, it’s essential to have all of your ducks in a row.
Buying with your partner or family member can be a great way to combine your savings and make the process much more affordable.
Self-Managed Super Funds, How Do They Work?
Now that you’ve thought about other options for saving, aside from the FHSS, it’s time to take a look at Self-Managed Super Funds (SMSF).
In this section, we’ll show you how to work with an SMSF and make the most of it.
This section is specifically for property investors.
Self-Managed Super Fund property rules
So, what is a self-managed super fund? It is a private super fund that allows you to manage your retirement savings. SMSF owners have full control over investment decisions and strategies as opposed to a regular super.
You can use a self-managed super fund to buy an investment property. The catch is…. You are not allowed to live in it!
You can buy the property through your SMSF, and the fund can have up to six members.
The members will need to make a decision together about how the super is invested.
What are the SMSF rules?
To buy a property through an SMSF, you must comply with a few rules.
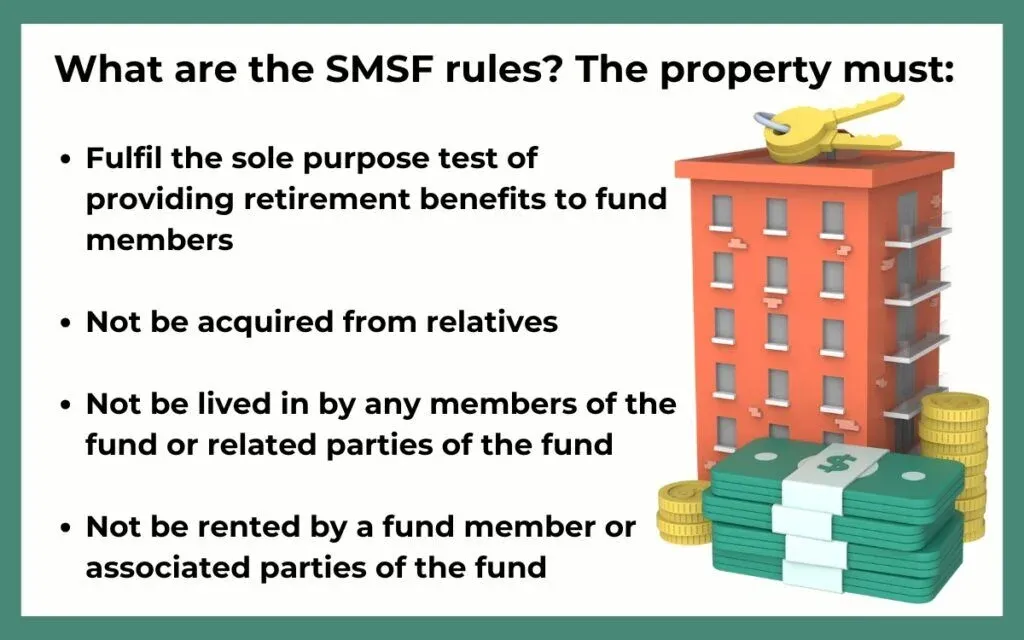
The property must:
- Fulfil the sole purpose test of providing retirement benefits to fund members
- Not be acquired from relatives
- Not be lived in by any members of the fund or related parties of the fund
- Not be rented by a fund member or associated parties of the fund
Business real property may qualify for acquisition from, or leasing to, a related party if the fund meets the rules. Terms must be at arm’s length, including market rent. Get specialist SMSF advice before committing.
What will it cost to use super for a house deposit?
Buying an investment property through a self-managed super fund will still have the same fees and even some extra charges that could eat into your super balance.
Ask a licensed SMSF adviser about the structure and costs, then confirm the lending terms with a lender or broker who arranges SMSF loans. Hunter Galloway does not arrange SMSF lending.
Some of the fees incurred include:
- Legal fees
- Stamp duty
- Advice and upfront fees
- Ongoing property management fees
- Bank fees
Key things to remember about SMSF borrowing
This is where things can get a little tricky.
Borrowing or “gearing” your super needs to be implemented in a controlled and strict way.
The conditions to follow are around a ‘limited recourse borrowing arrangement’.
This type of arrangement can only be used when buying a single asset such as residential or commercial property.
If you are ready to commit to a geared investment, consider whether or not the investment is in line with your broader investment strategy.
What are the risks of a geared SMSF property?
- Cash flow, putting money from your SMSF into your loan is required, and you will need to have enough cash flow to maintain this
- Extra costs, SMSF property loans are often more costly and have additional fees compared to standard loans.
- Potential tax loss. The losses on the property cannot be offset against your income outside of the fund.
- No turning back. If you haven’t set up your loan correctly, like documentation and the contract, then turning the arrangement around can be very difficult. Sometimes, it’s not even possible. In this case, you would potentially have to sell the property, which would most likely result in a loss.
- The ATO’s limited recourse borrowing rules allow the borrowed money to pay for repairs and maintenance. It can’t fund improvements. Check how you’ll pay for proposed work and whether the work changes the asset before you start.
Would you like to learn about your situation?
Bonus: Using A Personal Loan As A Deposit
As tempting as it can be to get a personal loan and use it as a deposit, don’t do it.
Why?
- Tell the lender if any of your deposit is borrowed. Some lenders won’t accept it and loan repayments can reduce what you can borrow.
- Ask your broker to compare what you could borrow with and without the personal loan.
These days, there are a lot of self-proclaimed social media financial advisors encouraging you to get personal loans and use them as a deposit. As tempting as it may sound, run far, far away from personal loans. Instead, talk to a home loan expert who will help you get the home loan that is right for you.
So, no matter how persuasive the video telling you to get a personal loan is, just don’t do it.
Frequently Asked Questions
Is Using Super To Buy A House Right For You?
If you plan to use an FHSS release for your home deposit, tell us what you’ve saved and your purchase timeline. We can check how the lender will treat those funds and what other cash you need. For super and SMSF advice, speak with a licensed adviser.
The lender usually pays the broker when your home loan settles. Ask about any fees up front.
To discuss your FHSS deposit and home loan, book a free assessment or call us on 1300 088 065.
Your broker has a support team to help with the application and keep you updated.
The information on this page is general in nature and should not be considered as advice. Before you act on this information, you must seek independent legal and financial advice.