These are three terms that you’re almost certain to come across as you plan on buying your first home. It’s important to know what these mean.
What is LVR?
LVR is the loan-to-value ratio. Divide the amount you want to borrow by the property value the lender uses, then multiply by 100 to get a percentage.

If your LVR is above 80%, you may need to pay lenders mortgage insurance (LMI). Some borrowers qualify for a guarantee or a lender waiver.
In this example, an $80,000 loan on a property valued by the lender at $100,000 gives an 80% LVR. Ask the lender whether any insurance or other costs apply to your loan.

An example of 80% LVR, this was calculated by dividing the loan amount of $80,000 by the home value of $100,000 times 100.
Read More: Try the LVR Calculator
What is LMI?
Lenders mortgage insurance protects the lender if a borrower can’t repay the loan and the property sale doesn’t cover the debt. If the lender requires LMI, you’ll usually pay it as a one-off cost at settlement or have it added to the loan if the lender allows that.
LMI stands for lenders mortgage insurance.

A $60,000 deposit on a $600,000 home is 10% of the price. If the lender also values the home at $600,000, a $540,000 loan gives a 90% LVR before any LMI is added. Whether you pay LMI and how much depends on the lender and application.
This amount varies a lot between different banks, sometimes adding up to a significant extra cost.
The comparison below shows how seven earlier estimates differed for the same purchase. Use it to see how LMI can vary, and ask for a fresh quote for your own loan.
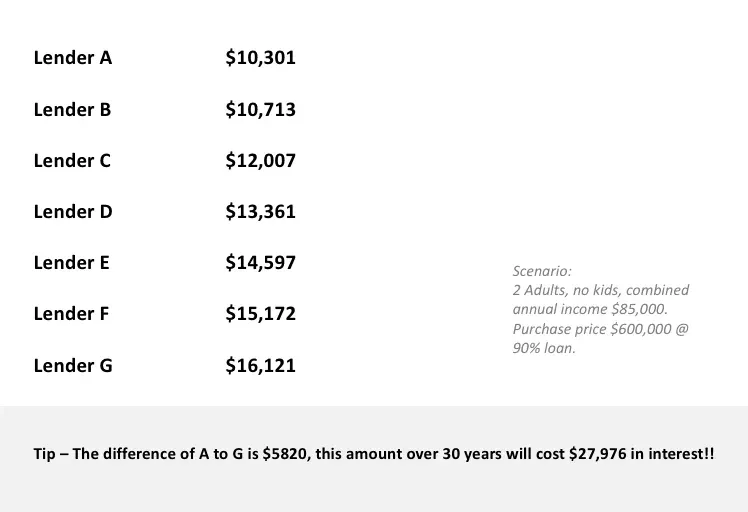
Lenders Mortgage Insurance (LMI) costs vary greatly between lenders.
In that comparison, the estimates ranged from $10,031 with Lender A to $16,121 with Lender G for the same borrower and purchase.
That’s a $6,090 difference in those estimates.
Compare the interest rate, loan fees and LMI together. If a lender adds LMI to the loan, allow for interest on that amount as well.
In some circumstances, you can arrange to have the LMI waived if you work in a certain profession. The best way to know if you’re eligible for an LMI waiver is to speak to a mortgage broker. If you want to know more about LMI and your options, get in touch with us here.
Read more:LMI Calculator, Try it out yourself!
What are genuine savings?
Some lenders ask for genuine savings. Their rules say how much you need and which funds count, based on how you held or built them up.
Ask your lender or broker which account records they need before you rely on savings, a gift or another deposit source.

- Examples to check with your lender about genuine savings include money built up or held in an account, shares, a term deposit or equity in another property.
- Ask how the lender treats a release under the First Home Super Saver Scheme and what evidence it needs.
- Ask whether your rental history could count as evidence.
The rules can differ by lender, type of loan and LVR. Ask early if you’re using a smaller deposit or part of it came from a gift.
If the lender requires genuine savings, check how much it expects you to have built up or held.
Ask which records the lender accepts to show genuine savings and how far back they need to go.
Keep enough cash aside for applicable transfer duty, legal fees, inspections and other costs.
If a lender requires genuine savings of 5% on a $500,000 purchase, that’s $25,000. Ask how long the lender wants you to have held it, what you need for buying costs and whether LMI applies.
Can I use what I pay in rent as genuine savings?
Some lenders may accept your rental history as evidence when you’re using a gift or other funds for the deposit.
Ask the lender what can count and what it needs to see.
- How long do I need to have been paying rent?
- Does a private lease or a rental through an agent qualify?
- Which names need to be on the lease or payment records?
Rental history is evidence of regular payments. You still need to provide the deposit and show where it came from.
The lender may ask for a rental ledger or a reference from your property manager when it assesses genuine savings.
Read More: What is genuine savings?
If I rent, do I still need a deposit?
You will still need to provide a deposit for your home loan even if you are renting.
Ask what deposit and buying costs you’ll need, and whether options like a guarantor or an eligible government guarantee suit your position.
Now that we’ve covered these few key financial terms, let’s look at your borrowing power in more detail.