Your deposit reduces the amount you need to borrow. Keep enough cash for buying costs and an emergency buffer as well; using every dollar at settlement can leave you short afterwards.
The deposit you need depends on your loan and eligibility. Some buyers can use a 5% deposit scheme or a guarantor; others need a larger contribution or pay LMI. Ask for the cash required at settlement, including fees, rather than relying on a single deposit percentage.
We will review the full amount you will need for a deposit shortly, including stamp duty, but if we just look at the bank deposit required for a $300,000 purchase, a 5% deposit is $15,000 or a 20% deposit is $60,000
Purchase Price
$300,000
$400,000
$500,000
$750,000
5%
$15,000
$20,000
$25,000
$37,500
10%
$30,000
$40,000
$50,000
$75,000
15%
$45,000
$60,000
$75,000
$112,500
20%
$60,000
$80,000
$100,000
$150,000
Buying costs are separate from the deposit. Budget for conveyancing, inspections, lender fees and any transfer duty. Grants and duty concessions depend on your eligibility, property and state.
The table shows deposit amounts only. Your broker can calculate the additional cash you need for the loan option you qualify for.
The contract deposit is the amount due under your purchase contract on the agreed dates. It is part of your purchase funds, but it is different from the total contribution your lender requires at settlement. Finance approval does not automatically determine when it is payable; ask your solicitor before signing.
If you haven't saved enough, compare the options below and the risks attached to each.
Could family help with your deposit?
A guarantor may let an eligible buyer borrow the purchase price and some costs, depending on the lender. You still need to afford the repayments and meet its credit requirements.
Here are some ways that you can buy a home without a deposit:
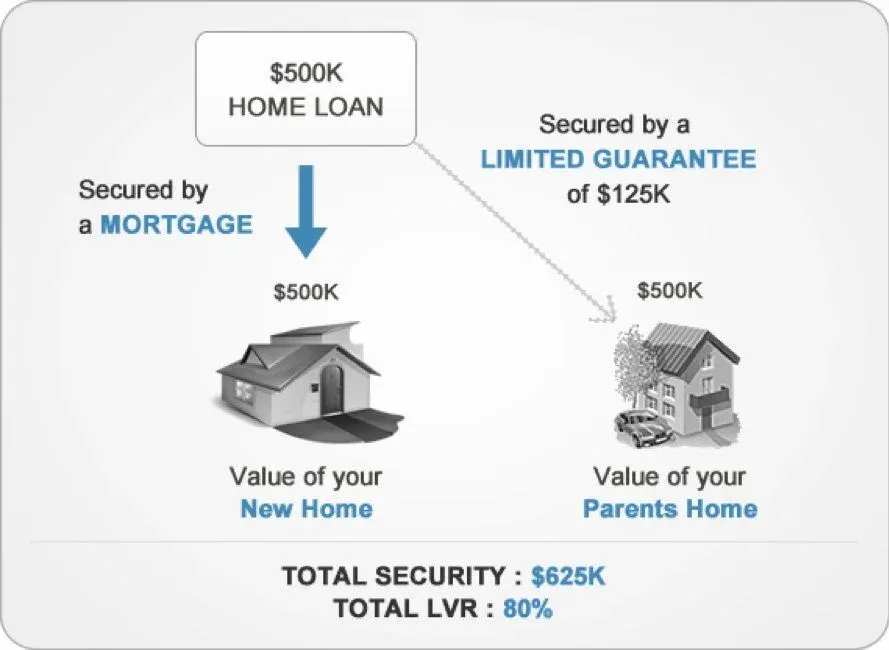
A family guarantee can reduce the cash deposit needed or help avoid LMI. Check the required savings, upfront costs and loan limits before assuming you can buy with no cash contribution.
The guarantee is not released automatically. You and the guarantor must ask the lender to remove it, and satisfy its valuation, equity and credit requirements.
The guarantor's property is security for part of your debt. If you cannot repay, the lender can pursue the guaranteed amount. The guarantor should obtain independent legal and financial advice.
Example of a typical guarantor home loan structure
A family member may offer additional property security, subject to lender approval. Compare this with a cash gift and make sure everyone understands their obligations.
A guarantee can put the family member's home or other security at risk. Agree on a plan for reducing the guaranteed amount, without promising a release date the lender has not approved.
A larger cash contribution or an increase in accepted property value may help you apply to remove the guarantee later. The lender makes the decision.
A family gift can help with your deposit. Tell the lender whether the money is a gift or a loan; repayments on a family loan may affect your borrowing capacity.
Queensland First Home Owner Grant: $30,000 for eligible new homes
Queensland's First Home Owner Grant is $30,000 for eligible transactions with a contract signed on or after 20 November 2023. Owner-builders have a separate commencement-date test. Check the current Queensland Revenue Office eligibility rules before relying on the grant.
The total value of the new home must be less than $750,000, including the land and relevant contract variations. Citizenship or residency, previous ownership and occupancy requirements also apply. The grant's payment timing may not cover the contract deposit, so confirm when the money will be available.
Your lender may count an approved grant towards your settlement contribution. That does not replace its loan approval, genuine-savings or upfront-cash requirements.
Bear in mind that when you apply for a no deposit home loan, lenders apply very strict criteria, including having good credit, with a well-maintained repayment history, stable income sources such as a regular job and consistent payments, as well as a common property type, banks don't like strange properties like caravans or removable houses.
If you are planning on using one of the options above, make sure to sort out your finances as early as possible. If you are relying on a deposit being gifted from your parents, getting a guarantor loan or relying on the first home owners' grant, there can be a bit of back and forth to have the funds available and ready in time for settlement. You're much better off being prepared and avoiding the stress of worrying if the money is going to make it into your bank account in time.
Start with what you can afford each month, then work back to a purchase budget. Include living costs, ownership costs and a buffer for changes in repayments.
Understanding what you should borrow is important so you can continue to live within your means and still have some spare cash left over for your weekly avo on toast!
There are a number of added costs when it comes to buying a house besides stamp duty and other settlement costs and fees, such as council and water rates, maintenance and repairs, and the added risk of interest rates rising.
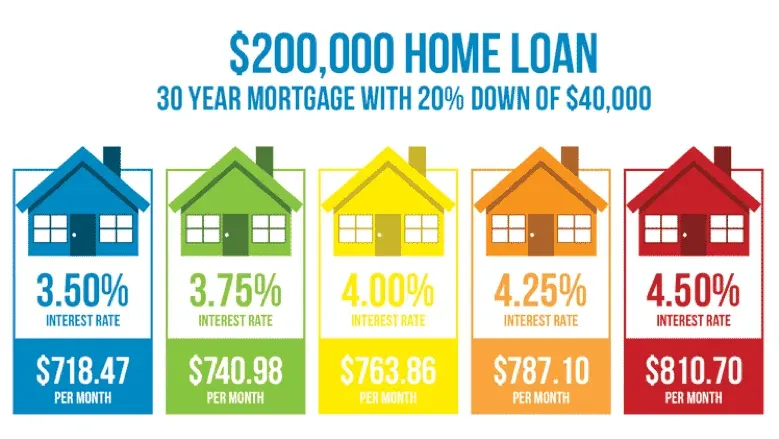
Check the repayments at your proposed loan amount and at a higher rate. The extra cost of borrowing more depends on the rate and term, so use a repayment calculator rather than a fixed monthly rule of thumb.
If you borrow too much, you run the risk of overextending and getting the wrong home loan.
I personally found it hard to accept how expensive some properties were when I first started looking, and this is completely common and normal.
Every home buyer knows the feeling, you're looking for a home that fits your budget, but there's that much more expensive property that looks so much more appealing!
Your first home doesn't need to be your home forever.
Buying a home that's way out of your price range could well derail your finances in the future. It's human nature for us to want a little more than we can afford, and there's always a real estate agent who'll talk you to the next level.
But don't be tempted, the bank has usually offered you a borrowing limit for good reasons based on your ability to repay the loan.
Spending more than you can sensibly afford leaves you exposed to potential financial shocks, including rises in interest rates. You must also allow for changes in your future circumstances.
Before making an offer, compare recent sales, check the property's risks and confirm your finance budget. Our property research guide explains what to check.
Saving a deposit usually means making trade-offs. Choose changes you can maintain, and keep a separate buffer for unexpected expenses.