

Client story
Patrick earned $25k more in his new job, but his bank declined the loan
Patrick was a software engineer who moved after 4 years with 1 employer. His salary rose from $105k to $130k. 4 weeks into the new role, with a standard 6 month probation period, his bank ran the application through its automated assessment and declined it.
- $105k to $130k
Base salary increase
- 4 years
Earlier work in the same industry
- $710k
Purchase price
- $568k
Loan at 80% loan-to-value ratio
We showed the lender that Patrick had spent 4 years as a software engineer before moving into another software engineering role. With his signed contract and first matching payslip, we found a lender that could consider his full new salary. His $568k loan was unconditionally approved.
The quick answer
✅ Permanent full time or part time PAYG: some lenders have no minimum time in the job. Your contract lets us start comparing options, but the bank decides what pay evidence it needs before approval.
⚠️ Casual: 3 to 6 months is a more common starting point. Some occupations and lender exceptions can work sooner, so do not assume you must always wait 6 months.
⚠️ Still waiting on employment evidence? We need to confirm your employment terms and income before relying on them. The lender may ask for a payslip later.
First I check whether the new job is permanent or casual, then what pay evidence the lender needs. If you've started your new job but haven't had your first payslip, NAB can use your employment contract or a letter from your employer instead. For casual work, the income history is usually the bigger question.
Can you apply before your first payslip?
Sometimes, if the new role is permanent PAYG and the contract shows the start date, base salary, hours and employment status. NAB usually wants to see that you've been paid twice. If you've just started and don't have payslips yet, NAB can use your employment contract or a letter from your employer instead. If you haven't started the job, we'll check with NAB before you apply. Other lenders have their own employment and payslip requirements.
That does not mean the contract completes the whole application. The lender still assesses the property, deposit, expenses, debts, credit conduct and whether the employment has actually started. A payslip may be requested later to confirm that the pay matches the contract.
Some lenders want at least 1 pay. CBA can consider 1 payslip, or a contract together with the previous year's income statement. Bankwest can consider 1 payslip for permanent base income. Westpac and St George can consider permanent base income once the job has started and 1 pay is available where lenders mortgage insurance does not apply. St George holds First Home Guarantee loans to its stricter insured test, even though no insurance is charged.
A contract can solve an evidence question. It does not make a conditional job, variable bonus or future allowance certain. Separate guaranteed base salary from overtime, commission, allowances and bonuses.
What if you changed employer but stayed in the same industry?
Your earlier work can make a real difference when you have only just started the new job. Macquarie can consider 6 months with the current employer or 6 months in the same field or industry with a previous employer. ING can consider someone after 3 months in the new job, or 6 months where lenders mortgage insurance applies, or earlier where they have 2 years in a similar role or industry. Westpac and St George can consider 12 months in the same occupation when lenders mortgage insurance applies, as long as the gap between jobs is no more than 2 months.
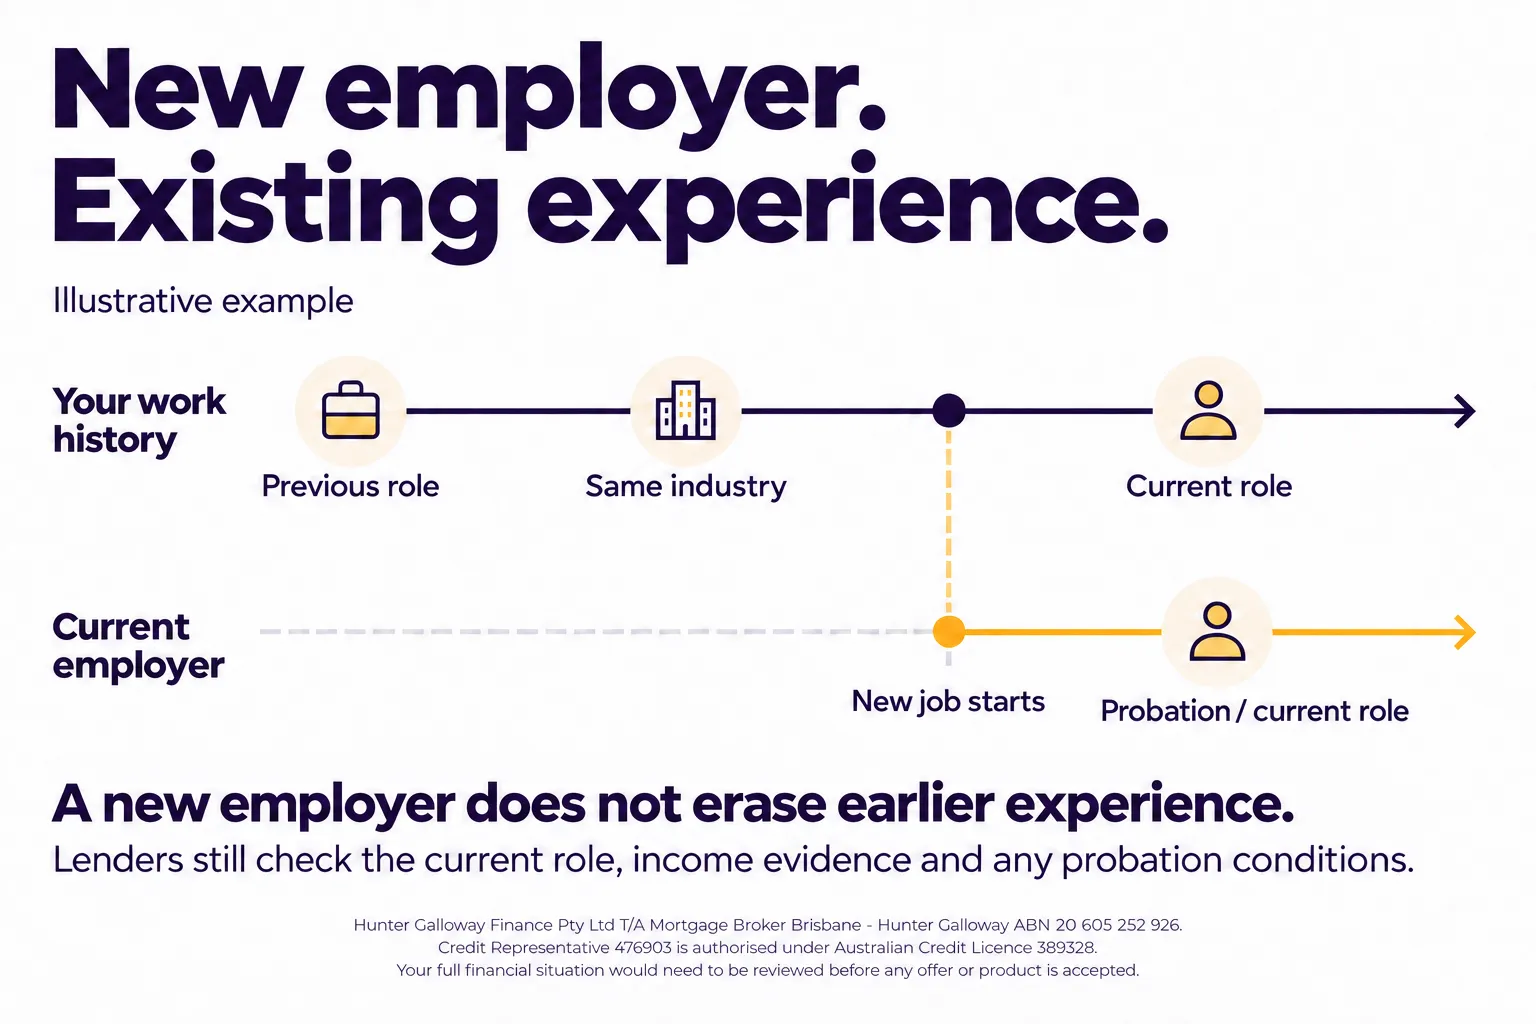
The wording matters. Same occupation, same field, similar role and same industry are not always treated the same way. A nurse moving hospitals is easier to connect than a person moving from retail management into software sales, even when both roles pay more. Nurses and doctors starting a new hospital job have extra lender rules, including for interns, residents and registrars. Our home loans for nurses guide and home loans for doctors guide cover them.
Patrick's 4 years as a software engineer did not guarantee approval everywhere. It gave us enough evidence to find a lender that could look beyond the 4 week start date.
What if the new job is casual?
A new casual job usually needs a different history check. Many lenders start around 6 months, while selected options can work from 3 months. Shorter exceptions may also be possible when the role, hours, earlier work and deposit support the application. The casual employment home loan guide compares those rules and explains what evidence may help you move sooner.
What if the new job is fixed-term or paid through an ABN?
A contractor may be PAYG, variable PAYG or self-employed, so the contract and pay structure matter. If you invoice through an ABN, start with the self-employed guide.
How much time do you need in a new permanent job?
There is no single waiting period. CBA and NAB do not publish a minimum time in the current role for newly commenced permanent PAYG work. Their starting rules also do not add a separate limit for the gap before the new job. The main question is whether the current permanent job and income can be verified.
Other banks do use a time-in-role test or rely on your earlier work as an alternative. That is when the exact gap between jobs can matter.
| How lenders assess it | What that can mean for you | What I check |
|---|---|---|
| No minimum time in the new permanent role: Commonwealth Bank, NAB, UBank and Bankwest | You may not need to wait 3 or 6 months simply because the permanent PAYG job is new. NAB usually wants to see that you've been paid twice. If you've just started and don't have payslips yet, it can use your employment contract or a letter from your employer instead. CBA can use 1 payslip, or an employment contract with the previous year's income statement. | I check that the job is permanent, the base salary is clear and the available documents match the way the income will be assessed. |
| Earlier industry history may help: Macquarie | Macquarie can consider 6 months with the current employer or 6 months in the same field or industry with a previous employer. Its published rule does not require the time between those roles to be counted. | I check whether the earlier role was genuinely in the same field or industry and whether the employment contract and payslip show the new base salary clearly. |
| 3 months in the new job, or a recent move with a gap under 28 days: ANZ | ANZ can consider permanent employees after 3 months in the new job, even if there was an earlier gap. A separate option can work for recent job changes where the gap was under 28 days. We check your employment history before applying. | I would map the last day with the old employer and the first day with the new one before relying on this option. |
| Time in the current job or continuous earlier work: Westpac, St George and ME Bank | These lenders may use earlier work as an alternative in selected cases, but the occupation, insurance position and permitted break between jobs can change the result. | I check the exact gap, whether mortgage insurance applies and whether the earlier role fits the lender's wording. |
| Several job changes: Bluestone | Bluestone no longer limits its Prime loans to PAYG applicants with no more than 2 employers in the last 12 months. I still need to explain your job changes in the application, along with any gap between jobs longer than 30 days. Bluestone asks for 12 months of work history. | I check your employment dates, current contract and payslips, then compare the rate and fees with other lenders. |
How much time do you need in a new permanent job?
No minimum time in the new permanent role: Commonwealth Bank, NAB, UBank and Bankwest
- What that can mean for you
- You may not need to wait 3 or 6 months simply because the permanent PAYG job is new. NAB usually wants to see that you've been paid twice. If you've just started and don't have payslips yet, it can use your employment contract or a letter from your employer instead. CBA can use 1 payslip, or an employment contract with the previous year's income statement.
- What I check
- I check that the job is permanent, the base salary is clear and the available documents match the way the income will be assessed.
- What that can mean for you
- Macquarie can consider 6 months with the current employer or 6 months in the same field or industry with a previous employer. Its published rule does not require the time between those roles to be counted.
- What I check
- I check whether the earlier role was genuinely in the same field or industry and whether the employment contract and payslip show the new base salary clearly.
3 months in the new job, or a recent move with a gap under 28 days: ANZ
- What that can mean for you
- ANZ can consider permanent employees after 3 months in the new job, even if there was an earlier gap. A separate option can work for recent job changes where the gap was under 28 days. We check your employment history before applying.
- What I check
- I would map the last day with the old employer and the first day with the new one before relying on this option.
Time in the current job or continuous earlier work: Westpac, St George and ME Bank
- What that can mean for you
- These lenders may use earlier work as an alternative in selected cases, but the occupation, insurance position and permitted break between jobs can change the result.
- What I check
- I check the exact gap, whether mortgage insurance applies and whether the earlier role fits the lender's wording.
- What that can mean for you
- Bluestone no longer limits its Prime loans to PAYG applicants with no more than 2 employers in the last 12 months. I still need to explain your job changes in the application, along with any gap between jobs longer than 30 days. Bluestone asks for 12 months of work history.
- What I check
- I check your employment dates, current contract and payslips, then compare the rate and fees with other lenders.
Parental leave, study, redundancy and a planned break are different stories. Explain the gap accurately and support it where needed. Do not change dates to make the timeline look continuous.
If you have been promoted or moved internally, set out what changed: the role, salary, hours, start date and any new probation clause. Keep the original employment history alongside the variation or new contract so we can check what the bank needs explained.
If both applicants are changing jobs, prepare a separate employment timeline and income documents for each person. Tell us which changes have already happened and which are planned before relying on a combined borrowing figure.
When would waiting improve the application?
Waiting helps only when the next date gives a lender something it needs, such as your first pay or 3 months in the role. This timeline applies to a new permanent full time or part time PAYG job. Casual work has different history rules, which I cover in the casual employment guide.
| Evidence point | What it may establish |
|---|---|
| Contract signed | Some banks can consider a permanent PAYG contract before the first pay. |
| First pay | Confirms the job started and salary matches the contract. |
| 3 months | Some banks can consider the application once you reach this point. |
| 6 months | More banks may consider the job, although your earlier work could mean you do not need to wait. |
When would waiting improve the application?
Contract signed
- What it may establish
- Some banks can consider a permanent PAYG contract before the first pay.
First pay
- What it may establish
- Confirms the job started and salary matches the contract.
3 months
- What it may establish
- Some banks can consider the application once you reach this point.
6 months
- What it may establish
- More banks may consider the job, although your earlier work could mean you do not need to wait.
You don't necessarily need to wait until every point in this timeline. Some lenders can assess a permanent role from the first payslip. If you've started your new job but don't have payslips yet, NAB can use your contract or a letter from your employer instead. The answer depends on your circumstances and the lender's assessment.
Can you change jobs during a home loan application?
You can, but tell your broker or lender before you resign, sign a new employment contract or start the role. Pre-approval is not an unconditional promise. The lender may reassess income and employment before formal approval or settlement.
Before pre-approval
Tell the lender about your planned new job from the start and confirm which documents are available.
After pre-approval
The lender may recalculate what you can afford and review the new contract, employment type and start date.
After unconditional approval but before settlement
Do not assume the employment change is irrelevant. Ask before acting because ongoing conditions and verification can still matter.
A higher salary can improve borrowing power, but the bank still needs evidence it can use. A lower salary, fewer guaranteed hours or a move from PAYG to ABN can reduce the income counted. Check the change before you resign rather than trying to explain it after the bank reviews the application.
What can hold up the application?
Missing payslips, unclear contract terms or a change from PAYG employment to contracting can leave the lender needing more information. A gap between jobs or extra income without a documented history can also need an explanation.
Send through the signed contract and any available payslips together, with the dates of the old and new jobs. Flag anything that differs between the contract and actual pay so we can work out what needs explaining before lodging.
What should you have ready?
Your signed employment contract, including start date, base salary, hours and employment status.
The first matching payslip when available, plus recent bank credits if requested.
Earlier payslips, income statements or contracts that show you stayed in the same industry or moved into a similar role.
A simple timeline of employers, roles, employment types and gaps.
Documents explaining a break between jobs, if the lender asks.
Separate evidence for overtime, commission, allowances or bonuses.
For the broader employment picture, see the home loan job requirements guide. If your work history does not fit one standard label, the income and employment guide covers the other common situations.
Before you put the purchase on hold, check what waiting would change. Your first payslip, 3 months in the job or the end of probation might open up another lender. If waiting won't meet a lender's requirement or give you missing documents, send us your contract and work history so we can check whether you can apply now.
If another employment situation also applies, check the guidance for temporary or agency work. The work history and documents needed can differ for each situation.
Frequently asked questions
Related guides
- Start here
See how your new role and earlier work history may be assessed together.
- Related guide
How lenders check casual income, hours and work history.
- Related guide
How permanent hours and extra shifts may be assessed.
- Related guide
The difference between PAYG, day rate and ABN income.
- Related guide
What lenders check about your role, history and payslips.
- Related guide
What lenders check while you are still in your probation period.
Can you apply with your new job?
I can compare your contract, first pay, employment history and deposit with current lender rules, then tell you whether you can move now or what is still missing.
or call 1300 088 065
Any loan depends on the lender's assessment and approval.
This guide is general information only and does not consider your objectives, financial situation or needs. Lending policies and eligibility can change. Your full financial situation would need to be reviewed before any credit assistance or product recommendation.
Sources and review
How this guide was checked
Reviewed 17 September 2026 by Joshua Vecchio.
Lender comparisons checked 30 July 2026. Bluestone employment history rules checked 20 October 2026.
Lenders assess employment history and income differently. Confirm the current rules against your payslips, employment documents and full application before relying on a borrowing estimate.
References
Lender requirements can change. Confirm the rules and documents for your application before relying on an income or borrowing estimate.
Client examples are based on real situations. Names and identifying details have been changed.