First home buyer support includes cash grants, deposit guarantees, shared equity and duty concessions. Each has different eligibility rules, costs and application steps.
This guide explains which support may fit your purchase. A 2% or 5% deposit is only part of the budget: allow for buying costs and the lender's assessment too.
Australian Government 5% Deposit Scheme update
From 1 October 2025, the First Home Guarantee (FHBG) has been expanded:
No income caps: all first-home buyers (and eligible returning buyers) can apply
Unlimited places: no more waiting lists
Higher price caps: e.g. up to $1.5m in Sydney, $1.0m in Brisbane, $950k in Melbourne
Permanent residents eligible, alongside citizens
Still only 5% deposit required, with no LMI
Remember: this is a government guarantee to your lender, not a cash grant. You remain fully responsible for your loan and repayments.
What Grants Are Available In 2026?
As a first-time homebuyer, you can take advantage of the following government grants and schemes:
The Help to Buy Scheme (Officially Open)
The First Home Guarantee (Expanded to include regional buyers)
The Family Home Guarantee
The First Home Super Saver Scheme
Stamp Duty concessions and discounts.
Read on to learn more about these grants and how they can help you buy your first home.
Federal Help to Buy opened on 5 December 2025. It lets eligible buyers share the cost and ownership of a home with the government.
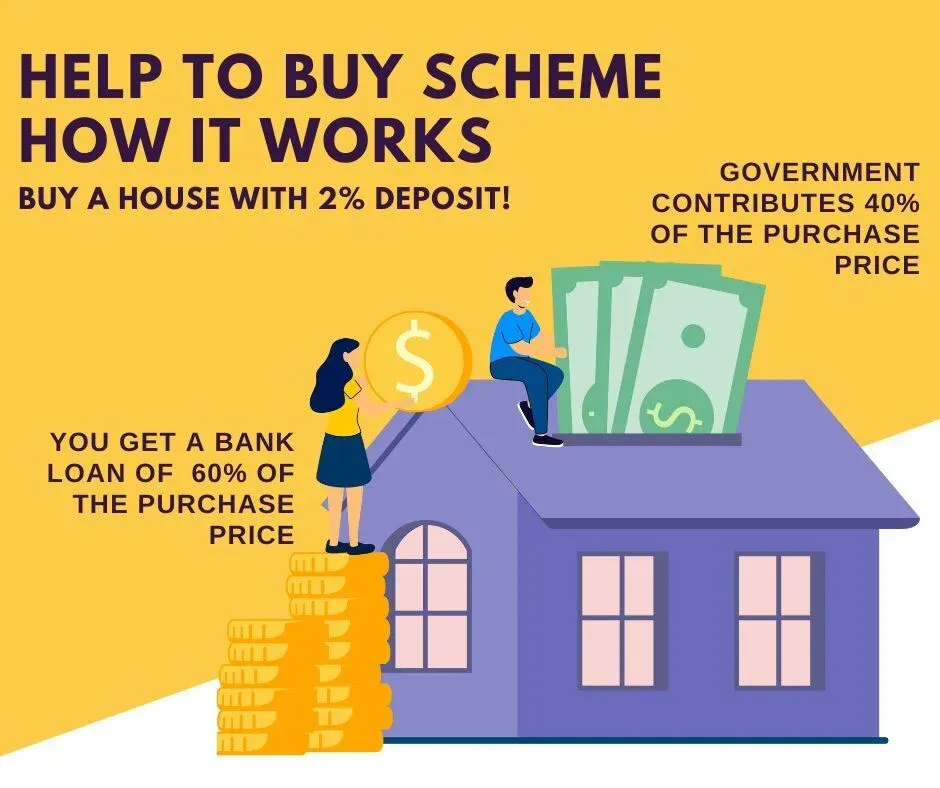
How does it work? Help to Buy is a shared equity scheme, meaning the government contributes a portion of the purchase price in exchange for a share of ownership (equity) in your property.
The government contributes up to 40% of the purchase price for a new home.
The government contributes up to 30% of the purchase price for an existing home.
This contribution reduces the size of the home loan you need to borrow, leading to a smaller deposit requirement (minimum 2%) and significantly lower monthly repayments. You do not pay rent on the government's share. The government's equity share is repaid when you sell the property or choose to buy them out over time.
Who is Eligible? The scheme is currently open to Australian Citizens (permanent residents are not currently eligible for this specific scheme). Key criteria include:
Current taxable-income limits are $103,000 for an individual and $165,000 for joint applicants or a single parent or single legal guardian, based on the previous financial year's ATO Notice of Assessment.
Property Ownership: You must not currently own any other land or property in Australia or overseas.
Residency: You must live in the property as your principal place of residence.
Price Caps: You must buy at or below the price cap for your region (e.g., $1.3m for Sydney, $1m for Brisbane/ACT, $950k for Melbourne).
Help to Buy has 10,000 places each year. Check current eligibility, participating lenders and availability before relying on a place. The government's contribution depends on your circumstances and is not automatically the maximum percentage.
Check Help to Buy's official rules and ask a participating lender how to apply. We can discuss your broader loan options; scheme participation does not confirm that a lender accepts broker applications.
2. The Australian Government 5% Deposit Scheme: buy with a small deposit and no LMI
The Home Guarantee Scheme (HGS) is a federal initiative administered by Housing Australia that helps you purchase a property sooner. It allows you to buy a home with a deposit as low as 2% or 5% without paying thousands of dollars in Lenders Mortgage Insurance (LMI).
With less than a 20% deposit, LMI may apply unless you qualify for a guarantee or lender waiver. The government deposit scheme provides a guarantee to the lender; it does not contribute cash to your deposit or reduce the amount you owe.
As of October 1, 2025, the scheme has been significantly expanded to help more Australians.
First Home Guarantee (FHBG)
Previously known as the First Home Loan Deposit Scheme.
This is the primary guarantee for first-home buyers.
Deposit: Purchase a home with as little as a 5% deposit.
Unlimited Places: As of late 2025, there are no longer any caps on the number of places available.
No Income Caps: The previous income limits ($125k/$200k) have been abolished. You can now apply regardless of your income level, provided you meet the other eligibility criteria.
Regional Access: The separate "Regional First Home Buyer Guarantee" has been merged into this scheme, simplifying the process for buyers in regional areas.
Eligibility:
You must be an Australian citizen or permanent resident aged 18+.
You must be a first home buyer OR have not owned a property in Australia in the last 10 years.
You can apply as an individual or jointly with a partner, friend, or family member.
Family Home Guarantee (FHG)
This guarantee provides targeted support for single parents and legal guardians to build a secure family home.
Deposit: Purchase a home with a deposit of just 2%.
Eligibility: You must be a single parent or single legal guardian with at least one dependent child. You do not need to be a first-home buyer, but you cannot own any other property at the time of settlement.
New Property Price Caps (Effective Oct 2025)
To be eligible, the property you purchase must be valued at or below the price cap for your region. These caps were significantly increased in October 2025 to reflect current market values.
State/Territory
Location
New Property Price Cap
NSW
Capital city & regional centres*
$1,500,000
Rest of state
$800,000
VIC
Capital city & regional centres*
$950,000
Rest of state
$650,000
QLD
Capital city & regional centres*
$1,000,000
Rest of state
$700,000
WA
Capital city
$850,000
Rest of state
$600,000
SA
Capital city
$900,000
Rest of state
$500,000
TAS
Capital city
$700,000
Rest of state
$550,000
ACT
All areas
$1,000,000
NT
Capital city
$750,000
NT
Rest of Territory
$600,000
For the complete regional definitions, use the official postcode tool and price-cap table. NSW includes additional designated regions beyond the older list. Confirm both the purchase price and lender-assessed value against the cap.
3. The First Home Super Saver (FHSS) Scheme: Save Your Deposit Faster
The First Home Super Saver (FHSS) Scheme allows you to save for your first home deposit inside your superannuation fund, helping you save faster thanks to tax concessions.
You can make eligible voluntary concessional or non-concessional contributions to super. The ATO determines the releasable amount: generally 85% of eligible concessional contributions, 100% of eligible non-concessional contributions and associated earnings, subject to the FHSS limits. Employer compulsory contributions do not qualify.
You can contribute up to $15,000 per financial year that counts towards the scheme.
Up to $50,000 of eligible contributions can count across all years. Your releasable amount depends on the contribution type, associated earnings and release tax.
The Application Process: Getting it Right The FHSS scheme process has recently become more flexible, but accuracy is still key.
Step 1: Make Voluntary Contributions. Arrange salary sacrifice with your employer or make personal after-tax contributions. (Note: Your employer's standard Super Guarantee payments do not count).
Step 2: Apply for an FHSS Determination. You must apply to the ATO for a determination to confirm how much you can withdraw.
Important Update: You can now request this determination after signing a contract, provided you do so before settlement (when you legally own the property).
Step 3: Request Your Release. Once you have your determination, submit a release request to the ATO. It typically takes 15 to 20 business days for funds to hit your account.
Note: You must request the release within 90 days of signing a contract.
Step 4: Notify the ATO. After signing your contract, you must notify the ATO within 90 days to avoid tax penalties.
Expert Tip: While the rules now allow you to get a determination after signing a contract, we strongly recommend applying before you start looking. This ensures you know exactly how much deposit you have available for bidding. A Hunter Galloway expert can help you project manage this timeline to ensure you don't miss the settlement deadline.
Deposit guarantees and shared-equity schemes use participating lenders. Cash grants often allow an application through an approved agent or directly to the revenue office; FHSS applications go through the ATO.
Quick Comparison: Lender Availability
Scheme
Application route
Australian Government 5% Deposit Scheme
A participating lender. Check its scheme and broker-channel availability.
Help to Buy
The current list includes Bank Australia, Commonwealth Bank, Teachers Mutual Bank, Health Professionals Bank, Firefighters Mutual Bank and UniBank.
Can I Submit Multiple Applications For Government Grants and Schemes?
You may combine compatible benefits if you meet each set of rules. For example, a state cash grant and duty concession may be used together. Help to Buy cannot be combined with another government shared-equity loan or guarantee for the same purchase. Confirm the combination before submitting applications.
Check to see if you are eligible for a home loan
Government Grants And Schemes For Each State
In Australia, each state has its own set of policies and programs for first-time home buyers, including:
It's worth mentioning that the FHOG is only accessible to first-time home buyers who are either buying or constructing a new home. If you're buying an established home, you will most likely not be eligible.
Grants to Buy First Home in Queensland (QLD)
Queensland currently offers some of the most generous incentives in the country.
Queensland's $30,000 grant continues for eligible contracts from 1 July 2026, for qualifying new homes valued below $750,000 including land. Check the current grant rules.
Regional Home Building Boost:Please note this previous $5,000 grant has expired and is no longer available.
Stamp Duty Concessions (Transfer Duty)
For eligible Queensland first home buyers, established homes attract $0 duty up to $700,000, with a reducing first home concession above that and below $800,000. The ordinary home concession may still apply at higher values.
For contracts from 1 May 2025, qualifying new homes and vacant residential land to build a first home have no property-value cap on the full duty concession. The former vacant-land caps do not apply to those contracts.
For transactions from 1 August 2026, claimants must be Australian citizens, permanent residents or specified foreign retirees, alongside the other conditions. Check QRO's established-home, new-home and vacant-land rules, then use our Queensland duty guide for worked examples.
The New "Boost to Buy" Shared Equity Scheme
Queensland Boost to Buy may contribute up to 30% for a new home or 25% for an existing home in exchange for a share of its value. Eligible applicants need at least a 2% deposit plus buying costs, and must satisfy the ownership, residence, property and lending requirements.
For the 2026 taxable-income year, the published limits are $155,000 for an individual and $232,000 for joint applicants or an individual with dependants. The property-price cap is $1 million.
As checked on 12 September 2026, Queensland Treasury reports that Round 2 South East Queensland allocations are exhausted, with regional allocations still available. Check current availability and eligibility. Applications go through Unity Bank.
Grants to Buy First Home in New South Wales (NSW)
First Home Owner Grant (FHOG)
If you are buying or building a new home, you may be eligible for a $10,000 grant.
Buying a new home: The purchase price must be $600,000 or less.
Building a new home: The total value (land + build) must be $750,000 or less.
Note: This grant is generally not available for established (existing) homes.
Stamp Duty Concessions (First Home Buyers Assistance Scheme)
NSW duty relief can save eligible first home buyers thousands of dollars. Check the current calculation in our NSW stamp duty guide.
Buying a Home (New or Existing):
Full Exemption ($0 tax): For homes valued up to $800,000.
Concessional Rate: For homes valued between $800,000 and $1,000,000.
Buying Vacant Land:
Full Exemption: For land valued up to $350,000.
Concessional Rate: For land valued between $350,000 and $450,000.
Shared Equity Home Buyer Helper
The NSW Shared Equity Home Buyer Helper pilot closed to new applications in 2024. It is not an open option for a new purchase. Eligible buyers can instead check the separate federal Help to Buy scheme. Existing NSW participants should follow their own scheme agreement.
Grants to Buy First Home in Australian Capital Territory (ACT)
For transactions from 1 July 2026, eligible ACT Home Buyer Concession Scheme buyers pay $0 conveyance duty, with no income threshold or property-value cap. This covers eligible homes and vacant residential land.
The 5 year property-ownership test still applies to all buyers and their domestic partners, subject to limited exceptions. At least one buyer must meet the residence requirement: generally moving in within 12 months and living there continuously for 12 months. Earlier contracts use the earlier rules. Check ACT Revenue's eligibility guidance before counting the saving in your deposit budget.
Disability Duty Concession Scheme
The ACT also removed the Disability Duty Concession Scheme's property-value cap from 1 July 2026. Its own eligibility conditions still apply. See ACT Revenue's 2026-27 Budget changes and confirm the applicable scheme before signing.
Grants To Buy First Home In Northern Territory (NT)
The Northern Territory currently offers the most generous first home buyer grant in Australia, designed to stimulate new housing construction.
HomeGrown Territory Grant (New Homes)
If you are buying or building a new home, you can receive a massive $50,000 grant.
Eligibility: You must be buying or building a new home that has not been lived in before.
Price Cap: There is no property price cap for this grant.
Dates: This boosted scheme has been extended and is available for contracts signed between 1 October 2024 and 30 September 2027.
Note: The previous $10,000 grant for buying an established (existing) home expired on 30 September 2025 and is no longer available.
Stamp Duty Exemption (House and Land Package Exemption)
A separate NT exemption can apply to qualifying house-and-land package contracts with a building contractor signed from 1 July 2022 to 30 June 2027. There is no price cap, but the contract structure and all eligibility conditions matter. At least one buyer must generally move in within 12 months of completion and live there for 6 continuous months. See NT Government's package exemption; a separate land purchase and building contract do not automatically qualify.
HomeBuild Access
This is a government-backed loan initiative to help low-to-middle income earners secure a home loan with a low deposit.
What it is: A low-deposit loan option for buying a new home or building on vacant land.
Price Limits: The property value must be under $475,000 (for 1-2 bedrooms) or $550,000 (for 3+ bedrooms).
FreshStart New Home Grant (For Non-First Buyers) Bonus:
If you are not a first home buyer (e.g., you owned a home years ago), you may still be eligible for the $30,000 FreshStart Grant if you build or buy a new home.
For more information and application forms, please visit the NT.gov.au website.
Grants To Buy First Home In South Australia (SA)
South Australia currently offers one of the most accessible schemes for buyers of new homes, having removed property price caps completely.
First Home Owner Grant (FHOG)
The Benefit: A one-off payment of $15,000.
Eligibility: You must be buying or building a new home (house, apartment, or townhouse) that has not been lived in before.
Price Cap: There is no property value cap for contracts signed on or after 6 June 2024.
Stamp Duty Relief (Abolished for New Homes)
South Australia has effectively abolished stamp duty for eligible first-home buyers purchasing a new home.
The Benefit: Pay $0 stamp duty.
Eligible Properties: New homes, off-the-plan apartments, house and land packages, or vacant land (to build a new home).
Price Cap: There is no property value cap, you can purchase a new home at any price point and still receive the exemption.
Note: This relief generally does not apply to established (existing) homes.
Important Eligibility Update (2025): For contracts signed on or after 13 February 2025, stricter rules apply: you and your partner must generally never have owned residential property in Australia before (even if you didn't live in it).
Tasmania still has a strong first home buyer grant, but the headline amount has changed and the stamp duty exemption has closed. Check both against your contract date.
First Home Owner Grant (FHOG)
The Benefit:$20,000 for a new home, for contracts entered into between 1 July 2026 and 30 June 2027.
No Price Cap: Tasmania does not apply a property value cap to the grant.
Eligibility: You must be buying or building a new home that has never been lived in. Established homes do not qualify for the grant.
Earlier contracts: The grant was $30,000 for a period before 1 July 2026. If you signed earlier, check which amount applies to your contract date with the State Revenue Office of Tasmania.
Stamp Duty Exemption (Established Homes): closed 30 June 2026
Tasmania's "Stamping Out Stamp Duty" policy gave first home buyers of established homes a 100% duty exemption, but it applied only to properties settling on or before 30 June 2026, and that window has now closed. The terms below applied inside it. If you are buying now, confirm the concession currently on offer with the State Revenue Office of Tasmania before you budget: do not assume a full exemption.
The Benefit: You paid $0 stamp duty (100% exemption).
Eligibility: You had to buy an established (existing) home, not a new build.
Price Cap: The property value had to be $750,000 or less.
"MyHome" Shared Equity Program
This state-backed scheme helps you buy a home with a deposit of just 2%.
Contribution: Homes Tasmania can contribute up to 40% of the price, capped at $300,000, for a new home or house-and-land package. For an existing home, the limit is 30%, capped at $150,000. In each case, the lower limit applies. See the MyHome contribution rules.
Price Caps:
New Homes: $800,000
Existing Homes: $750,000
MyHome has income and financial-asset tests, with specified exemptions. The published financial-asset cap is $124,268 from 1 July 2026. Check Homes Tasmania's full eligibility rules, including any exemption that applies to you.
Victoria offers specific grants for buying new homes, but the landscape has changed significantly with the closure of the state's shared equity fund in late 2025.
First Home Owner Grant (FHOG)
The Benefit: A $10,000 grant.
Eligibility: You must be buying or building a new home that has never been lived in before.
Price Cap: The property value must be $750,000 or less.
Caution: Unlike some other states, this grant is not available for established (existing) homes.
Stamp Duty Exemption & Concessions
Victoria provides generous stamp duty relief for first-home buyers, which can save you up to $31,070.
Full Exemption ($0 tax): If your home (new or established) is valued at $600,000 or less, you pay zero stamp duty.
Concession (Discount): If your home is valued between $600,001 and $750,000, you pay a reduced rate on a sliding scale.
Victorian Homebuyer Fund (VHF): [CLOSED]
Status: This shared equity scheme closed to new applications on 10 September 2025.
Alternative: Victorian buyers looking for shared equity support should now look to the Federal Help to Buy Scheme, which opened in December 2025 (see the Help to Buy section above).
Off-the-Plan Concession (Extended)
If you buy an apartment or townhouse "off-the-plan," you may be eligible for a stamp duty concession that deducts construction costs from the purchase price.
Update: This temporary concession was recently extended until 21 April 2027.
Grants to Buy First Home in Western Australia (WA)
Western Australia recently updated its stamp duty thresholds to help first-home buyers keep up with rising property prices.
First Home Owner Grant (FHOG)
The Benefit: A $10,000 grant.
Eligibility: You must be buying or building a new home that has never been lived in before.
Price Caps:
Perth & South West: Property value up to $800,000 for transactions entered into on or after 7 May 2026 (raised from $750,000).
North West (North of 26th parallel): Property value up to $1,000,000.
Stamp Duty (First Home Owner Rate)
For eligible WA transactions from 7 May 2026, homes have a $600,000 full-exemption threshold and a concessional band from $600,001 to $800,000. Vacant land has a $450,000 full-exemption threshold and a concessional band from $450,001 to $550,000.
WA's off-the-plan concession has been extended to eligible contracts through 30 June 2028, with expanded property coverage. The contract date, property type, value and construction stage determine the concession. Check RevenueWA's current conditions before you sign.
The Pros and Cons Of Each First Home Buyer Grant
A cash grant can reduce your upfront costs. Shared equity reduces the loan but gives the government a share of the home's value. A deposit guarantee may remove LMI while leaving you responsible for the full loan.
Compare what each option saves now with the repayments, eligibility rules and obligations you will take on.
Quick Comparison: Benefits vs. Risks
Scheme
Potential benefit
What to allow for
Help to Buy
Smaller loan with government shared equity and a minimum 2% deposit
You share changes in the home's value and must meet ongoing income and occupation obligations. Use an approved lender.
Boost to Buy
Queensland shared equity with a minimum 2% deposit
Limited allocations, an approved lender and obligations to repay the government's share.
5% Deposit Scheme
Eligible borrowers avoid LMI without giving government an equity share
A smaller deposit means a larger loan. Lending, property-price and occupation requirements apply.
FHSS
Eligible voluntary super contributions can help fund a first home
Contribution limits, tax treatment and release deadlines apply. It is your saved money, not a cash grant.
State home-owner grant
A cash contribution to an eligible purchase or build
Property, ownership and occupation rules differ. Check when it is paid before relying on it for settlement.
Frequently Asked Questions About Grants To Buy First Home
Some benefits can be combined if you meet each program's rules. For example, an eligible state cash grant may be used with Help to Buy. Confirm the grant amount and payment date, and check the lender will accept that combination before including it in your deposit.
When you sell the property, you must repay the government's share of the home's current market value. If the government contributed 30% to buy the home, they take 30% of the sale proceeds. This means if your home has gone up in value, the government shares in that profit.
No, the Victorian Homebuyer Fund closed to new applications in late 2025. It has been effectively superseded by the Federal Help to Buy scheme, which is now active and available to Victorian buyers with similar benefits.
As of 1 October 2025, the specific "Regional First Home Buyer Guarantee" has been merged into the expanded First Home Guarantee (FHBG). Regional buyers now access the main FHBG, which offers unlimited places and higher price caps (e.g., up to $1 million in QLD regional centres). You generally need a 5% deposit and must not have owned property in the last 10 years.
Start with the official scheme rules for your location and property. Hunter Galloway can discuss your loan and deposit budget and identify options to investigate further.
Check which benefits can be combined before applying. Cash grants and duty concessions may work together, but you cannot assume every guarantee, shared-equity scheme and grant can be stacked.
The main types of support are:
Help to Buy: (Federal) Shared equity with 2% deposit.
Home Guarantee Scheme: (Federal) 5% deposit with no LMI.
First Home Owner Grant: State or territory cash support for eligible new homes. Amounts vary, including the NT's $50,000 HomeGrown Territory Grant.
Stamp Duty Exemptions: (State) Tax waivers up to certain price caps.
Boost to Buy: (QLD only) State-based shared equity.
Help to Buy may contribute up to 40% for a new home or 30% for an existing home. You need at least a 2% deposit and lender approval. The government shares the property's gains or losses when its share is repaid, under the scheme agreement; you do not pay rent on that share.
The Australian Government 5% Deposit Scheme provides an eligible lender with a guarantee, usually up to 15% of the property value for the first-home pathway. It is not cash added to your deposit. You remain responsible for the full loan, and must meet the scheme and lender requirements.
Eligible single parents or single legal guardians with dependent children can apply with a minimum 2% deposit and no LMI. There is no income cap. You do not need to be a first home buyer, but cannot own another property interest once the new home settles. Scheme and lender requirements still apply.
FHSS lets eligible buyers release qualifying voluntary super contributions and associated earnings. Up to $15,000 of contributions per year and $50,000 overall can count. Generally, 85% of eligible concessional contributions and 100% of eligible non-concessional contributions are releasable, plus associated earnings. Tax can apply on release.
Strict Price Caps: You may be limited to cheaper properties that don't suit your needs.
Equity Sharing: With schemes like Help to Buy, you give up a percentage of your future profits.
Paperwork: Schemes like the FHSS require precise timing; get it wrong, and your funds can be locked away.
The application route depends on the benefit. Government guarantees and shared equity use participating lenders; cash grants can often be lodged through an approved agent or directly with the revenue office. Apply for FHSS through the ATO.
A broker can check loan options, help with budgeting and explain the relevant scheme pathways. Ask whether the particular scheme is available through the broker or requires a direct lender application.
Bring your savings, price range and the state you are buying in. Our team can check the loan alongside the grants and concessions you may qualify for.
To chat about your deposit, lending and first home ownership options, please give us a call on 1300 088 065 or book a free assessment online to see how we can help.
Our team of home loan experts is here to help you buy a home in Australia.