

Replacing kitchen cupboards and adding another level can need very different funding. Start with what you want to change, what it will cost and when the people doing the work need to be paid.
Compare 2 figures: the money available for the renovation and the full cost of finishing it. Getting a loan approved helps, but the project also needs enough cash for deposits, excluded work and changes along the way.
Which renovation finance option fits the work?
Start with the scope and payment schedule. You do not automatically need a separate product called a renovation loan.
| What you are planning | Funding worth comparing | What I would check first |
|---|---|---|
| Painting, flooring or other cosmetic work | Savings, available redraw or a home loan increase | Whether you can pay the invoices and still keep a household cash reserve |
| A kitchen or bathroom update | Savings or an increase to the existing loan; construction finance if the scope requires it | Whether the work affects the structure, needs approvals or relies on the finished value |
| An extension, house lift or major structural renovation | A construction loan with payments released in stages | The building contract, accepted finished value and cash contribution |
| Demolishing and rebuilding | A construction arrangement that covers the existing mortgage and rebuild | Approval and the lender's written demolition requirements before the house comes down |
| A small project without enough home equity | A personal loan, a smaller project or waiting to save more | The repayments, fees and total cost over the proposed term |
Which renovation finance option fits the work?
Painting, flooring or other cosmetic work
- Funding worth comparing
- Savings, available redraw or a home loan increase
- What I would check first
- Whether you can pay the invoices and still keep a household cash reserve
A kitchen or bathroom update
- Funding worth comparing
- Savings or an increase to the existing loan; construction finance if the scope requires it
- What I would check first
- Whether the work affects the structure, needs approvals or relies on the finished value
An extension, house lift or major structural renovation
- Funding worth comparing
- A construction loan with payments released in stages
- What I would check first
- The building contract, accepted finished value and cash contribution
Demolishing and rebuilding
- Funding worth comparing
- A construction arrangement that covers the existing mortgage and rebuild
- What I would check first
- Approval and the lender's written demolition requirements before the house comes down
A small project without enough home equity
- Funding worth comparing
- A personal loan, a smaller project or waiting to save more
- What I would check first
- The repayments, fees and total cost over the proposed term
A pool or granny flat also needs its own scope, approvals and funding check. The name of the project does not tell us how a lender will treat it.
For a kitchen project, our kitchen renovation guide covers planning and costs in more detail.
Savings, offset and redraw
Using savings can avoid a new credit application, but keep money aside for household bills and unexpected work. If those savings are in an offset account, taking them out can increase the interest charged on your mortgage.
Redraw is different. It lets you access eligible extra repayments already made to a loan, subject to that loan's terms. Check the amount actually available and how using it changes your balance and repayments before promising money to a contractor.
Increasing or refinancing the home loan
An increase with your current lender is worth checking first. If it cannot provide the amount or arrangement you need, compare a refinance with another suitable lender.
Keep the comparison like for like. Include fees, the remaining loan term and the advertised rate. Moving a loan with 22 years left back to 30 years may lower the minimum repayment while leaving you paying interest for longer. Our home equity guide explains how borrowing against the property works.
Personal loans, credit cards and a line of credit
A personal loan can be an option for a smaller job, but the shorter term can mean higher monthly repayments. Compare the actual offer and total amount repayable with the home loan option. A lower mortgage rate does not automatically make a renovation cheaper if you repay it over decades.
A line of credit allows borrowing and reborrowing within an approved limit. Check its rate, fees and repayment requirements against an ordinary loan increase. Access to money is useful only if the debt has a workable repayment plan.
How much can you borrow for renovations?
The lender checks what you can afford and how much it is prepared to lend against the property. Equity helps with the second question; it does not replace the income needed to repay the loan.
Equity is the property's value minus the debt secured against it. You usually cannot borrow every dollar of that difference.
Example: adding $100k to the loan
| Item | Example amount |
|---|---|
| Current property value accepted by the lender | $800k |
| Existing home loan | $500k |
| Proposed extra borrowing for renovations | $100k |
| Total proposed loan | $600k |
| Total loan as a share of the property value | 75% |
Example: adding $100k to the loan
Current property value accepted by the lender
- Example amount
- $800k
Existing home loan
- Example amount
- $500k
Proposed extra borrowing for renovations
- Example amount
- $100k
Total proposed loan
- Example amount
- $600k
Total loan as a share of the property value
- Example amount
- 75%
Here, the proposed loan is 75% of the current value, so the extra $100k does not rely on the renovation lifting the valuation. The lender must still approve the work and assess income, debts and expenses. Fees and any other secured debt also need to be allowed for.
This is an example, not a borrowing limit or loan approval. The equity calculator can help you make a first estimate using your own figures.
Will the bank use today's value or the finished value?
A loan increase for smaller work may use the home as it stands today. With construction finance, the lender may arrange a valuation of the home as if the approved renovation were finished.
The finished valuation is not automatically the current value plus what you spend. A $300k renovation might add only $180k to the value accepted by the lender. That can leave you needing more cash even when the repayments look affordable.
Check the likely valuation before committing to a design that only works financially if every renovation dollar adds a dollar of value. Our property valuation guide explains why the bank's figure matters.
Do all banks use the same renovation rules?
The proposed work and lender determine the funding requirements. Check both before relying on a dollar threshold.
| Lender example | What its public guidance says | What that means for your decision |
|---|---|---|
| CommBank | Describes several funding choices, including redraw, refinancing, personal loans and construction finance | Choose the arrangement around the job and your finances |
| ANZ | Directs structural renovations towards construction finance | A relatively small structural job should not be described as cosmetic just to simplify the application |
| Westpac | Discusses loan increases for renovations costing $250k or less, subject to its requirements; its top-up guidance excludes work involving construction | The amount is only part of the assessment; check the work itself |
| NAB | Describes equity, redraw, refinance, personal loans and staged construction lending | Compare the available funds, repayment term and how the loan pays for the work |
Do all banks use the same renovation rules?
- What its public guidance says
- Describes several funding choices, including redraw, refinancing, personal loans and construction finance
- What that means for your decision
- Choose the arrangement around the job and your finances
- What its public guidance says
- Directs structural renovations towards construction finance
- What that means for your decision
- A relatively small structural job should not be described as cosmetic just to simplify the application
- What its public guidance says
- Discusses loan increases for renovations costing $250k or less, subject to its requirements; its top-up guidance excludes work involving construction
- What that means for your decision
- The amount is only part of the assessment; check the work itself
- What its public guidance says
- Describes equity, redraw, refinance, personal loans and staged construction lending
- What that means for your decision
- Compare the available funds, repayment term and how the loan pays for the work
When does a renovation need construction finance?
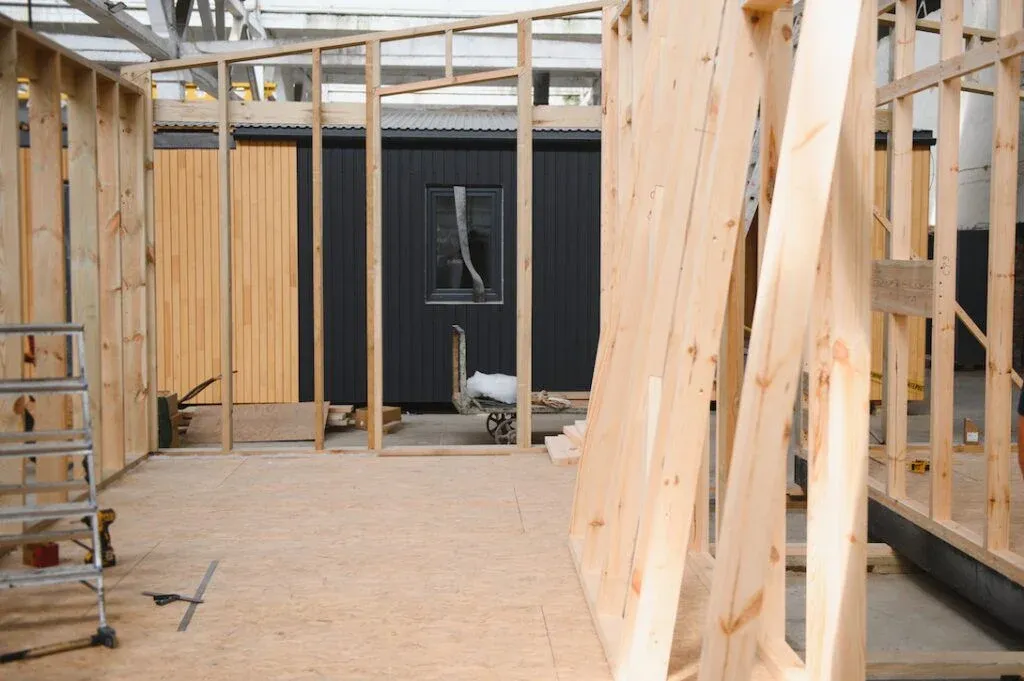
Structural work or a project funded against the expected finished value may require construction finance. Instead of giving you the whole building amount upfront, the lender releases money as agreed stages are completed and its payment conditions are met.
The practical sequence is:
- Step 1Prepare the scope, quotes and complete budget
- Step 2Check borrowing capacity and which value the lender will use
- Step 3Have the contract reviewed, then supply the signed documents required for formal approval
- Step 4Clear the conditions for work and payments to begin, including your cash contribution
- Step 5Submit each progress claim through the agreed process and meet the final-payment requirements at completion
The stages and percentages must fit your contract and lender. There is no single payment schedule for every renovation, and a loan below $100k does not automatically mean you can control all payments yourself.
Your contribution may have to be paid before the lender starts releasing funds. Keep deposits already paid, cash still available and loan money separate so the same dollars are not counted twice.
Interest on progressively released funds generally grows as more money is drawn. Check the repayments during the renovation and once the full loan is in place. The construction finance guide explains the complete approval-to-handover process.
What if the work has already started?
Tell the broker or lender immediately. An unfinished property, changed contract or altered payment schedule can change the assessment.
If you already have a construction loan, the broker and lender managing it are the first people to contact about a live payment problem. Send the updated cost to finish, variations, remaining loan funds and next invoice date. Do not assume another lender can take over midway through the work.
How do you budget for the whole renovation?
Start with an itemised scope and compare quotes for the same work. A cheaper quote may leave out something you still need to pay for.
Alongside the builder's price, allow for design and engineering, approvals, demolition or asbestos work where relevant, service changes, separately arranged trades and temporary accommodation. Check whether landscaping, fencing, appliances and window coverings are included.
A prime-cost allowance covers an item whose final selection or price is not yet settled. A provisional sum estimates work whose cost cannot be fixed at that point. Ask the builder to identify these amounts and have your solicitor explain how changes affect the contract.
Our fixed-price building contract guide explains how allowances and exclusions affect the cash you need.
Separate work needed to finish the home from optional upgrades. That gives you something to change if the budget becomes tight, rather than finding the cash is gone before essential work is complete.
Keep a cash reserve that matches the project
A buffer should reflect the uncertain parts of your renovation. Ask the builder which costs remain estimates and test what happens if they rise or the job takes longer.
A fixed percentage does not make every project safe. Old services, difficult access or work concealed behind walls may need specialist investigation before you can set a useful allowance.
The Australian Government's Your Home renovation guide is a useful starting point for planning the work. A builder, designer or other qualified professional can help identify what the quote needs to cover.
If you are weighing up renovation against starting again, compare the funding and demolition sequence in our knockdown rebuild guide.
Where can you trim the budget?
Consider retaining a workable layout, staging optional cosmetic work and comparing materials before ordering. Check with the relevant professional before changing structural work or removing something needed for approval, safety or completion.
Do not budget on doing licensed trade work yourself. Saving on paint or fittings is different from taking responsibility for electrical, plumbing or structural work without the required qualifications and approvals.
What should you confirm before committing?
Start the finance discussion while the plans can still change. Approval timing depends on the application, valuation, contract and outstanding documents; a promised 1 or 2 week turnaround is not a reliable project plan.
For an initial discussion, bring the current mortgage balance, rough property value, renovation scope, budget and savings. That lets us check whether the main issue is equity, repayments or the way the work needs to be funded.
For a construction application, the lender may also need plans, specifications, the building contract, payment schedule, approvals, builder details and insurance evidence. Confirm which documents are needed for approval and which are required before the first payment.
Can you manage the trades yourself?
Owner-builder work needs a separate lending check. Do not assume a construction approval based on a licensed builder will still work if you decide to manage the trades yourself.
In Queensland, an owner-builder permit is generally required to undertake or supervise a project valued above $11,000, including GST. Permit eligibility and the lender's approval are separate. Check the QBCC owner-builder requirements before work begins. QBCC also explains the limits on DIY work and home warranty protection.
Could energy-efficient work get a different loan offer?
It is worth checking eligible solar, batteries or other energy upgrades separately. Some lenders have specific products or discounts, with limits on eligible purchases and installation evidence. A discount for selected equipment is not automatically a discount on the whole renovation or mortgage.
For example, CommBank publishes eligibility criteria for energy-efficient personal-loan purchases. Compare the amount, term and total cost with your other options before ordering. Our green home loan guide covers the broader question.
Questions about renovation loans
Experience and sources
How this guide was checked
Public guidance checked on 22 September 2026. Each lender still assesses the borrower, property and proposed work under its current requirements. Published lender guidance can change. Confirm the current requirements with the lender assessing your project before relying on an example.
Jayden Vecchio is a mortgage broker and director at Hunter Galloway. Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328. He holds a Certificate IV in Finance & Mortgage Broking and a Diploma of Financial Planning.
Sources
General information only. Lending is subject to the lender's assessment of your circumstances, property and proposed work. Obtain legal, tax and building advice where needed before signing a contract or starting work.
Related guides
- Related guide
How construction finance works
Read guide - Related guide
Home equity loans
Read guide - Related guide
Reasons to refinance
Read guide - Related guide
Building a house in Brisbane
Read guide - Calculator
Compare mortgage repayments
Open calculator - Calculator
Check your loan-to-value ratio
Open calculator - Related guide
Fixed-price building contracts
Read guide - Related guide
Construction cost overruns
Read guide - Related guide
Knockdown rebuild finance
Read guide
Work out how you can fund the renovation
Send us your current loan balance, renovation scope, rough budget and cash available. We'll compare the amount you could access, how the money would be paid and the repayments, then explain what needs confirming before you commit.
or call 1300 088 065
Your full financial situation would need to be reviewed before any offer or product is accepted.