


The building contract is only one part of your budget. You may also need to pay for land, site work, rent during construction and items the builder has left out.
The order is:
- Step 1Add up the land, build and other costs
- Step 2Check the loan amount, property value and cash you will contribute
- Step 3Complete the loan and building requirements before work starts
- Step 4Request payments as the agreed stages are finished
- Step 5Complete the final checks and confirm your ongoing repayments
1. Check the whole project cost before committing
Put the full cost beside the money available to pay it. Include costs outside the building contract and cash you need to keep for everyday life.
Your budget may need to cover:
- the land purchase, or the mortgage already against land you own;
- the building contract, site preparation and any demolition;
- excluded work such as retaining walls, a driveway, fencing or landscaping;
- design, engineering, approvals, connections and other professional costs;
- loan and purchase costs;
- rent, storage and moving expenses; and
- money kept aside for changes or delays.
A fixed-price contract does not make every item on that list a fixed cost. Ask the builder to identify exclusions and allowances, and have your solicitor explain the contract before you sign. QBCC explains the different contract arrangements.
There is no single cash buffer that is enough for every project. The amount should reflect the work, uncertain costs and how long you could carry your housing expenses if completion is delayed. Keep it separate from money already committed to the deposit or next building stage.
Buying land or using land you already own
If you are buying land, check both the land purchase and proposed build before relying on a budget. Land settlement may happen well before construction starts. A land-only pre-approval does not establish that the full project will qualify.
If you already own land, its value may help support the borrowing. But equity is not the same as cash in your account. Land worth $500k with $250k owing has $250k of equity; that does not mean the lender will release another $250k for the build. It still checks the finished value, total debt and what you can afford.
Our vacant land loan guide covers buying the block. If you want to borrow against another property, the home equity guide explains that separate decision.
The builder's deposit and your loan contribution are different
The builder's deposit is an early payment under the building contract. Your loan contribution is the money the lender requires you to put towards the project. One does not automatically satisfy the other.
For Queensland domestic building contracts of $20,000 or more, the usual maximum builder deposit is 5%. A limited exception permits up to 20% where substantial customised work or prefabrication off-site represents more than 50% of the contract price. Check the contract and applicable exception rather than assuming a larger request is standard. QBCC deposit guidance
Ask when you must use your own funds and keep the receipts. Westpac, for example, requires agreed borrower contributions before its first progress payment. Do not assume the bank will reimburse an early payment unless it has confirmed that arrangement.
2. Get the property, contract and loan checked together
The lender needs to assess both you and the proposed home. Your income may support the repayments, but the valuation or an incomplete budget can still limit the loan.
Banks regulated by APRA generally assess repayments at least 3% above the actual rate to check whether you could manage higher repayments. This assessment rate does not change the interest rate you pay. APRA sets out the minimum buffer in its lending standard.
The valuation estimates what the property should be worth when the approved work is finished. The finished value can be lower than the land and build cost. The lender decides which value and cost limits it will use; the valuer does not approve your loan amount.
If there is a gap, we need to identify whether it comes from the valuation, the amount you can afford to borrow, or costs the loan does not cover. Each calls for a different response. Better plans or evidence may support a valuation review, but spending more on the build does not guarantee a higher value.
Which documents will you need?
Start with a budget and preliminary building information. For a formal decision and permission to begin drawing funds, the lender may need the following:
| Document | What it helps establish |
|---|---|
| Income, expenses, debts and savings records | Whether you can afford the loan and provide your contribution |
| Land contract or current loan statement | What you are buying or what is already owing |
| Building contract and payment schedule | The agreed price, work, timing and amounts due |
| Plans and specifications | The size, layout, finishes and materials being valued |
| Quotes for work outside the contract | Whether the full project is covered |
| Builder details, insurance and required approvals | Whether the project can proceed and the lender can release funds |
Which documents will you need?
Income, expenses, debts and savings records
- What it helps establish
- Whether you can afford the loan and provide your contribution
Land contract or current loan statement
- What it helps establish
- What you are buying or what is already owing
Building contract and payment schedule
- What it helps establish
- The agreed price, work, timing and amounts due
Plans and specifications
- What it helps establish
- The size, layout, finishes and materials being valued
Quotes for work outside the contract
- What it helps establish
- Whether the full project is covered
Builder details, insurance and required approvals
- What it helps establish
- Whether the project can proceed and the lender can release funds
Requirements can differ between the initial assessment and first payment. Westpac's published checklist, for example, requires a signed and dated contract at application. It may accept plans awaiting approval initially, but requires approved plans before the first builder payment. There is no Queensland-wide rule that every lender will give formal construction approval using an unsigned contract. Westpac construction guide
Clear the conditions before building or demolition
Loan approval, permission to start building and release of the first payment are separate steps. Check the remaining loan conditions, building approvals, insurance, your contribution and the first payment process before work starts.
For a knockdown rebuild, confirm the lender's position before removing the existing house. Demolition changes the property supporting the mortgage. The bank may need to consider its value now, the land after demolition and the finished home, as well as where you will live during construction.
Your solicitor handles contract advice, the builder and certifier handle building requirements, and the lender controls loan approval and payment conditions. We help put the finance requirements in the right order.
3. Pay for completed stages, not the whole build upfront
Once the loan is ready to use, construction money is released in instalments called progress payments or drawdowns. The payment schedule must fit both the building contract and the lender's approval.
Typical stages include the base or slab, frame, enclosed or lock-up stage, fixing or fit-out, and completion. The names, work included and percentages can vary. Do not treat one example schedule as the required HIA schedule for every lender or every build. ANZ's progress-payment explanation
What happens after the builder sends an invoice?
You check the completed stage and amount against the contract, then provide the invoice and any required signed authority to the lender. It may arrange an inspection before releasing the accepted amount, usually to the builder.
A bank inspection supports the bank's lending decision. It does not replace your own building inspection or resolve a disagreement about defects. NAB explains the purpose of its construction inspections.
Send complete documents promptly and confirm the expected processing time with the lender managing the build. A missing signature, inspection or site access can hold up payment. There is no universal promise that every stage will be paid within 5 business days.
Example: paying for a $400k build
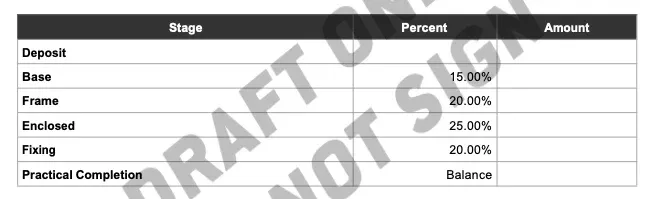
This example retains the stages in the sample schedule below. It assumes a $400k building contract, a $20k builder deposit paid from your savings and a $380k construction loan for the remaining work. It excludes land debt, fees, other contributions and work outside the contract. It is not a recommended payment schedule or an indication that a lender will fund this proportion of your project.
| Payment | Share of contract | Payment due | Construction loan drawn so far |
|---|---|---|---|
| Deposit, paid from savings | 5% | $20,000 | $0 |
| Base | 15% | $60,000 | $60,000 |
| Frame | 20% | $80,000 | $140,000 |
| Enclosed | 25% | $100,000 | $240,000 |
| Fixing | 20% | $80,000 | $320,000 |
| Completion | 15% | $60,000 | $380,000 |
Example: paying for a $400k build
Deposit, paid from savings
- Share of contract
- 5%
- Payment due
- $20,000
- Construction loan drawn so far
- $0
Base
- Share of contract
- 15%
- Payment due
- $60,000
- Construction loan drawn so far
- $60,000
Frame
- Share of contract
- 20%
- Payment due
- $80,000
- Construction loan drawn so far
- $140,000
Enclosed
- Share of contract
- 25%
- Payment due
- $100,000
- Construction loan drawn so far
- $240,000
Fixing
- Share of contract
- 20%
- Payment due
- $80,000
- Construction loan drawn so far
- $320,000
Completion
- Share of contract
- 15%
- Payment due
- $60,000
- Construction loan drawn so far
- $380,000
After the base payment, $80k has gone to the builder, but only $60k came from this construction loan. That distinction matters when you calculate interest and the money still available.
4. Budget for rising interest and the finished repayment
Interest is generally calculated on the amount already drawn. The unused portion of the approval has not yet been borrowed. Many construction loans have interest-only repayments during the build. That means the required payment covers interest without reducing the amount you owe.
Using the $400k build example above at an assumed 6% a year, interest rises as more of the construction loan is drawn.
- $300
After base
$60k drawn
- $1,200
After enclosed
$240k drawn
- $1,900
After completion
$380k drawn
These estimates use annual interest divided by 12. They are illustrative and do not quote a current rate. Actual interest depends on daily balances, timing, fees and your loan terms.
Any separate land loan or existing mortgage also needs to be included. The construction figure alone may be only part of your monthly housing cost.
If you will rent during the build, allow for rent alongside increasing loan interest, plus extra rent if the build runs late. Then check the repayment that applies after completion. Do not decide that the project is affordable using only the small payment near the start.
Completion does not trigger the same repayment change at every bank. CommBank switches to the product and repayment type selected at application after the final progress payment. NAB says its loan becomes principal and interest when the interest-only period ends, with an earlier switch available by contacting the bank. Check your own loan documents. CommBank, NAB
You can use our mortgage repayment calculator to compare the finished repayment with your current housing costs.
5. Recheck the money before changing the build
An agreed change to the building contract does not automatically increase the loan. Before approving extra work, check its price, when payment is due and how you will fund it.
Add up the remaining stages, variations and work outside the contract. Compare that total with your unused approved loan and cash still available, counting each amount once. If the loan needs to increase, the lender may need to reassess your income and the finished value.
Our construction cost-overrun guide shows how to compare the money left with the full cost to finish.
NAB's construction guidance makes the limit clear: if it cannot provide additional funding for an overrun, you need to cover the extra cost. A builder's approval of a variation does not establish that funding.
If a payment is delayed
Contact the broker or lender managing your construction loan. Find out whether it is waiting for a document, inspection, your contribution, a corrected invoice or a decision on a variation. That tells you what needs to happen next.
If the invoice is disputed, get building or legal advice as well. A bank processing delay does not change your contractual payment obligations by itself.
If the builder stops work or becomes insolvent
Start with your existing lender, solicitor and the relevant state insurance or building authority. Confirm what has been paid, what remains unfinished and the approved money still undrawn.
In Queensland, seek advice before terminating the contract, appointing a replacement builder or restarting work. QBCC's non-completion process has requirements that can affect a claim. An insurance payment or loan increase is not automatic. QBCC non-completion guidance
If your builder collapses, our guide explains the first calls to make and the information to collect.
The unused loan balance is not cash you can freely hand to another builder. The lender needs to consider the revised work and funding plan. Do not assume a partly completed build can simply be refinanced elsewhere.
6. Complete the final checks before relying on handover
Ask for the final-payment checklist before the builder reaches completion. The lender may require a final inspection, insurance and completion documents appropriate to your state and project.
Check the work and any outstanding items with your building adviser. Practical completion, bank payment and your rights under the building contract are related, but they are not the same decision.
Confirm the final amount being drawn, what happens to any unused loan funds, when your next repayment is due and whether its amount or type will change. That is the point to update the household budget for living in the completed home.
For the broader land, builder and local planning sequence, see building a house in Brisbane.
Construction finance FAQs
Experience and sources
How this guide was checked
Public construction and building guidance checked on 22 September 2026. Your lender's approval and contract determine the requirements for your project. Published lender guidance can change. Confirm the current requirements with the lender assessing your project before relying on an example.
Jayden Vecchio is a mortgage broker and director at Hunter Galloway. Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328. He holds a Certificate IV in Finance & Mortgage Broking and a Diploma of Financial Planning.
Sources
Hunter Galloway Finance Pty Ltd, Credit Representative 476903, is authorised under Australian Credit Licence 389328. General information only, not a credit assessment, valuation, building inspection, legal advice or promise of approval.
Related guides
Check whether your construction plan is covered
Send us the land details, building quote or contract, costs outside the contract and cash you have available. We can check the funding and expected repayments before you commit to the next step.
or call 1300 088 065
Your full financial situation would need to be reviewed before any offer or product is accepted.