

The short answer
Some lenders can use child support as income. I check what agreement supports it, how long the payments have arrived, how long they are likely to continue and what other income you receive.
The amount a lender accepts may differ from the payment reaching your account. A private arrangement without formal paperwork needs a closer look. Kirsty's story below shows why it can be worth checking before you assume the answer is no.
Client story
Kirsty's loan increased by about $130k
Her income: Kirsty earned $90k a year and had been receiving $1,000 a week in private child support since November 2025. The payments had recently increased to $1,100 a week.
The document gap: There was no Child Support Agency assessment or final agreement yet. She was working with her lawyer, but she wanted to know whether she could buy before that process was finished.
The first assessment: The first calculation left the child support out. That put the home she wanted beyond her budget, even though the payments had arrived every week for more than 6 months.
What we did: I found a lender willing to look at the private arrangement as an exception. We showed more than 6 months of clear weekly deposits, the amount received and the wider separation position. Kirsty also cleared her remaining HECS debt.
The result: Her loan was approved at about $790k, lifting her buying budget to around $1.275m. She was able to secure the home she wanted in Brisbane's inner east.
The difference: That was about $130k more borrowing room. The change reflected the whole application, including the child-support exception and clearing her HECS debt.
Why this was an exception: This was a lender-specific exception. Kirsty's regular deposits gave us evidence to present, but 6 months of payments does not guarantee that another private arrangement will be accepted.
What changed in Kirsty's application
- About $660k
First calculation without child support
Loan amount
- About $790k
Approved loan after the exception and clearing her HECS debt
Loan amount
When can child support count as income?
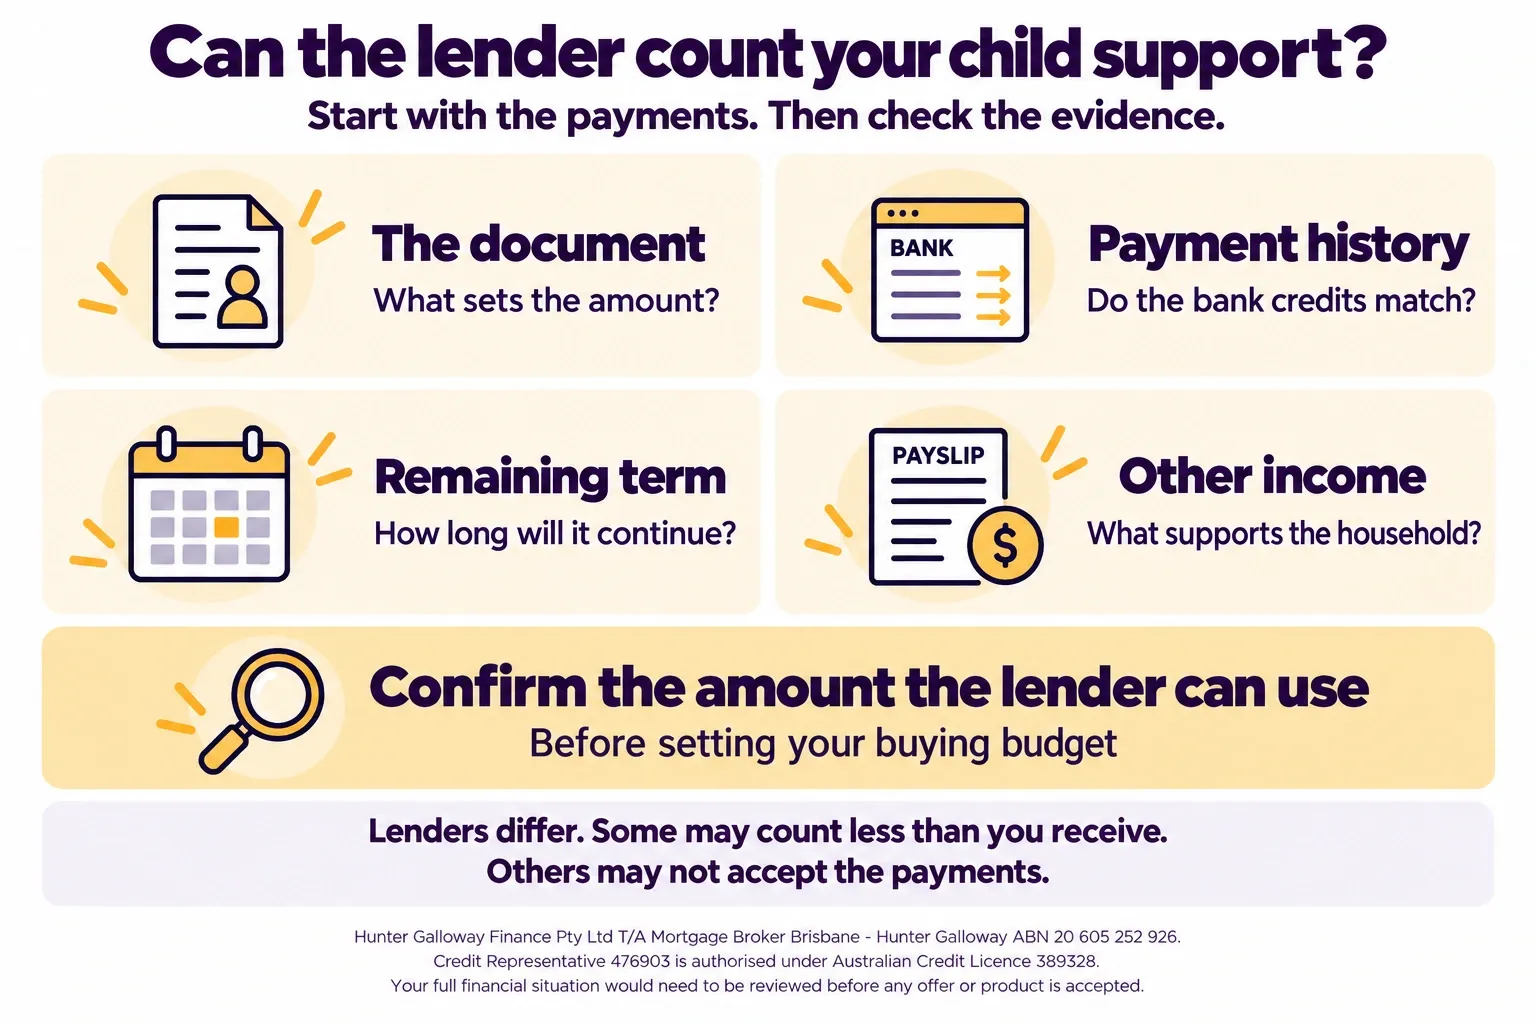
The payments reaching your account are the starting point. I then check 4 things.
What document sits behind the payment?
A current CSA assessment, court order, binding agreement or limited agreement can show who pays, how much is due and when it ends. Different lenders accept different combinations. A private text message or informal understanding will not meet every lender's rules.
Do the account credits match?
The required payment history depends on the lender. I check the amount, date, description and any missed payments. If the support recently increased, I check which amount the history supports before using the newer figure in a borrowing estimate.
How long will it continue?
The child's age matters because many lenders want the income to continue for several years. One lender may be comfortable with the remaining term while another may stop using the income much earlier. Where there are several children, the lender may split the payment rather than use one household total.
How much of the household income comes from support?
Child support is usually treated as extra income alongside salary, business income or another accepted source. Some lenders restrict it where it becomes the main income. That is why a calculator that simply adds the full weekly payment to a salary can give a false result.
What evidence makes the difference?
The agreement and the money arriving in your account need to tell the same story. Before relying on child support in your buying budget, I check these points with the lender being considered.
| Evidence | What we need to establish |
|---|---|
| Assessment, agreement or court order | The amount due, who receives it and how long it is expected to continue. |
| Bank statements | The amount actually received, payment dates and any missed or catch-up payments. |
| Children's ages and care arrangement | The remaining support period and the household costs the lender needs to assess. |
| Your other income | Whether the household can meet the new loan and whether the lender accepts support alongside that income. |
What evidence makes the difference?
Assessment, agreement or court order
- What we need to establish
- The amount due, who receives it and how long it is expected to continue.
Bank statements
- What we need to establish
- The amount actually received, payment dates and any missed or catch-up payments.
Children's ages and care arrangement
- What we need to establish
- The remaining support period and the household costs the lender needs to assess.
Your other income
- What we need to establish
- Whether the household can meet the new loan and whether the lender accepts support alongside that income.
What if the child support is arranged privately?
Start by separating Private Collect from an informal arrangement. With Private Collect, an assessment, agreement or court order sets the amount, and parents arrange the payments themselves. An informal arrangement may have no such document.
That distinction matters for a home loan. Regular transfers show what you receive, but the lender may still need evidence of the agreed amount and how long it will continue.
A formal agreement or court order can create more options. If that is not available yet, the next question is whether there is enough payment history to ask for a manual exception. That is what worked for Kirsty.
I would not tell someone to wait automatically. I would first check the dates and evidence already available. There is a big difference between 2 irregular transfers and 6 months of the same payment arriving every week.
If you pay child support, the bank normally treats it as a cost
Child support paid is not subtracted from your salary and forgotten. The lender normally records the payment as an ongoing commitment or living cost.
The care arrangement and dependants also matter. Some lenders count the child as a dependant and record the support separately. Others treat lower levels of care differently. I check your arrangement so the application includes the right costs without counting the same expense twice.
Private school fees, health insurance, medical costs and other expenses paid outside the child-support amount may still need to be included. Kirsty's ex-partner covered most child costs outside food at her home, but that did not mean we could ignore the household expenses she still paid.
Family Tax Benefit is a separate income question
Family Tax Benefit is assessed separately from child support. The home loan guide for single mothers brings the income, deposit and government-backed options together, so you can check the whole buying position.
What should you have ready?
- your current CSA assessment, court order or signed child-support agreement, if one exists
- recent bank statements showing the payments, ideally covering up to 6 months if you have them; the lender may ask for a different period
- the date payments started and any recent change in the amount
- the ages of the children and when the payments are due to end
- your care arrangement and who lives in each household
- school fees, medical costs, insurance or other child expenses paid separately
- Family Tax Benefit statements, if you receive it
- details of your salary, HECS debt, cards, loans and the home you want to buy
You do not need to solve every lender rule yourself. Send me the documents you already have and I can tell you what is missing before we rely on the income in a buying budget.
Frequently asked questions
Experience and sources
How this guide was checked
We checked the child-support arrangements and collection guidance against Services Australia and the lender source below on 21 September 2026. The client example shows an individual lending exception. We confirm current evidence requirements and the income a lender will accept for each application.
Jayden Vecchio is a mortgage broker at Hunter Galloway. Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328.
Sources
General information only. Lender requirements can change and applications are subject to credit approval. Client examples describe individual outcomes.
Related guides
- Start here
Divorce and separation home loans
Work out whether the next step is keeping, selling, buying elsewhere or waiting.
Read guide - Related guide
Home loans for single mothers
Check income, deposit and government-backed options together.
Read guide - Related guide
Calculate a property buyout
Work out the loan and cash needed to keep the home.
Read guide - Related guide
Home loans during parental leave
How a return-to-work date and employer letter may help.
Read guide - Related guide
HECS debt and home loans
See how the repayment affects the borrowing calculation.
Read guide
Let me check whether your child support can count
Send me the arrangement and payment history you already have. I will check the evidence, the amount that may be counted and whether it is worth asking a lender to review the situation now.
or call 1300 088 065
Your full financial situation would need to be reviewed before any offer or product is accepted.
About this information: General information only. It is not legal, financial, tax or credit advice. Obtain legal advice before changing or entering a child-support arrangement. Lending rules can change and every loan remains subject to the lender's full assessment.
Client examples are based on real situations. Names and identifying details have been changed.