

You may be able to buy with 10% plus costs and no Lenders Mortgage Insurance (LMI). The options include a first-home offer for education workers and a general no-LMI loan. Eligible buyers can also check the government scheme with a minimum 5% deposit.
I'd start with your employment agreement and pay history. A permanent salary, a fixed-term contract and relief teaching can produce different borrowing figures, even when you have the same deposit.
- 01
Education-sector offer
Bank First publishes an offer for eligible first home buyers in education with 10% plus costs. You must live in the home; loans above 80% carry a higher interest rate. Hunter Galloway does not offer Bank First loans. We include this option for comparison only; you would need to apply directly with Bank First.
- 02
General loan without LMI
ubank offers eligible home or investment purchases with 10% plus costs and principal and interest repayments. You do not need to be a teacher or first home buyer.
- 03
Government 5% Deposit Scheme
Eligible buyers may start with 5% plus costs. You must live in the home and meet the buyer, local price-cap and participating lender requirements.
This guide is part of our LMI Waivers hub. Use our deposit calculator and LMI guide to work through the starting costs.
Find out which smaller-deposit option fits your teaching income
How much deposit will you need?
Say you're buying an $800k home with $200k saved. Assume the valuation matches the price and buying costs are $25k. For a standard 90% loan, assume a $15k LMI premium paid upfront. These are comparison assumptions, not a lender quote or a stamp-duty calculation.
| Option | Deposit and loan | LMI and cash remaining |
|---|---|---|
| Eligible no-LMI loan at 90% | $80k deposit; $720k loan | $0 LMI; $95k left |
| Standard 90% loan with assumed LMI | $80k deposit; $720k loan | $15k LMI paid upfront; $80k left |
| Standard loan at 80% | $160k deposit; $640k loan | Usually no LMI; $15k left |
Buying an $800k home with $200k saved and $25k assumed buying costs
Eligible no-LMI loan at 90%
- Deposit and loan
- $80k deposit; $720k loan
- LMI and cash remaining
- $0 LMI; $95k left
Standard 90% loan with assumed LMI
- Deposit and loan
- $80k deposit; $720k loan
- LMI and cash remaining
- $15k LMI paid upfront; $80k left
Standard loan at 80%
- Deposit and loan
- $160k deposit; $640k loan
- LMI and cash remaining
- Usually no LMI; $15k left
The 90% no-LMI loan keeps $80k more in your savings than the 80% loan, but you owe $80k more. Against the standard 90% loan, it saves the assumed $15k premium. I'd compare the repayments and fees alongside those upfront figures.
If LMI is added to the loan instead of paid upfront, your debt rises and you pay interest on the premium. Whether that fits depends on the lender’s maximum loan. Your actual premium and buying costs may differ from these assumptions.
Allow for conveyancing, inspections, registration charges and any stamp duty after concessions. The government scheme is a separate eligibility check and is not included in this cash comparison.
How lenders assess teaching income
Your contract tells us how the job is structured; your payslips show what it pays. I'd check both, particularly if you've changed schools, moved from casual to permanent work or have a contract ending before settlement.
| How you work | What to bring | Why it helps |
|---|---|---|
| Permanent teaching | Payslips and contract showing hours and salary | Shows your ongoing pay and whether probation has ended. |
| Fixed-term contract | Current agreement, earlier contracts and renewal evidence | Helps explain continuity when the current contract has an end date. |
| Casual or relief teaching | Earnings history across terms, income statements and current payslips | Shows paid days and gaps, rather than treating a busy fortnight as a normal full year. |
| Tutoring or a second job | Separate payslips or business records | Lets the bank assess that income separately from your school salary. |
Documents that explain your employment
Permanent teaching
- What to bring
- Payslips and contract showing hours and salary
- Why it helps
- Shows your ongoing pay and whether probation has ended.
Fixed-term contract
- What to bring
- Current agreement, earlier contracts and renewal evidence
- Why it helps
- Helps explain continuity when the current contract has an end date.
Casual or relief teaching
- What to bring
- Earnings history across terms, income statements and current payslips
- Why it helps
- Shows paid days and gaps, rather than treating a busy fortnight as a normal full year.
Tutoring or a second job
- What to bring
- Separate payslips or business records
- Why it helps
- Lets the bank assess that income separately from your school salary.
For relief work, a busy fortnight can overstate the income you receive over a year. Bring earnings across school terms and holidays so we can show the pattern rather than assume every week is paid.
| Calculation | Annual income |
|---|---|
| 3 days × $450 × 40 paid weeks | $54k |
| The same weekly pay incorrectly extended across 52 weeks | $70,200 |
| Amount overstated by ignoring 12 unpaid weeks | $16,200 |
Worked assumption: $450 a day, 3 days a week, 40 paid weeks
3 days × $450 × 40 paid weeks
- Annual income
- $54k
The same weekly pay incorrectly extended across 52 weeks
- Annual income
- $70,200
Amount overstated by ignoring 12 unpaid weeks
- Annual income
- $16,200
The $450 daily rate and 40 paid weeks are hypothetical. This illustrates why unpaid periods matter; it is not a teacher pay rate or a named bank’s assessment formula. A lender may use a different evidence period or method, and your actual work pattern may be steadier or more variable.
If you’re a relief teacher, include income records covering school holidays as well as busy teaching periods. That helps the lender work out your annual income from the work you regularly get.
If you tutor through an ABN, include income and expenses. Your tutoring receipts are not the same as personal income after business costs. Our self-employed loan guide explains the documents.
Include your HECS or HELP debt and any credit cards, car finance or other commitments. Income accepted by the bank and the amount it will lend are separate figures.
Which low deposit option suits your purchase?
| Option | Who and what may fit | Main restriction |
|---|---|---|
| Bank First education-sector offer | Eligible first home buyers in education; up to 90% lending for a home to live in. | Above 80% carries a higher rate. No off-the-plan or construction waiver; no equity release on refinanced loans. Confirm current availability directly. |
| ubank general no-LMI purchase | Eligible home or investment purchases at up to 90%; principal and interest repayments. | Not a teacher-specific waiver. Income, property and credit requirements apply. |
| Government 5% Deposit Scheme | Eligible buyers with at least 5% plus costs; owner-occupied home within the local price cap. | Buyer eligibility and participating lender approval required. It does not cover an investment purchase. |
Teacher options: public sources checked 11 September 2026
Bank First education-sector offer
- Who and what may fit
- Eligible first home buyers in education; up to 90% lending for a home to live in.
- Main restriction
- Above 80% carries a higher rate. No off-the-plan or construction waiver; no equity release on refinanced loans. Confirm current availability directly.
- Who and what may fit
- Eligible home or investment purchases at up to 90%; principal and interest repayments.
- Main restriction
- Not a teacher-specific waiver. Income, property and credit requirements apply.
Government 5% Deposit Scheme
- Who and what may fit
- Eligible buyers with at least 5% plus costs; owner-occupied home within the local price cap.
- Main restriction
- Buyer eligibility and participating lender approval required. It does not cover an investment purchase.
What could change your options?
Interest rate and fees
Compare repayments, establishment costs, ongoing fees and discharge costs. Avoiding the premium is only one part of the cost.
Offset and extra repayments
An offset can keep savings accessible while reducing interest. Check account fees and restrictions on fixed loans.
Property and purpose
An investment, regional property, small unit or construction project may fall outside an advertised offer. Have the address checked before relying on it.
Employment terms
Casual work, probation, changing contracts or irregular overtime can affect the income accepted and the evidence required. Compare the lender assessment before setting your budget.
Refinancing
A purchase offer may not apply to refinancing. Include exit costs and avoid extending the term just to make repayments look lower.
If you already own a property, our refinancing guide explains the comparison. A higher valuation or smaller outstanding loan may give you enough equity to refinance without an occupation-based offer.
What if you have less than a 10% deposit?
For an eligible $800k purchase under the government scheme, a minimum 5% deposit is $40k and a 95% loan is $760k, before buying costs. That is $40k more debt than borrowing 90%. These starting figures do not establish eligibility or mean you can keep all other savings; the participating lender checks your required contribution.
The 5% route is a government guarantee for eligible buyers, rather than a blanket 95% teacher waiver. You must live in the home and meet the scheme and lender requirements. Our government scheme guide explains the next checks.
A family guarantor loan may help where savings are the barrier. The family member puts property at risk, so compare the guarantee amount and release plan and get independent advice. It does not replace the income you need to repay the loan.
Paying LMI can also be worth comparing if it gives you a suitable property, employment policy or loan structure. Use an actual premium quote and total-cost comparison before deciding that every no-LMI offer is better.
What to send us for a useful answer
Bring the documents that explain your work and deposit
- Your current employment agreement, including hours, probation and any contract end date.
- Recent payslips and income records across school terms and holidays if your hours vary.
- Earlier contracts or a written renewal where they help explain ongoing work.
- Separate payroll or business records for tutoring and second-job income.
- Savings, HELP debt, other loans and credit limits, plus the property price, address and intended use.
We first check which income a suitable lender can use, then compare the deposit, actual LMI quote and repayments. From there we can help prepare the application and explain what is still needed for approval. Our pre-approval guide explains that stage.
Get your teaching income and deposit checked before you apply
Common questions from teachers
Experience and sources
How this guide was checked
We checked the public lender and government sources below on 11 September 2026. This guide separates education-sector eligibility, general no-LMI lending and income assessment. The deposit and relief-pay examples use stated assumptions; they are not client outcomes or lender quotes.
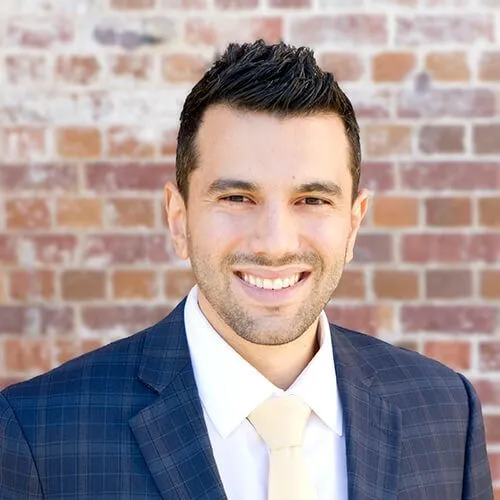
Jayden has worked in finance since 2006 and joined Hunter Galloway in 2018 after working in private and commercial banking. He holds a Bachelor of Business and a Certificate IV in Finance & Mortgage Broking.
Hunter Galloway Finance Pty Ltd is Credit Representative 476903, authorised under Australian Credit Licence 389328.
Sources
Public-source check: 11 September 2026. Confirm current lender availability, property restrictions and income requirements for your application.
Lenders pay us upfront and ongoing commissions when we arrange eligible loans. The initial assessment is free. If we charge a fee for helping with your application, we'll explain it before you proceed. Lender and other third-party costs may still apply. How we review lenders explains our approach.
Find out how much of your teaching income counts
Send us your employment agreement, recent payslips and deposit details. We'll compare how lenders we offer count your teaching income and what that means for your buying plans.
or call 1300 088 065
We assess your full financial situation before recommending a loan.