

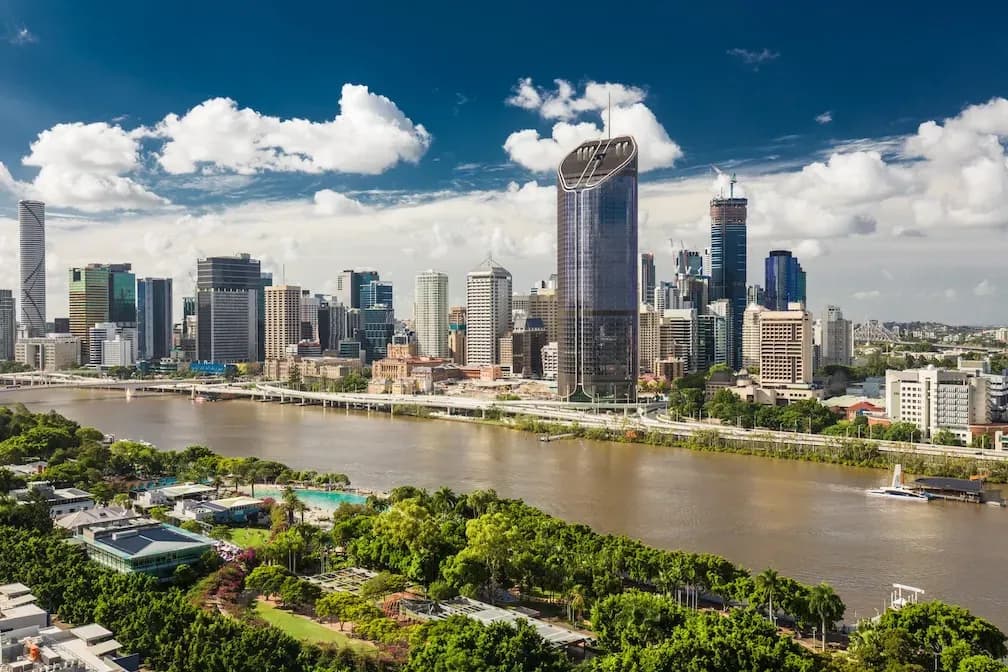
If you've got $800,000 to spend on an investment property, Queensland gives you some very different choices. You could look at a Brisbane unit, a house in Toowoomba or Townsville, or spend considerably less on a Cairns unit. I'd compare those options before deciding that the next purchase has to be close to home.
The five markets are Chermside and Woolloongabba units in Brisbane, Harristown houses in Toowoomba, Kirwan houses in Townsville and Manunda units in Cairns.
My starting question is how much you can comfortably put towards the property each week after the rent comes in. A suburb can look great on a hot-spot list and still leave you with a loan, insurance bill or body corporate levy that makes it hard to hold.
Below, I'd compare the sale and rental figures, then check the costs and property details before making an offer.
Five Queensland markets to compare
Suburb medians: September 2025 to August 2026
Scroll to see more columns
| Suburb and property type | Median sale price | Weekly rent | Sales / leases |
|---|---|---|---|
| Chermside units (Brisbane) | $800,000 | $650 | 228 / 559 |
| Woolloongabba units (Brisbane) | $812,000 | $730 | 152 / 612 |
| Harristown houses (Toowoomba) | $750,000 | $580 | 133 / 174 |
| Kirwan houses (Townsville) | $673,000 | $580 | 391 / 481 |
| Manunda units (Cairns) | $365,000 | $450 | 87 / 117 |
Source: realestate.com.au, September 2025–August 2026; checked 1 October 2026. Medians cover each property type, not a particular bedroom count.
The prices and rents come from separate groups of properties. Don't assume you can buy at the median and receive the median rent. Use these figures to narrow your search, then get a rental appraisal and recent comparable sales for the home you're considering.
Start with Kirwan and Harristown. Look closely at land, building condition and the cost of maintaining the home.
Compare Chermside with Woolloongabba. The suburb matters, but the building and its levies can decide which property works.
Manunda has the lowest median in this shortlist. Get the body corporate and insurance figures before treating the lower price as a bargain.
Start with your work trip, household and budget. Our Brisbane suburb guide is a better fit for comparing places to call home.
1. Chermside units: compare the building carefully
Chermside gives you an established Brisbane location with Westfield, a bus interchange and The Prince Charles Hospital. Those are useful everyday services for renters. Check the walk or bus connection from the unit itself; being in the same suburb doesn't make every building equally convenient.
The unit median was $800,000, with median rent of $650 a week. There were 228 sales and 559 leases in the source period, giving you a reasonable pool of transactions to research. Narrow that down to units with similar bedrooms, parking, floor area and condition.
For me, the body corporate records would be an early read. A pool, lifts and shared facilities can add costs, while planned repairs can change what you need to contribute. Compare the annual levies, sinking fund and upcoming work alongside the rent. A slightly cheaper unit can lose its price advantage surprisingly quickly.
2. Woolloongabba units: inner-city access, without betting on the Games
Woolloongabba's unit median was $812,000, only $12,000 above Chermside, while its median weekly rent was $730. That makes it worth comparing if your budget is around $800,000. It doesn't establish which individual unit offers the better return.
The suburb already has the PA Hospital and inner-city access. Cross River Rail is another reason to investigate the location, with first passenger services expected in 2029. Base today's rental appraisal on the connections available now, and account for construction nearby.
I wouldn't pay extra just because a listing mentions the Olympics. The new Olympic stadium is planned for Victoria Park. The proposed Gabba indoor arena and housing precinct is a separate project. Neither project tells you what a particular apartment will be worth when you sell.
Look at the floor plan, natural light, parking, noise and the number of similar units available. Our property valuation guide explains how to use comparable sales before you settle on an offer.
Our apartment mortgage guide explains the finance checks to make before committing to a unit.
3. Harristown houses: a regional house alternative
If you prefer a house to a unit, Harristown in Toowoomba gives you a useful comparison. Its $750,000 house median was below both Brisbane unit medians above, with rent of $580 a week. The figures cover 133 sales and 174 leases.
Harristown has its own state high school, while UniSQ's Toowoomba campus is in neighbouring Darling Heights. Think about who the particular house would suit and how they would get to work, study or school. A local property manager should be able to show you comparable leases, rather than just give you an optimistic asking rent.
An older house can give you more space and control over the property, but you're responsible for the roof, drainage and repairs. Have the building and pest inspection done, price the work it needs and allow for ongoing maintenance. Check the address for flood and overland-flow exposure as well.
4. Kirwan houses: a lower house price, with insurance in the budget
Kirwan's $673,000 house median puts it $77,000 below Harristown in this comparison. Both had a $580 weekly rent median. That price difference is worth investigating, provided the property's running costs and condition also stack up.
Kirwan is part of Townsville's established urban area, with Kirwan Health Campus and nearby shopping at Willows in Thuringowa Central. I'd look for a practical home with a layout, cooling and parking that suit local renters, then ask a manager which similar properties are actually leasing.
Get an insurance quote before you commit. Read the flood information for the block and access roads, have the roof and drainage inspected, and understand the policy's cover and excesses. The attractive purchase price needs to survive those checks. Don't leave them until after you've negotiated the contract.
5. Manunda units: the smallest entry budget on this list
Manunda in Cairns is a very different purchase from the Brisbane units. Its unit median was $365,000 and rent was $450 a week, based on 87 sales and 117 leases. It is the lowest-priced market in this shortlist, so you can investigate a purchase with a smaller deposit and loan.
The suburb has TAFE Queensland's Cairns campus and Raintrees Shopping Centre. For this comparison, I'm looking at ordinary long-term residential letting. A holiday-rental income estimate needs separate research into permission, occupancy, management and costs.
Before getting excited about the rent relative to the price, read the body corporate minutes, levies, insurance schedule and planned work. With a unit, you share costs for common property as well as looking after your own interior. For Cairns flood and storm-tide information, use the council's property searches and obtain actual insurance information; a broad map won't answer every question about the building.
Still comparing Greater Brisbane?
Ashgrove, Capalaba and Shailer Park also belong on a Brisbane-area unit search if their locations suit you. Here are the current figures so you can put them beside Chermside and Woolloongabba.
Three more unit markets: September 2025 to August 2026
Scroll to see more columns
| Units | Median sale price | Weekly rent | Sales |
|---|---|---|---|
| Ashgrove | $940,000 | $650 | 59 |
| Capalaba | $760,000 | $600 | 83 |
| Shailer Park | $697,000 | $550 | 21 |
Source: realestate.com.au, September 2025–August 2026; checked 1 October 2026. Shailer Park has only 21 sales; interpret its median carefully.
Ashgrove has the highest unit median of these three. Capalaba and Shailer Park provide lower-priced alternatives in the Redlands and Logan areas. With the smaller Shailer Park sales sample, a few different properties can shift the median. Fewer sales do not mean fewer competing rentals.
For a wider location search, use our Brisbane suburb guide or compare Ipswich house and unit prices. If you're happy renting where you want to live while buying elsewhere, our rentvesting guide covers how to think through that decision.
What the broader market is telling us
The newer September figures show why I'd be careful about chasing last year's growth. Cotality's 1 October Home Value Index report puts Brisbane dwelling values down 1.5% in September and regional Queensland down 0.9%. Brisbane was still 5.9% higher over the year. Those broad value indexes don't replace the suburb sale medians above or tell us what an individual property should sell for.
Queensland is moving at different speeds. REIQ's June 2026 quarter figures show Brisbane unit medians down 0.57% over the quarter, Toowoomba houses up 3.03%, Townsville houses flat and Cairns units up 4.35%. These are council-area figures for the June quarter, so don't compare them directly with the suburb table.
Rental markets were tight across these four areas in the same quarter: vacancy was 1.0% in the Brisbane council area, 0.6% in Toowoomba, 0.9% in Townsville and 0.8% in Cairns. A regional vacancy rate won't tell you how quickly your property will lease. Ask about recent local results, including homes that needed a rent reduction.
The cash-rate target is 4.60%, effective 30 September 2026. On the same day, the ABS released August inflation: 4.0% annually, with underlying inflation steady at 3.6%. Your investment loan rate is separate from the cash rate, so use a current quote in your budget. I wouldn't rely on a rate cut or price growth to make the purchase affordable. Our Brisbane property market guide covers the capital-city picture in more detail.
How much might you need to contribute each week?
Here's how I'd compare the cash cost before choosing between suburbs. Take an $800,000 unit renting for $650 a week, with a $160,000 deposit from your own funds and a $640,000 interest-only loan. Buying costs come from separate funds. For this example, assume a 6.5% loan rate, two weeks without rent and the annual costs below. The rate and expenses are assumptions, not a loan offer or a quote for a particular property.
Worked annual budget for an $800,000 unit
Scroll to see more columns
| Item | Annual amount |
|---|---|
| Rent collected: $650 × 50 weeks | $32,500 |
| Management: 7% of collected rent | −$2,275 |
| Rates and owner-paid water charges | −$3,000 |
| Landlord insurance | −$1,500 |
| Maintenance allowance | −$1,500 |
| Body corporate levies | −$4,500 |
| Left for the loan | $19,725 |
| Loan interest: $640,000 × 6.5% | −$41,600 |
| Annual amount you contribute | $21,875 |
| Average weekly contribution | About $421 |
That's about $421 a week from your own budget, before tax effects or principal repayments. Buying costs, any land tax, letting fees and unexpected repairs are extra. Borrowing the deposit would add another loan cost. A principal-and-interest loan would require a higher payment. Replace every assumption with the figures for the property, and check what building insurance the body corporate levy already covers so you don't count it twice.
Before counting on a tax refund, check the new negative-gearing rules. From 1 July 2027, rental losses on established residential property bought under a contract entered into at or after 7:30pm AEST on 12 May 2026 generally can't offset your wages. Deductions can still offset residential rental income; unused losses may reduce eligible residential capital gains or carry forward. Earlier holdings and qualifying new builds are excluded from this restriction. I'd get tax advice before using a refund to make the weekly budget work.
This is where two properties at the same price can give you very different results. Higher rent helps, but so do lower levies and a building that doesn't need expensive work. Our investment loan guide explains the finance side, including how lenders assess rental income.
Do the finance and property checks before committing
If you're using equity from your current home for the deposit, include that extra borrowing in the budget too. Equity can help fund the purchase, but the released amount is still debt you need to service. On an $800,000 purchase, a 20% deposit is $160,000 before buying costs.
Lender choice matters, particularly if you already own investment properties. Banks have limits on the share of new lending they can make at a debt-to-income ratio of six or more. That isn't a six-times-income borrowing entitlement or a blanket ban above it. We can compare how lenders treat your rent, existing loans and the property itself.
Check flood and overland-flow information for every address, including the Brisbane units and their common property. Have your conveyancer review the contract and arrange the relevant searches, building inspection and body corporate records. Our property research guide helps you build a shortlist, and the making an offer guide covers the next step.
First-home grants and deposit schemes have owner-occupier conditions. Don't include them in the budget for a property you intend to hold purely as an investment. If you plan to live in it first, check each program's occupancy rules before assuming you can rent it out later. Our Queensland grant and 5% Deposit Scheme guides explain the separate requirements.
Queensland property investment questions
Sources
Sources and how we chose these markets
Checked 1 October 2026. We chose these five markets to compare different Queensland regions, entry budgets and property types, using existing services and available sale and leasing evidence. This is an editorial shortlist, not a forecast or a ranking of future returns. All suburb medians use realestate.com.au profiles for September 2025 to August 2026, linked in the tables. Each main selection has at least 20 sales and 20 leases; sample counts are shown. REIQ figures are regional June-quarter data and are kept separate. Government, council and facility sources support the location and finance information. The cash-cost example uses stated assumptions and excludes tax effects.
References
- Housing Australia: 5% Deposit Scheme eligibility and ongoing obligations
- REIQ: June 2026 quarter property market
- REIQ: June 2026 quarter rental vacancies
- RBA: 29 September 2026 cash-rate decision
- The Prince Charles Hospital: location
- Westfield Chermside: transport and directions
- PA Hospital: location and transport
- Cross River Rail: current project timing
- GIICA: Brisbane Stadium at Victoria Park
- Queensland Government: Gabba entertainment and housing precinct
- Queensland Education: Harristown State High School
- UniSQ: Toowoomba campus in Darling Heights
- Townsville Health: Kirwan services
- Willows Shopping Centre: location
- TAFE Queensland: Cairns campus
- Raintrees Shopping Centre: location
- Brisbane Council: FloodWise property reports
- Toowoomba Council: flood risk information
- Townsville Council: flood mapping
- Cairns Council: flood information and map limitations
- Cairns Council: property searches
- APRA: debt-to-income limits effective 1 February 2026
- Queensland Government: First Home Owner Grant eligibility
- ABS: August 2026 CPI, released 30 September
- CBA Economic Insights (client research note): Lucinda Jerogin, Home prices fall further in September while credit growth holds steady in August, 1 October 2026, pages 1-2. Regional Queensland monthly and Brisbane annual Cotality figures.
- Cotality: Australian housing values down for sixth straight month in September, 1 October 2026
- Cotality Home Value Index, released 1 October 2026: September dwelling values
- Treasury Laws Amendment (Tax Reform No. 1) Act 2026: Schedule 2, negative-gearing changes from the 2027-28 income year
General information only. This doesn't consider your objectives, financial situation or needs. Rates, policies and figures change, so confirm current details before acting. Loans are subject to lender approval.
Keep researching your purchase
Work out what you can comfortably invest
Tell us your deposit or equity, existing loans and the property budget you have in mind. We'll compare lenders and help you understand the repayments before you start making offers.
or call 1300 088 065
Your full financial situation needs to be assessed before a loan can be recommended.